
How Investors May Respond To Agree Realty (ADC) Stronger Quarterly Earnings
- Agree Realty reported third quarter 2026 sales and revenue of US$213.8 million and net income of US$68.4 million, with diluted EPS from continuing operations of US$0.53, alongside nine month 2026 revenue of US$619.8 million and net income of US$185.1 million.
- For readers tracking operating momentum at Agree Realty, the nine month figures show higher sales, revenue and net income than the same period a year earlier. This highlights how the portfolio is currently supporting higher earnings per share from continuing operations.
- We will now look at how Agree Realty's investment narrative is influenced by this year over year EPS progress across the latest quarter.
Scan how Agree Realty's latest earnings compare with peers by reviewing list of solid balance sheet and fundamentals (24 results) anchored by consistent operating performance.
Agree Realty Investment Narrative Recap
To own Agree Realty, you need to be comfortable with a REIT that leans heavily on external funding while trying to scale a large, net lease retail portfolio. The latest quarter supports that narrative. Revenue and net income for both the third quarter and first nine months of 2026 were higher than a year earlier, which helps near term confidence in rent collection and underwriting.
The key short term catalyst is whether management can keep deploying capital into new properties without letting higher funding costs eat into earnings from continuing operations. The biggest risk remains that interest expenses rise faster than rental income and that development costs stay elevated. This earnings release does not remove that risk but it does not materially worsen it either.
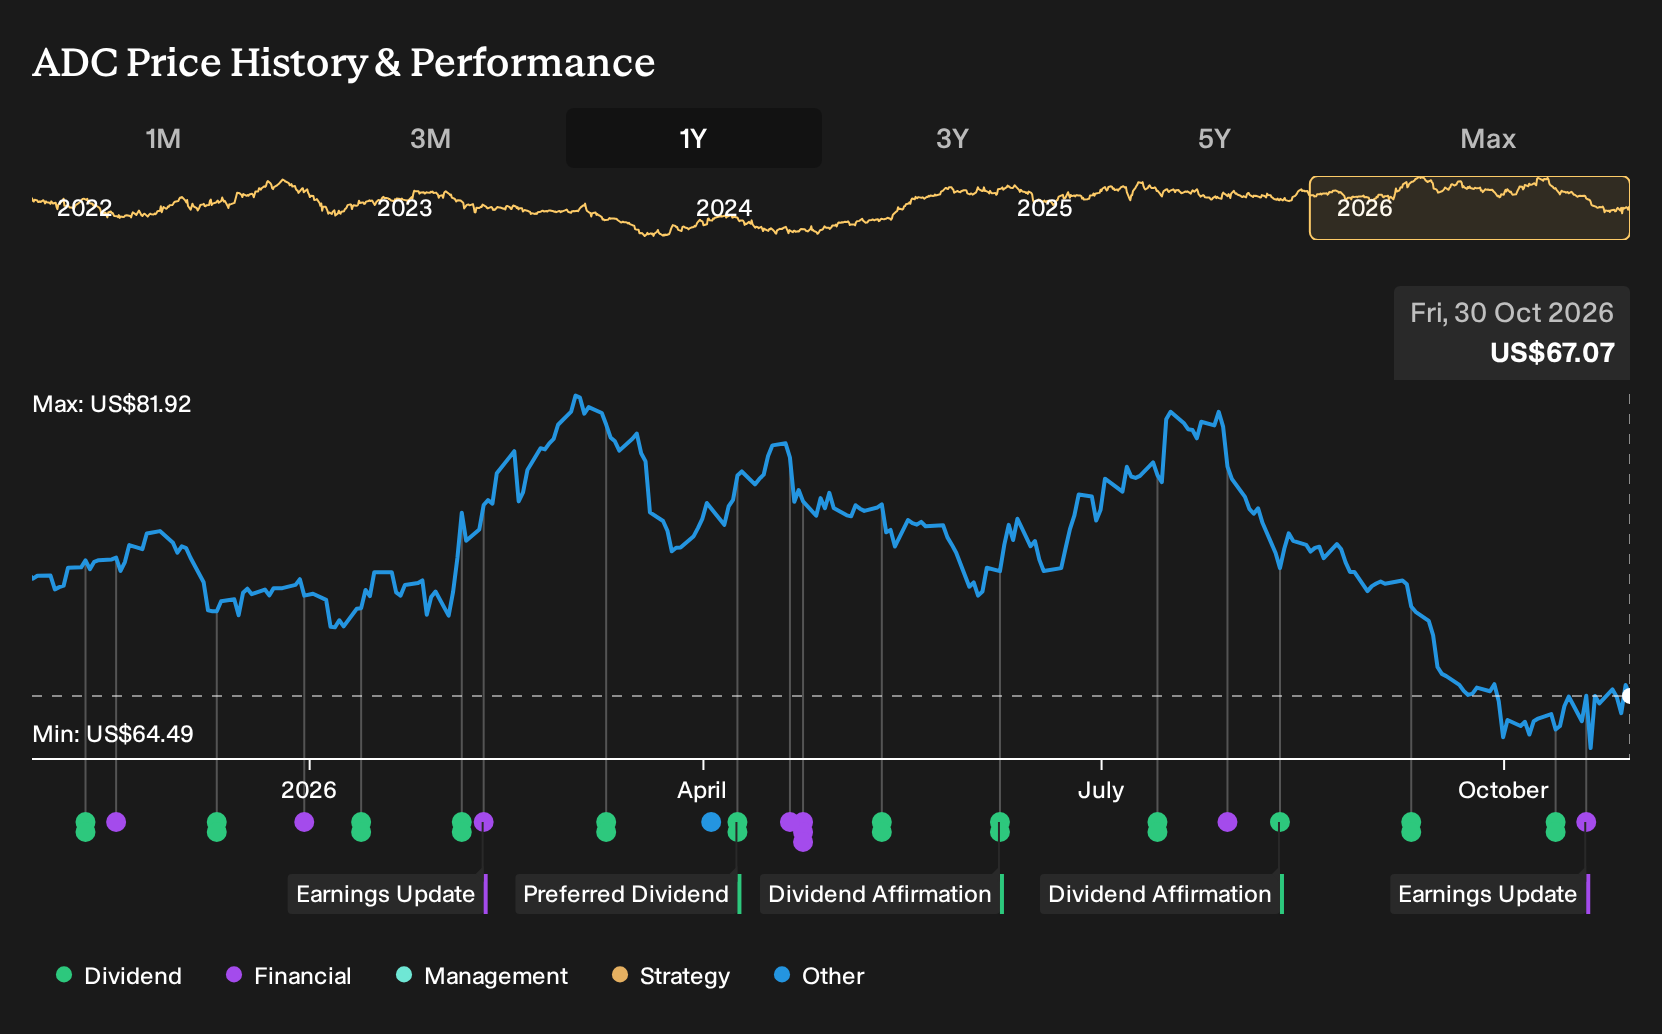
The most relevant data point for that debate is the earnings announcement on October 20, 2026. Agree Realty reported third quarter diluted EPS from continuing operations of US$0.53 compared with US$0.45 a year earlier, alongside higher revenue and net income for both the quarter and the first nine months of 2026 versus 2025.
For you as a shareholder, those figures feed directly into the existing catalysts. Higher EPS from continuing operations supports the case that the record capital deployment and focus on necessity based, largely investment grade tenants are translating into stronger cash generation. At the same time, the update arrives against a backdrop where interest payments are described as not well covered by earnings. The path from this point still hinges on how effectively Agree Realty manages its cost of capital and development economics.
Agree Realty's current earnings of US$217.0 million are set against analyst forecasts for earnings of US$314.9 million by 2029, implying an earnings increase of about US$98 million. The same projections point to revenue of US$1.1b by that year and assume 12.8% yearly revenue growth to reach that level.
Uncover why Agree Realty's fair value indicates a 20% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Two fair value views from the Simply Wall St Community span roughly US$80.67 to US$164.95, so private investors are treating Agree Realty as anywhere from heavily discounted to richly priced. Those opinions sit beside interest rate and construction cost risks, as well as capital deployment plans, which you can weigh as you explore more community viewpoints.
Explore another Agree Realty fair value estimate, including one that suggests as much as 146% upside from the current price!
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Agree Realty research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Agree Realty. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Agree Realty's overall financial health at a glance.
Looking for more investment ideas beyond Agree Realty?
Once you have a view on Agree Realty, it can help to widen the net and compare it with other opportunities that fit different risk and income profiles.
- For investors hunting for possibly underappreciated opportunities with solid fundamentals, review a curated 19 high quality undiscovered gems that might not yet be widely followed.
- If capital preservation and smoother portfolio swings matter most to you, consider a 29 resilient stocks with low risk scores that screens for businesses with more resilient profiles.
- For those who care about income and want potential yield backed by underlying fundamentals, scan a focused set of 5 dividend fortresses that could complement a REIT like Agree Realty.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com