
ASML Holding (ASML) Ties Pay To Morale Following Pullback But Is The Value Already Priced In
ASML Holding (NasdaqGS:ASML) just tied CEO and executive compensation to a new Workplace Experience Index that tracks employee morale, after a year of weaker engagement scores and planned management job cuts.
ASML Holding’s recent focus on culture is landing at a moment when the share price has slipped in the short term yet remains strong over longer periods, with the stock down over the past month and quarter but supported by a 34.55% year to date share price return and a 47.55% 1 year total shareholder return that builds on very large 3 year gains.
Scan how ASML Holding fits into the wider chip buildout and compare it with 54 AI infrastructure stocks powering the same long-term AI demand story.
The share price has cooled in recent weeks while ASML Holding still carries a premium reputation and hefty market value. Does that recent pullback leave enough upside in the current valuation to justify taking on new risk?
Most Popular Narrative: 13.5% Undervalued
ASML Holding last closed at $1,565.90, while the most followed valuation narrative pins fair value at $1,809.43. This implies a clear gap between what the market is paying and what that framework suggests the business could be worth.
My thesis is simple. ASML is a toll booth on the progress of semiconductors. Every new node, every new DRAM generation and every AI accelerator needs more lithography layers, and the most advanced layers can only be printed on ASML's tools. The moat is wide, with decades of R&D, a unique supplier network (Zeiss optics above all), deep customer integration and a growing installed base that produces recurring, high-margin service revenue.
See why 2 investors see ASML Holding as 13% undervalued.
Result: Fair Value of $1,809.43 (UNDERVALUED)
Still, ASML Holding faces clear risks if export rules on China tighten further or if customers slow AI and memory spending, which could challenge the view that the shares are undervalued.
Find out about the key risks to this ASML Holding narrative.
Another View: ASML Holding Looks Expensive On Earnings
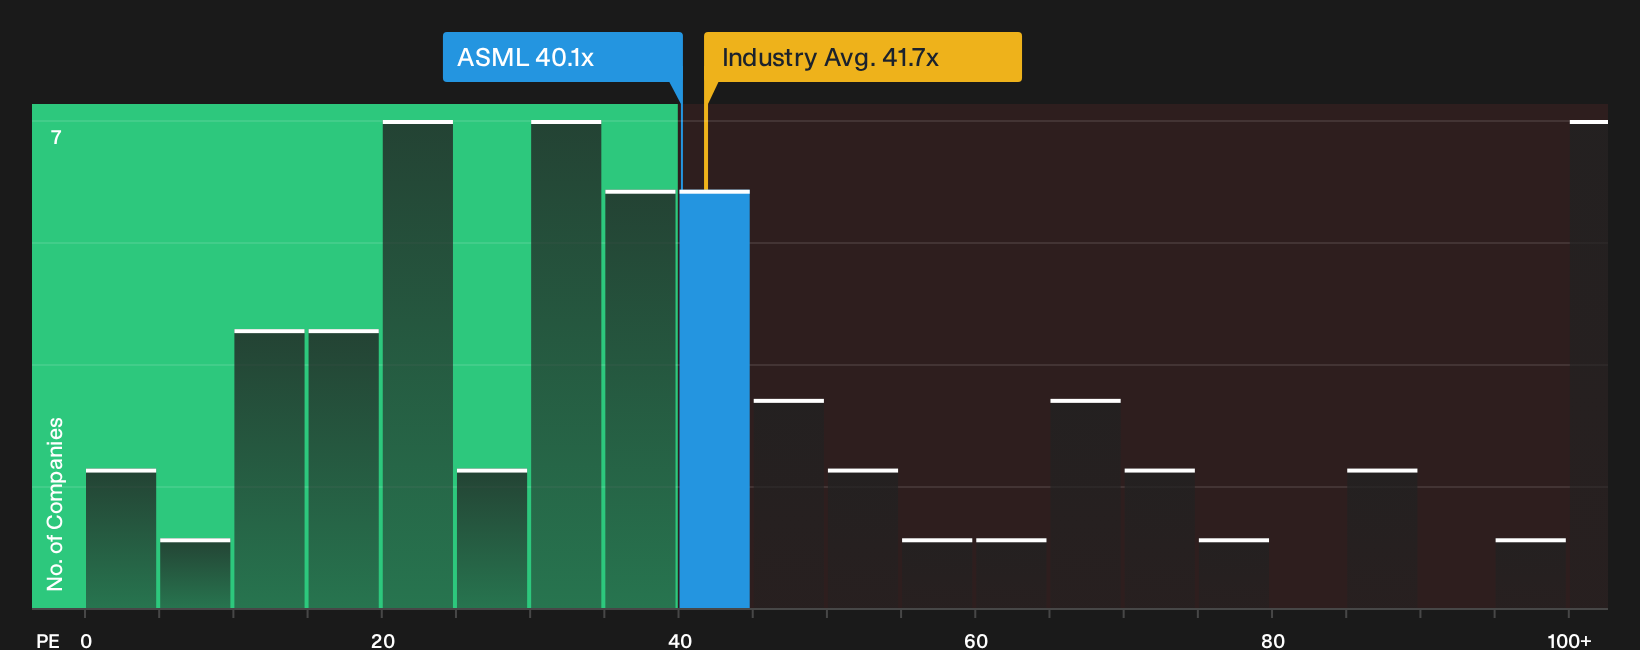
The user narrative leans on a fair value of $1,809.43, yet a different lens tells a tougher story. On a P/E of 40.1x, ASML Holding trades above a fair ratio of 33.7x and above peer averages at 34.8x, even if it sits slightly below the broader US Semiconductor group on 41.7x. That kind of gap can compress quickly if sentiment cools, so how comfortable are you paying up for this quality?
To see how the earnings multiple stacks up against what the numbers suggest the ratio could drift toward, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed views on ASML Holding's price and quality are clear in the numbers, so move quickly to scrutinize the data and shape your own stance. To understand why some investors still see upside potential based on specific strengths, review the 3 key rewards
Looking for more investment ideas beyond ASML Holding?
Do not stop with ASML Holding. Use the Simply Wall Street Screener to scan fresh opportunities that match your risk appetite, income needs, and quality focus.
- Target potential mispricings by reviewing a curated 33 high quality undervalued stocks that may offer stronger value than what is already on your radar.
- Lock in cash flow focus by checking a hand picked group of 5 dividend fortresses that might suit an income driven approach.
- Prioritise resilience by scanning a 29 resilient stocks with low risk scores that could help reduce portfolio volatility when markets turn rough.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com