
What Kingfisher Holders Got Right
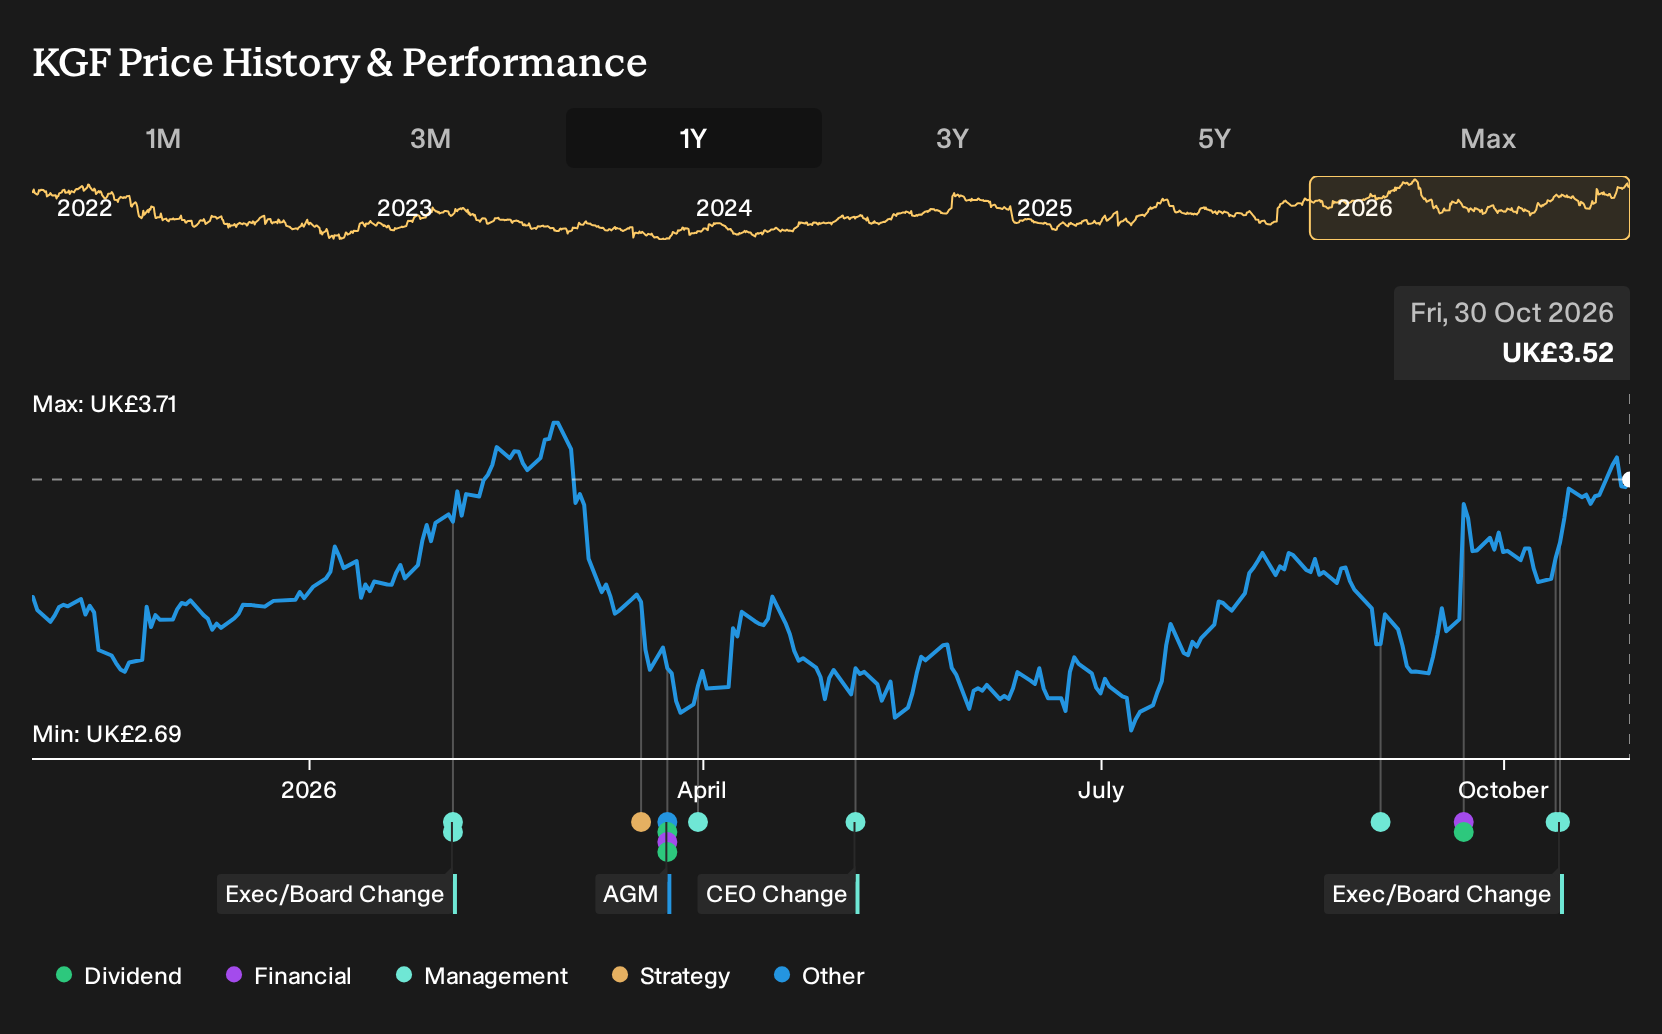
News of Kingfisher hiring former OBI chief Sebastian Gundel as CEO from 2027 sharpened the market’s focus on its push into digital and trade customers. Yet that leadership story landed only after the key twelve month window. For Kingfisher shareholders, the return over the past year was 20.2%, including dividends. If you were deciding on 30 October 2025, what would you have needed to believe about this retailer’s digital plans and eco renovation focus to hold through that outcome?
On Simply Wall St, a Narrative is an investor's thesis written down: the reasoning, plus the numbers it rests on. Run those numbers and you get an estimated Fair Value.
The move put Kingfisher in the middle of this trade. Scan 34 elite gold producer stocks for other companies exposed to it.
The Two Kingfisher Stories Investors Were Arguing About
The shares cost £3.13 at the start of the period, and Kingfisher sat between two sharply different but credible stories about its future.
The bullish narrative put fair value at £3.87, 24% above the start price. It focused on potential growth in e-commerce, trade customers, and eco-focused renovation products across France and Poland.
The bearish case set fair value at £2.35, 25% below the start price. It highlighted aging European demographics, weaker DIY demand, and online competition such as Amazon eroding margins.
What The Results Changed In The Kingfisher Debate
Kingfisher’s H1 2027 report gave the bullish camp fresh data. Revenue reached £6,864m with net income of £290m, compared with £6,811m and £237m a year earlier, and net margin moved from 3.5% to 4.2%. That supported the optimistic story about digital execution and eco renovation helping profitability, although it did not invalidate longer term demographic and competition worries.
The key lesson is about which promise to test. For any retailer built on a digital upgrade story, it may be useful to track net margin and absolute profit against that pitch rather than relying on headline sales or share price moves.
What Kingfisher’s Price Already Assumes Today
Kingfisher shares now trade at £3.52, up 20.2% over the past year. The selected Narrative’s Fair Value sits below that level based on its own assumptions.
The Narrative focuses on how much of the recent margin and cash gains can persist. A buyer today effectively assumes that trade and digital growth can offset mix pressure and thinner incremental efficiency gains. This raises the question of how that view aligns with the specific risks it outlines around margin dilution and store productivity.
"The main factor that needs to work in Kingfisher’s favor is the ability to translate higher trade penetration, digital growth and margin initiatives into sustained profit and cash generation, despite gross margin headwinds from trade, freight and supplier pricing. The recent structural gross margin gains from sourcing, logistics and inventory efficiencies are already sizable in basis point terms."
One Narrative disagrees with today's price. → See where this Narrative says Kingfisher should trade
Which Company Could Surprise You Next?
By the time a rally makes headlines, you are reading about returns someone else has already earned. Why not go straight to the source and look for your own contrarian opportunity? These three companies trade below our estimated value.
- Company 1 - 40% below our estimate - focuses on higher fee private market strategies that convert fundraising momentum into fee earning assets.
- Company 2 - 32% below our estimate - channels inflows into renewable focused real assets and tax efficient products for institutions and individuals.
- Company 3 - 43% below our estimate - expands an AI enabled price comparison and cashback platform into savings, investment and SME finance offers.
Three companies from the same screener. Open all 14 potentially undervalued companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com