
Learn Why The Bull Case For Huron Consulting Group Stock Could Change Following S&P Index Inclusion
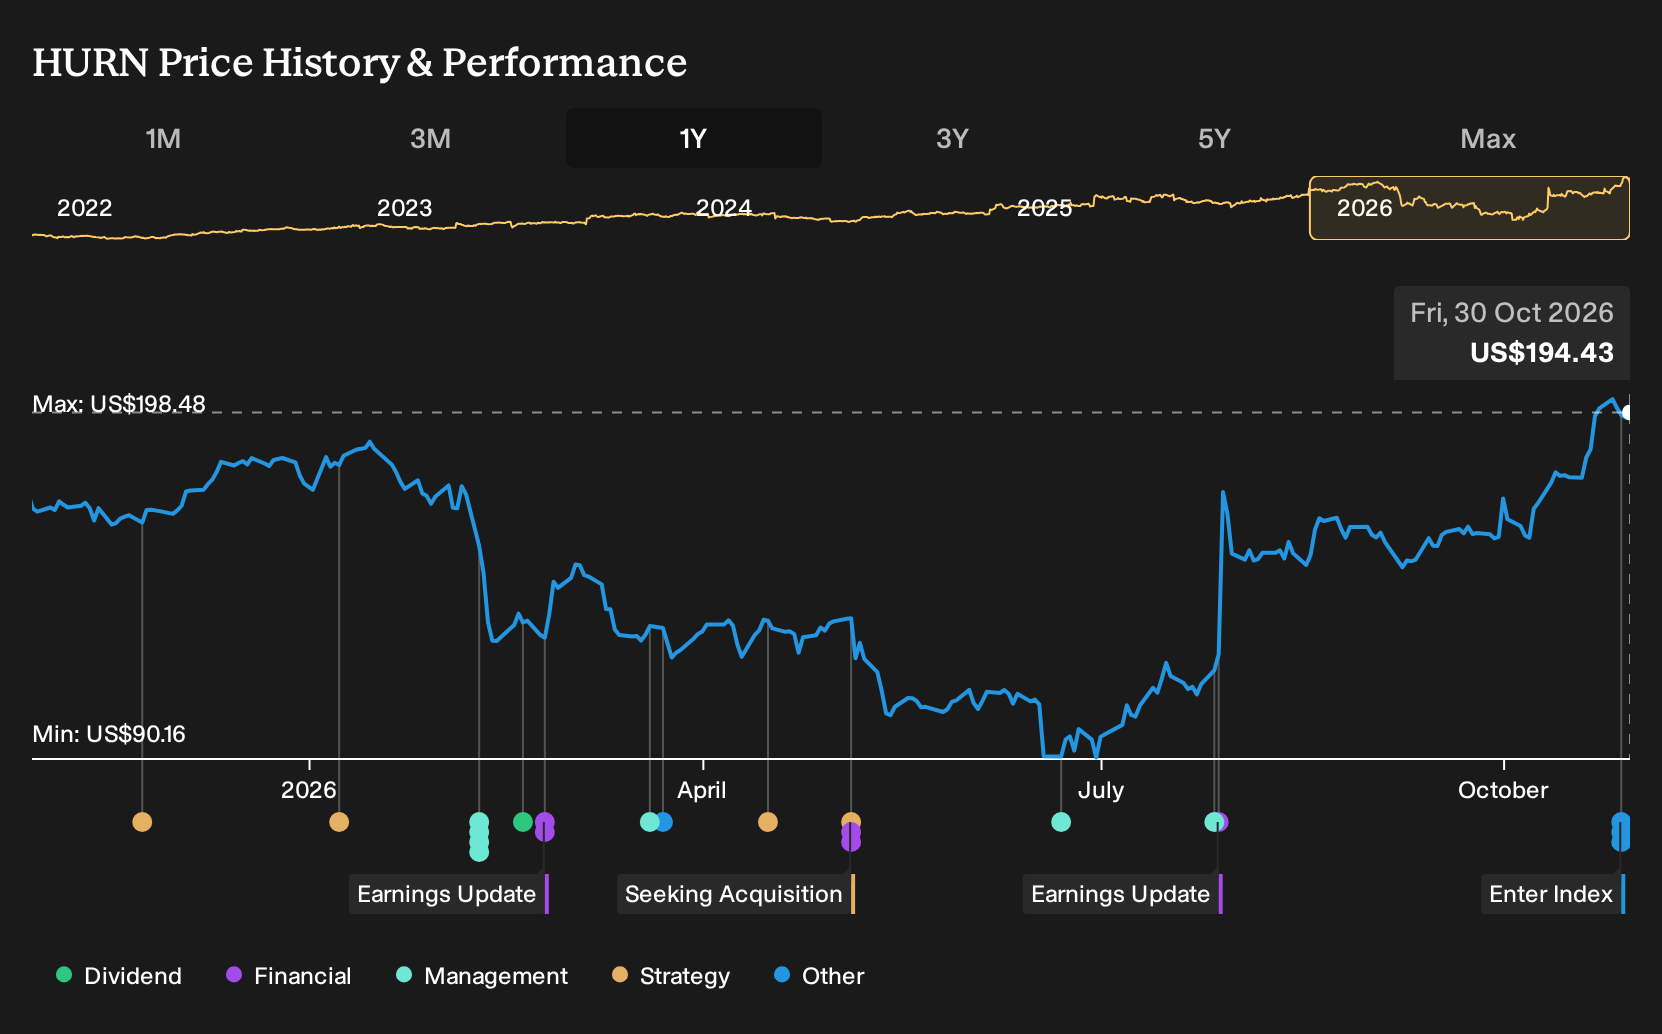
- Huron Consulting Group was added to the S&P 600 Industrials and the broader S&P Composite 1500 on 28 October 2026, bringing the stock into a wider set of index-tracking portfolios.
- This new index inclusion increases visibility for Huron Consulting Group among institutional investors and can influence liquidity and how the business is represented in diversified U.S. equity allocations.
- We will now look at how Huron Consulting Group's investment narrative might be influenced by its recent addition to key S&P indices.
Scan how Huron Consulting Group’s index move compares with other potential additions to diversified portfolios by reviewing the hand-picked list of solid balance sheet and fundamentals (24 results).
Huron Consulting Group Investment Narrative Recap
For Huron Consulting Group, the core belief as a shareholder is that demand from healthcare, education and commercial clients for performance improvement, AI supported services and managed offerings stays healthy enough to support its current mix shift toward recurring and outcomes based work. The most important near term catalyst remains execution on that contract mix and digital bookings, and the index additions themselves do not materially change that operating task.
The biggest current risk stays on the cost and balance sheet side. Rising support personnel expenses, higher software and hosting costs, and a higher level of debt all need careful management so they do not erode margins or flexibility. Index inclusion may increase liquidity, but it does not remove the pressure to keep costs aligned with revenue and to avoid stretching leverage during weaker cash generation.
With no fresh operational announcements tied directly to the index changes, the most relevant recent datapoint remains Huron Consulting Group’s progress in shifting revenue toward outcomes based and recurring contracts, which reached 67% of revenue before reimbursable expenses by 2025. That mix gives more visibility on cash flow and ties directly into how investors might judge the value of its new index exposure.
Digital bookings, which were reported at more than 20% year on year growth in Q2 2026 with an increasing share linked to AI scope, form the other side of the same catalyst. If clients keep prioritising technology and AI supported efficiency projects over deferred digital work, that momentum can support both revenue and margins. Your assessment of Huron’s execution on these two fronts, contract quality and digital demand, is likely to matter more than the index news itself.
How Huron Consulting Group's Index Story Lines Up With Analyst Assumptions
Huron Consulting Group now carries an index label that can pull it into more model portfolios, but the numbers investors often anchor to are still the analyst scenarios behind that ticker. Those forecasts sketch out how much revenue and profit the business might be generating by the time the current crop of S&P index reshuffles feels like old news, and they show what kind of earnings power would need to sit behind the stock for today’s consensus views to make sense.
Huron Consulting Group's latest analyst framework points to rising scale and profitability over the next several years, with forecast revenue growth of 9.6% a year and earnings today of US$115.6 million expected to reach a consensus of US$223.3 million by 2029, which is an increase of about US$108 million in profit. Under those assumptions, revenues are projected to reach about US$2.3b and earnings US$223.3 million in 2029.
Uncover why Huron Consulting Group's fair value indicates a 4% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Index inclusion has some investors focused on liquidity, but the lowest analysts lean hard into AI disruption risk for Huron Consulting Group. They were pencilling in about US$2.4b of revenue and US$223.8 million of earnings by 2029, yet they still argued for a much lower P/E. Use that spread to explore how differently the same data can be read.
Explore 3 other Huron Consulting Group fair value estimates, including one that suggests as much as 51% downside from the current price!
The Verdict Is Yours
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Huron Consulting Group research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Huron Consulting Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Huron Consulting Group's overall financial health at a glance.
Looking For More Ideas Beyond Huron Consulting Group?
Once you have a handle on Huron Consulting Group, it can help to compare it with other opportunities that have different risk and income profiles. The Simply Wall St screener lets you scan the market quickly and then drill into the fundamentals that matter most to you.
- For investors who want income to play a bigger role in returns, start with companies that have higher yields and resilient payout histories by checking out 5 dividend fortresses.
- If balance sheet strength and solid fundamentals are a priority, compare Huron Consulting Group with a broader list of solid balance sheet and fundamentals (24 results) that already meet strict financial health filters.
- When you want to hunt for opportunities that fly under the radar, use the 19 high quality undiscovered gems to focus on lesser known businesses with strong underlying metrics.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com