
Is Shionogi (TSE:4507) Still Cheap Following Strong Results And Higher Dividend Guidance?
Why Shionogi’s latest earnings and dividend move matter for investors
Shionogi (TSE:4507) just paired stronger half year results with higher full year earnings and dividend guidance, putting fresh attention on how its product portfolio and cash generation feed into shareholder returns.
The recent guidance hike and dividend increase come at a time when the share price has gained momentum, with a 30 day share price return of 8.11% and a year to date gain of 5.13%. A 1 year total shareholder return of 19.66% and a 3 year total shareholder return of 37.20% indicate that patient holders have already seen meaningful value from Shionogi.
Scan how Shionogi’s earnings and dividend story compares with other potential opportunities by reviewing our curated list of 14 high quality undervalued stocks that also pair cash generation with shareholder returns.
Bulls point to Shionogi’s upgraded earnings and richer dividend path, while bears flag drug concentration risk and execution demands. Based on today’s numbers, which story does the current valuation appear to support?
Price to earnings of 10.6x for Shionogi: Is it justified?
On current figures, Shionogi trades on a P/E of 10.6x, which looks low compared with both its own fair value estimate and sector peers given the recent share price of ¥3,012.
The P/E ratio compares the market value of the equity to the earnings it generates. For a pharmaceutical group like Shionogi, that link between valuation and profit can matter more than raw revenue growth, because cash generation and patent cycles tend to influence shareholder returns over time.
Here, the market is pricing Shionogi at less than half of the SWS fair P/E of 21.9x. This suggests investors may be assigning a discount to its forecast earnings decline, even though the business has a record of 12.1% annual earnings growth over the past 5 years and 41.5% profit growth over the last twelve months.
Set against the rest of the JP Pharmaceuticals space, Shionogi trades on 10.6x earnings compared with an industry average P/E of 14.9x and a peer group average of 20.3x. That is a notable valuation gap and a level the market might move towards if confidence in its profit durability improves.
Explore the SWS fair ratio for Shionogi.
Result: Price-to-Earnings of 10.6x (UNDERVALUED)
Still, Shionogi’s reliance on prescription drugs and a recent annual net income decline of 1.6% could pressure sentiment if earnings momentum cools.
Find out about the key risks to this Shionogi narrative.
Another view on Shionogi’s value
The P/E points to good value for Shionogi, but the SWS DCF model tells an even stronger story. On that framework, the current price of ¥3,012 sits well below an estimated fair value of ¥7,200.87, which frames today’s discount as unusually wide. Could the gap be reflecting real earnings risk, or is sentiment overshooting the cautious forecasts?
Look into how the SWS DCF model arrives at its fair value.
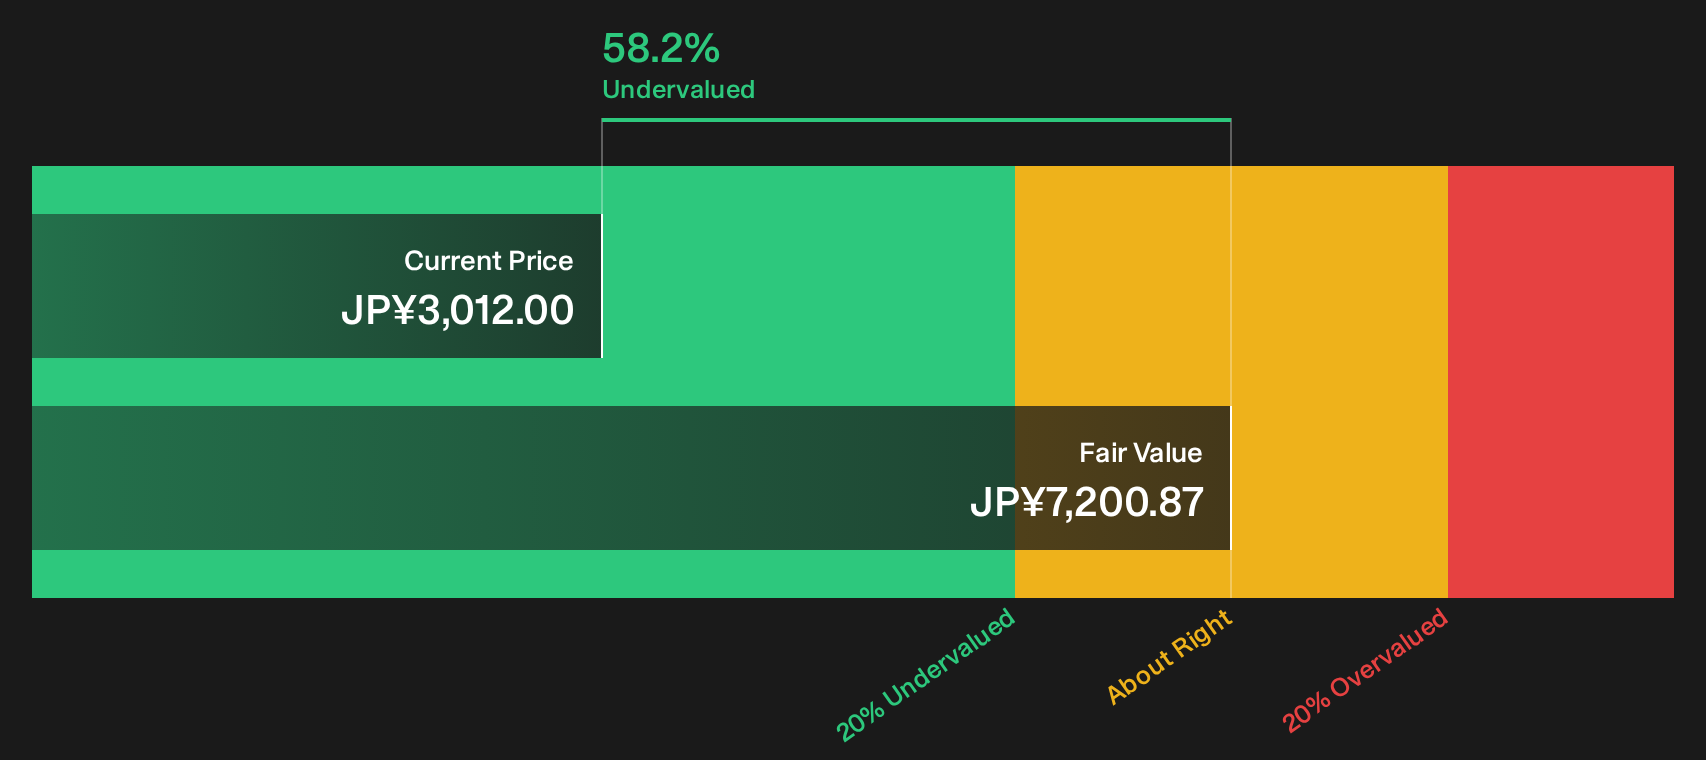
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Shionogi for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 14 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Does the balance of optimism and concern around Shionogi match your own read of the numbers, or does it feel out of sync with the risks and rewards on the table? Take a few minutes to go through the key data points yourself, pressure test the consensus, and then check the 4 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Shionogi?
If Shionogi has sharpened your focus on value and income, do not stop there. Apply the same disciplined lens to a wider opportunity set using focused screeners.
- Target resilient balance sheets by scanning a list of solid balance sheet and fundamentals (22 results) that prioritises financial strength alongside earnings power.
- Hunt for mispriced opportunities through a curated 14 high quality undervalued stocks that blend quality fundamentals with compressed P/E ratios.
- Zero in on underfollowed opportunities by using a 71 high quality undiscovered gems that pair strong financials with limited market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com