
Graham Holdings (GHC) Reports Mixed Quarter, Is The Stock Still Cheap?
Graham Holdings (GHC) just released third quarter 2026 results, reporting revenue of US$1,326.04 million and net income of US$75.11 million, a sharp drop from the prior-year period.
At a share price of US$1,168.51, Graham Holdings has seen short term momentum fade slightly, with the 7-day share price return down 2.4%. However, the year-to-date share price return is up 7.47%, and the 5-year total shareholder return has more than doubled at 105.52%.
Compare Graham Holdings' mixed earnings story with other resilient, cash-generating companies using our hand picked 33 high quality undervalued stocks for ideas that look beyond a single quarter's results.
Graham Holdings now appears to be a solid, diversified enterprise facing fresh questions after a softer quarter. Following the recent share price wobble, the key issue is whether US$1,168 a share still reflects fair value or a stretched one.
Preferred P/E of 9.9x: Is it justified for Graham Holdings?
On a simple earnings yardstick, Graham Holdings looks inexpensive. At a last close of $1,168.51, the stock trades on a P/E of 9.9x, while peers in the US Consumer Services space sit closer to 12.2x and the broader peer set averages 13.3x.
P/E compares what investors are paying today to each dollar of profit the business currently generates. For a diversified group like Graham Holdings, with exposure across education, healthcare, media, manufacturing and automotive, that ratio distils a very complicated profit mix into a single number you can line up next to sector averages.
The gap is not small. A 9.9x P/E against a 13.3x peer average and a 12.2x Consumer Services benchmark suggests the market is pricing Graham Holdings at a clear discount to comparable companies, even though its earnings have grown 19.6% per year over the past 5 years and are assessed as high quality. The lower multiple sits alongside a recent decline in profit margins from 14.8% to 9.6% and a Return on Equity of 10.4%, which is described as low, so the discount may reflect concerns about how sustainable past profit growth is rather than a simple pricing error.
Compared with industry peers, that undercut P/E places Graham Holdings firmly in the cheaper bucket. The stock is described as good value both against Consumer Services as a whole and against a broader peer group. Yet the same data flags revenue that is forecast to grow at 5.5% per year, slower than both the US market and high growth thresholds, and earnings that currently lack clear forecast visibility. For an investor, the question becomes whether that modest multiple is a fair reflection of slower expected expansion and softer recent margins, or whether it underestimates the benefit of a seasoned board and management team, diversified revenue base of $5.1b, and high quality historical earnings.
Result: Price-to-Earnings of 9.9x (UNDERVALUED)
See what the numbers say about this price — find out in our valuation breakdown.
Still, the picture can change quickly if Graham Holdings sees further pressure on profit margins or if earnings quality metrics begin to deteriorate from here.
Find out about the key risks to this Graham Holdings narrative.
Another view of Graham Holdings valuation
The P/E points to Graham Holdings as inexpensive, yet the SWS DCF model paints an even starker picture. On that cash flow view, an estimated value of $3,372.02 per share versus a market price of $1,168.51 suggests a wide gap that investors need to interpret. Is that a genuine opportunity or a signal that the model assumptions deserve closer scrutiny?
Look into how the SWS DCF model arrives at its fair value.
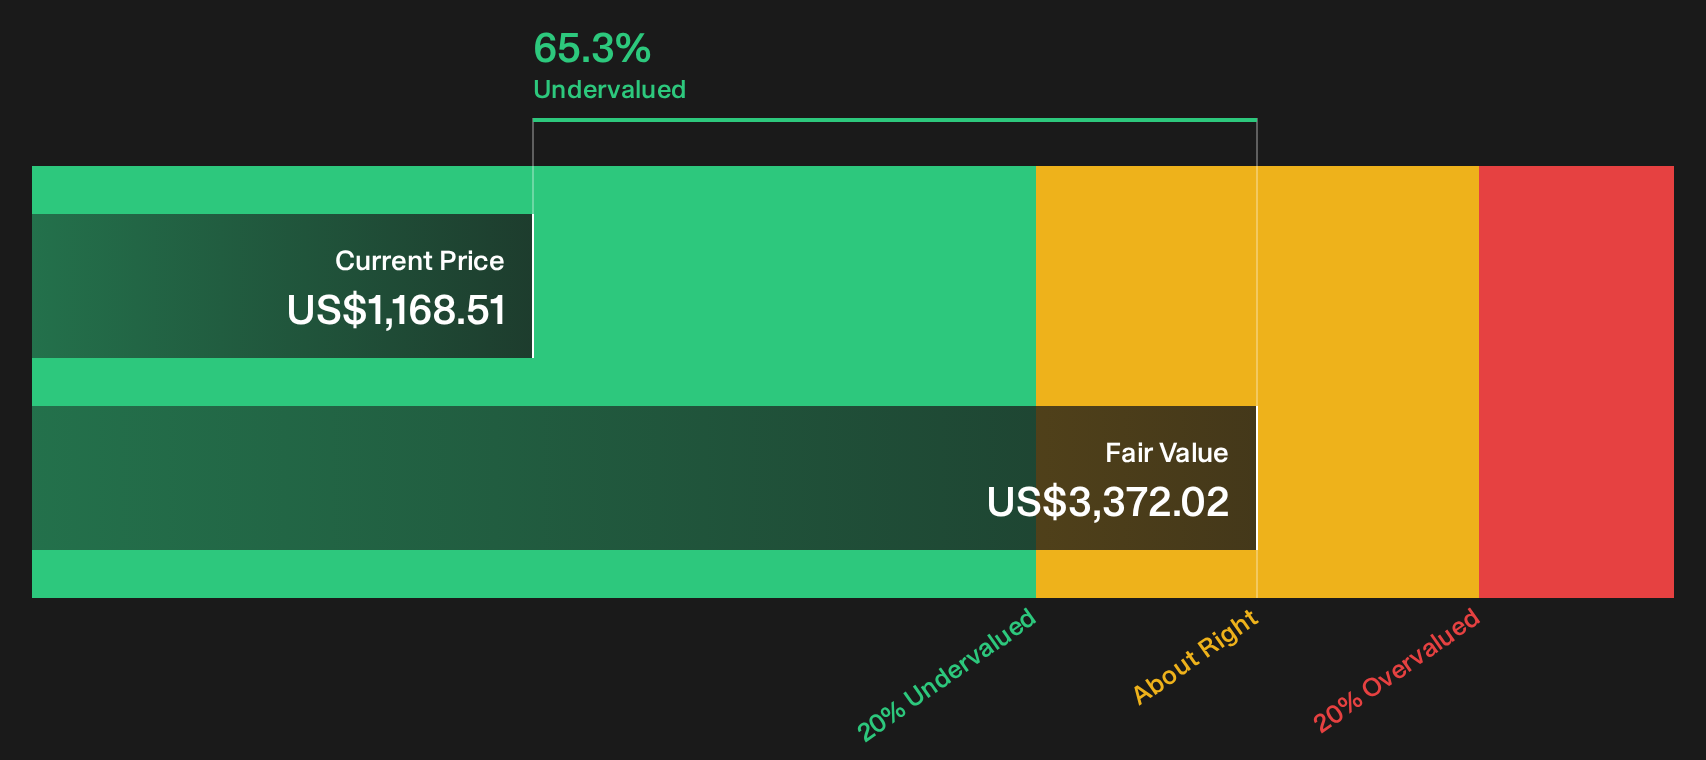
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Graham Holdings for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 33 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If this mix of value signals and questions around Graham Holdings leaves you undecided, keep moving quickly, compare the numbers, and pressure test the narrative for yourself. Then weigh up the balance of potential upside and downside by checking the 1 key reward and 1 important warning sign.
Looking for more Graham Holdings sized investment ideas?
If Graham Holdings has you rethinking what value looks like, do not stop at one ticker. Cast a wider net now so you are not regretting missed opportunities later.
- Target income resilience by scanning companies that aim to support stronger payouts through a 5 dividend fortresses.
- Hunt for quality at a discount by filtering for companies that combine earnings strength with appealing valuations using our 33 high quality undervalued stocks.
- Zero in on durability by reviewing a curated list of solid balance sheet and fundamentals (24 results) that can help you focus on financially robust businesses when conditions change.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com