
ZoomInfo Technologies (GTM) Expands Snowflake And Exa Ties As Undervalued Case Holds
ZoomInfo Technologies (GTM) just rolled out deeper hooks into Snowflake and Exa, wiring its GTM data directly into AI agents and data clouds. For shareholders, the question is how that reach might influence long term usage.
Against that product backdrop, ZoomInfo Technologies has seen the share price rise 31.88% over the past 90 days on a 30 day share price return of 14.83%. Yet the year to date share price return is still down 54.71% and the 1 year total shareholder return has declined 61.21%. Recent momentum is building from a low base as the market reassesses how these integrations might affect future usage and risk.
Scan how ZoomInfo Technologies fits into the wider AI data buildout by comparing it with a hand picked list of 54 AI infrastructure stocks.
After a sharp 90 day rebound yet deep 1 year and multi year losses, ZoomInfo Technologies now sits at a crossroads. Do the current price and fundamentals still skew the risk reward toward buyers, or has the easy upside already passed?
Most Popular Narrative: 56% Undervalued
On the most followed view, ZoomInfo Technologies screens as materially undervalued, with a fair value of $9.99 against a last close of $4.35. This puts the focus squarely on whether its AI fueled workflows and cost cuts can reshape earnings power.
The acquisition of DoubleO.ai and the focus on orchestrating multi agent workflows around proprietary go to market data create room for ZoomInfo Technologies to charge for higher value decisioning and automation rather than only raw data access, which could affect average contract value and operating margins.
See why 9 investors see ZoomInfo Technologies as 56% undervalued.
Result: Fair Value of $9.99 (UNDERVALUED)
Still, the bullish ZoomInfo Technologies story wobbles if net revenue retention, stuck at 89%, keeps dragging on recurring sales or if AI driven alternatives squeeze contract values.
Find out about the key risks to this ZoomInfo Technologies narrative.
Another View: ZoomInfo Technologies On Simple Sales Multiples
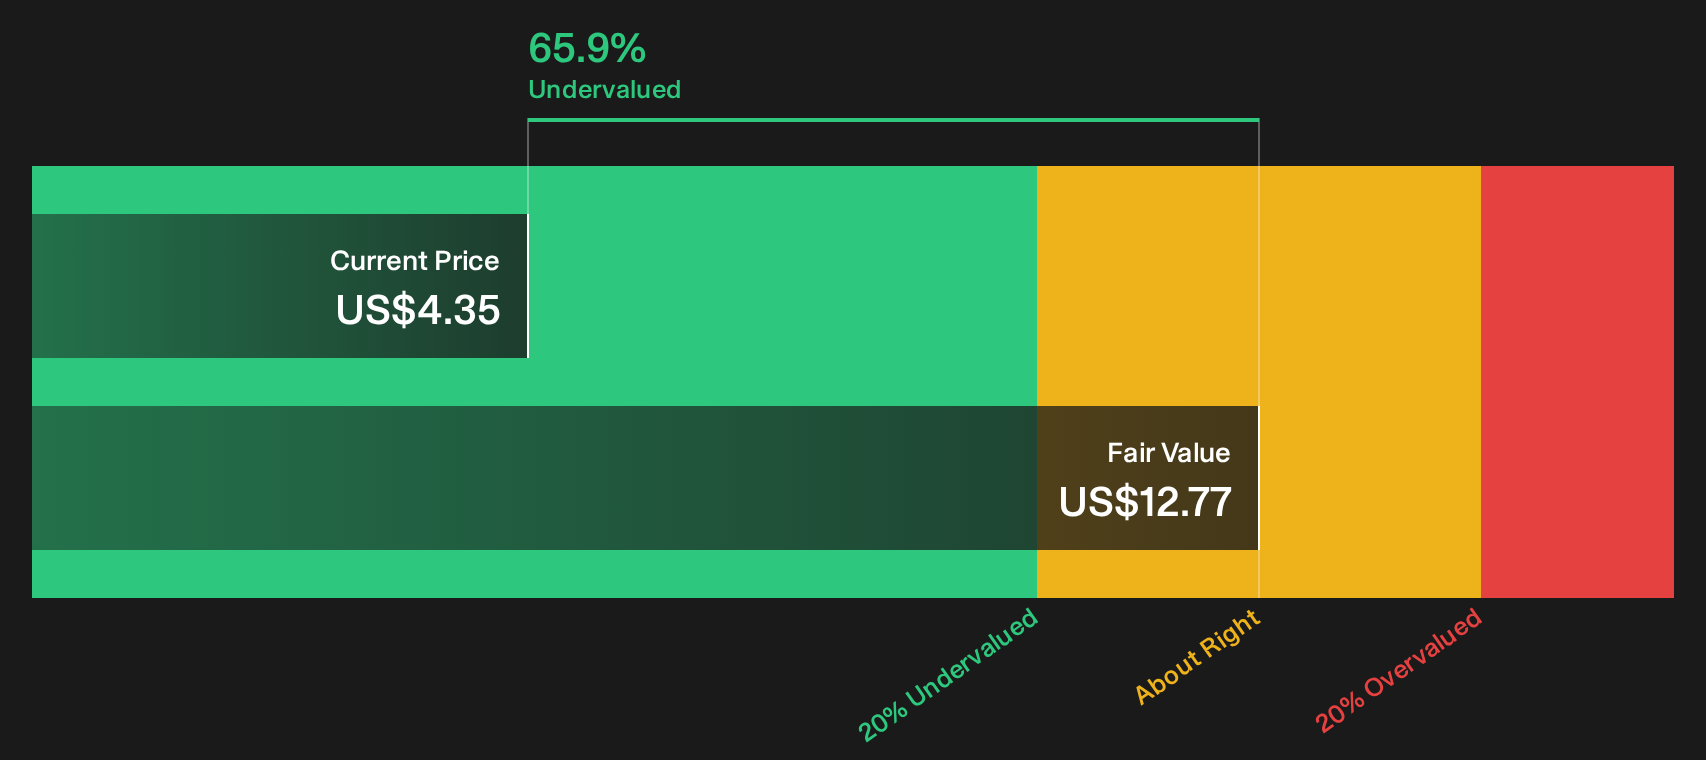
The discounted cash flow workup points to ZoomInfo Technologies trading below an estimated future cash flow value of $12.77, which reads as undervalued. A simpler P/S check sends a different signal. At roughly 1x sales, GTM screens slightly expensive against the US Interactive Media and Services group on 0.9x and a peer set on 0.8x, even though that same 1x level sits a touch below a fair ratio of 1.1x that the market could potentially move toward. For anyone weighing those signals, the real puzzle is which reference point feels more reliable if revenue is expected to decline by 1.8% a year.
To see how that cash flow view is built line by line, take a look at how the SWS DCF model tackles ZoomInfo Technologies through Look into how the SWS DCF model arrives at its fair value..
Next Steps
Mixed signals like these rarely resolve on their own, so it helps to see the underlying data for yourself and decide quickly where you stand. To weigh both sides of the ZoomInfo Technologies story in one place, start with the 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond ZoomInfo Technologies?
If ZoomInfo Technologies has you rethinking where the next edge might come from, casting a wider net across high quality ideas can sharpen your opportunity set fast.
- Target potential future upside by scanning a curated list of high quality undervalued opportunities through the 33 high quality undervalued stocks.
- Protect your downside by focusing on sturdier businesses using the 29 resilient stocks with low risk scores.
- Explore lesser known possibilities with solid fundamentals through the 19 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com