
Piper Sandler Companies (PIPR) Buyback And Q3 Results Put Valuation Back In Focus
Piper Sandler Companies (PIPR) just packed several shareholder headlines into one day, reporting third quarter 2026 results, affirming its dividend, and unveiling a fresh US$200 million buyback authorization.
The upbeat headlines have landed against a tougher tape for Piper Sandler Companies, with the share price down 7.1% on the day of the release to US$63.81 and declining 27.1% year to date. Even though the 3 year total shareholder return is 87.3% and the 5 year total shareholder return is 66.0%, this suggests long term holders have still seen meaningful gains while near term momentum has faded.
Scan beyond Piper Sandler Companies and compare this kind of capital return story with 33 high quality undervalued stocks that combine buybacks, dividends, and balance sheet strength.
Piper Sandler Companies now trades well below its recent levels after a tough year on the screen, even as it commits fresh cash to buybacks and dividends. Is most of the value already recognized, or is the reset creating room for more?
Most Popular Narrative: 20% Undervalued
At a last close of $63.81 against a widely followed fair value estimate of $79.38, Piper Sandler Companies is framed as meaningfully discounted in the prevailing narrative, with that gap resting on a detailed set of revenue and margin assumptions.
Growth in private credit and sponsor activity is expanding the opportunity set for debt capital markets advisory, private capital advisory and restructuring work. This can affect advisory revenues and support operating leverage as more of the fee pool shifts to these higher value services.
See why 1 investors see Piper Sandler Companies as 20% undervalued.
Result: Fair Value of $79.38 (UNDERVALUED)
Still, the Piper Sandler Companies story can change quickly if advisory volumes stay soft or if any future large acquisition brings tougher integration and retention issues.
Find out about the key risks to this Piper Sandler Companies narrative.
Another View: Cash Flows Paint A Harsher Picture
On one hand, Piper Sandler Companies is framed as about 20% below a US$79.38 fair value built on analyst earnings assumptions. On the other hand, the Simply Wall St DCF model points to future cash flow value of just US$34.58 per share, well below the current US$63.81 price and flagging the stock as overvalued from that perspective.
This gap between earnings based and cash flow based views highlights real valuation risk. It leaves you asking which set of assumptions feels closer to how Piper Sandler actually converts advisory fees into long run cash.
For a closer look at how this cash flow view is built, start with the SWS DCF model itself, then decide which story you find more persuasive. Look into how the SWS DCF model arrives at its fair value.
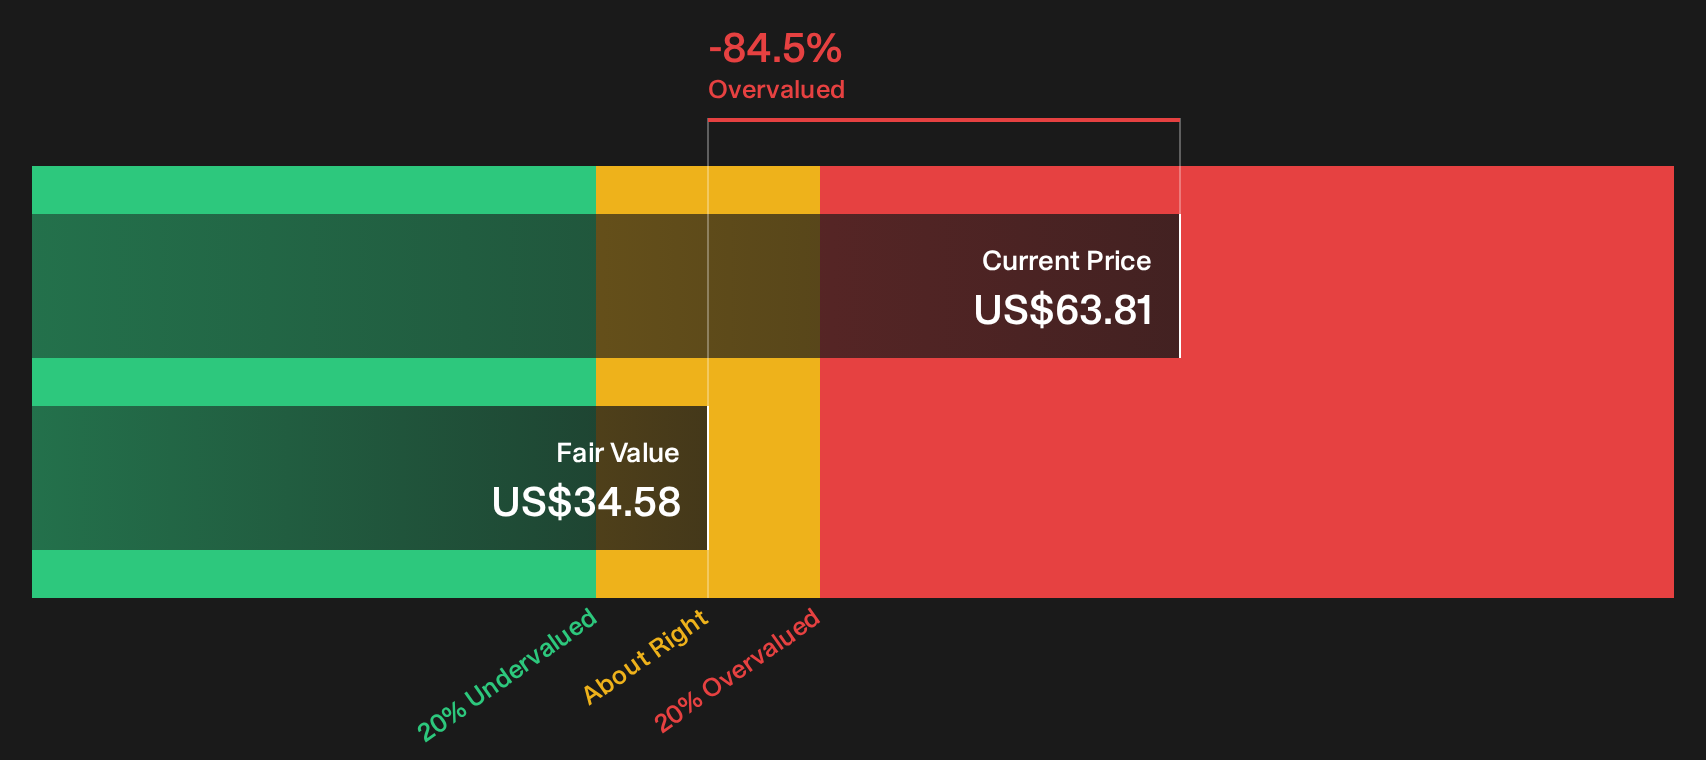
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Piper Sandler Companies for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 33 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If this mix of optimism and caution around Piper Sandler Companies feels familiar, consider taking a closer look and pressure test the story against the data yourself. To weigh both sides clearly, start with 4 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Piper Sandler Companies?
Do not stop with Piper Sandler Companies. Use the Simply Wall St screener to hunt for fresh candidates where the numbers and story line up before others catch on.
- Target resilient opportunities by focusing on businesses that hold up under pressure with a 29 resilient stocks with low risk scores that filters for stability and lower risk scores.
- Hunt for future leaders early through a 19 high quality undiscovered gems built to surface quality companies that many investors still overlook.
- Anchor your watchlist in financial strength with a list of solid balance sheet and fundamentals (24 results) that highlights firms combining cleaner balance sheets with solid fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com