
IRADIMED (IRMD) Earnings And Guidance Raise The Question Of Whether The Stock Is A Bargain
What IRADIMED's Latest Earnings Mean For Investors
IRADIMED (IRMD) just paired a fresh third quarter earnings release with new fourth quarter and full year 2026 guidance, giving investors updated revenue and earnings per share ranges to work with.
Alongside that outlook, the business confirmed a regular cash dividend of $0.20 per share, with payment scheduled for November 27, 2026 to stockholders of record as of November 13. Those decisions come as the healthcare equipment specialist continues to generate cash from MRI compatible infusion and monitoring products, while the share price has pulled back over the past month and past 3 months.
IRADIMED's stock has retreated sharply in the short term, with the share price down 10.6% over the past week and 16.3% over 90 days. However, the 1 year total shareholder return of 1.2% and 5 year total shareholder return of 121.7% show a longer track record of value creation, even as investors reassess the guidance, dividend and latest earnings print against what they are willing to pay at the current US$76.68 level.
Scan IRADIMED's pullback in context by comparing it with a hand picked group of healthcare equipment peers that have resilient balance sheets and strong cash generation, available through our list of solid balance sheet and fundamentals (24 results)
IRADIMED's share price just fell while reported sales, earnings and guidance moved in a different direction, which raises a simple question. Is this about the business, or about sentiment resetting the valuation you are paying?
Most Popular Narrative: 35% Undervalued
IRADIMED's most followed valuation story puts fair value at $118 per share, above the last close of $76.68. This frames the recent pullback very differently for investors weighing earnings, guidance and the dividend.
A large multi year replacement opportunity in the roughly 6,400 older pump channels, combined with management’s target of more than 2,000 3870 channels sold annually, points to sustained system demand. This could underpin IRADIMED pump revenue levels and support operating income over several years.
See why 8 investors see IRADIMED as 35% undervalued.
Result: Fair Value of $118 (UNDERVALUED)
Still, IRADIMED’s heavy reliance on MRI compatible pumps and the early hit to gross margin from 3870 manufacturing inefficiencies both sit uncomfortably underneath this upbeat valuation story.
Find out about the key risks to this IRADIMED narrative.
Another View: What IRADIMED's P/E Is Telling You
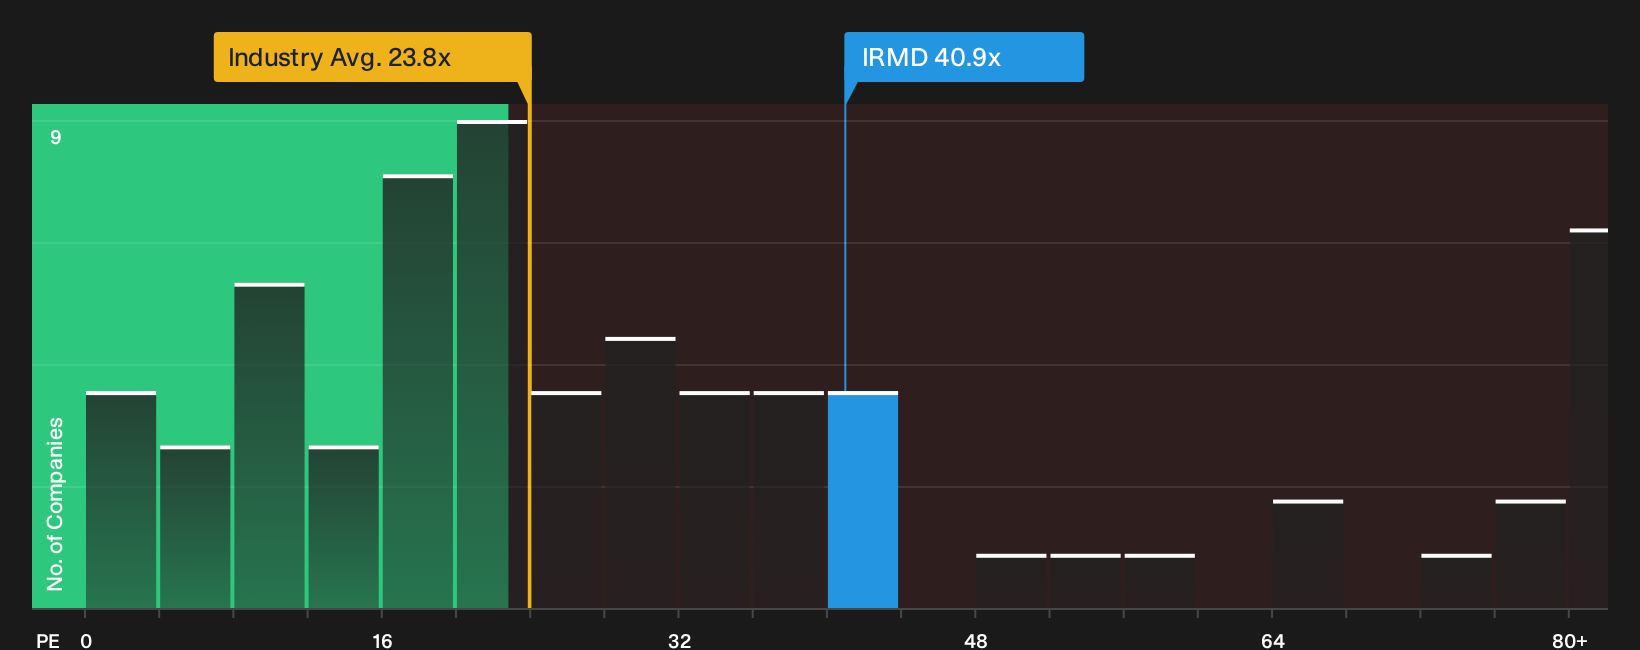
IRADIMED might look undervalued against a $118 fair value, yet its P/E of 40.9x is higher than both the US Medical Equipment industry at 23.8x and peer average at 39.4x, and it also sits above a fair ratio of 21.3x. That gap points to valuation risk if expectations soften. How comfortable are you paying this kind of premium for the story you have in mind?
To pressure test that premium against the underlying numbers, take a closer look at how the valuation stacks up through our detailed breakdown, starting with the See what the numbers say about this price — find out in our valuation breakdown.
Then review how IRADIMED's current P/E compares visually against sector benchmarks using the latest ratio snapshot here
Next Steps
If the story so far seems either too cautious or too optimistic for IRADIMED, evaluate it yourself while sentiment is still shifting. Start by checking the balance of potential upside with the 3 key rewards.
Looking for more IRADIMED sized investment ideas?
If IRADIMED has you rethinking what you own, this is the moment to widen your opportunity set before the next round of prices moves without you.
- Target potential upside in quality companies trading below what their fundamentals might justify by scanning our 33 high quality undervalued stocks.
- Strengthen your income stream by zeroing in on established payers with higher yields using the 5 dividend fortresses.
- Protect your downside by focusing on financially robust businesses through the 29 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com