
United States Lime & Minerals (USLM) Q3 Strength Meets Cost Concerns On A Pricey Valuation
Why United States Lime & Minerals is back on investors’ radar
United States Lime & Minerals (USLM) just paired a regular quarterly dividend declaration with fresh third quarter numbers, putting both income potential and cost pressures in front of investors at the same time.
Recent trading tells a mixed story. The share price is around $111.61 and is down about 7.7% year to date, even though the 5 year total shareholder return is about 314%. Long term holders in United States Lime & Minerals have still seen very strong compounding despite the more cautious tone around rising costs this year.
Scan beyond United States Lime & Minerals and compare it with a curated group of industrials that pair solid fundamentals with income potential through our 5 dividend fortresses
United States Lime & Minerals recently combined record multi-year returns with a share price that has cooled and a dividend that remains modest. Is most of the value already reflected, or does the recent pullback still leave upside on the table?
Price-to-earnings of 23.9x: Is it justified for United States Lime & Minerals?
United States Lime & Minerals trades on a P/E of 23.9x, which looks rich when you line it up against both global basic materials rivals on 14.1x and closer peers on 22.3x.
The P/E ratio compares the current share price to earnings per share and gives a quick read on how much investors are willing to pay for each dollar of profit. For a lime and limestone producer like United States Lime & Minerals, this often reflects how dependable its earnings stream is, how investors view its position in industrial and construction supply chains, and how confident the market feels about future profitability.
Earnings growth of 2.3% over the past year, combined with high quality earnings and a net profit margin of 35.1%, helps explain why investors might accept a premium. At the same time, the fact that this growth is well below the 28.6% per year achieved over the past 5 years suggests the market could be paying up for a business where profit momentum has cooled compared to its own recent history.
Compared with the global basic materials industry average P/E of 14.1x, the 23.9x multiple for United States Lime & Minerals points to investors assigning a materially higher valuation than the sector. Relative to the peer average of 22.3x, the stock still trades at a premium, which indicates the market is pricing in stronger durability or quality of earnings than both its global industry and more direct peers.
See what the numbers say about this price — find out in our valuation breakdown.
Result: Price-to-earnings of 23.9x (OVERVALUED)
Still, the dividend yield remains modest, and any reversal in the recent 12.6% revenue growth or higher input and energy costs could quickly challenge the current P/E premium.
Find out about the key risks to this United States Lime & Minerals narrative.
Another view on United States Lime & Minerals valuation
The P/E premium tells only one story. Our DCF model values United States Lime & Minerals at $105.44 per share, which is below the current $111.61 price and indicates that the stock may be trading at an overvalued level on a cash flow basis. Which signal would you trust if you had to pick one?
Look into how the SWS DCF model arrives at its fair value.
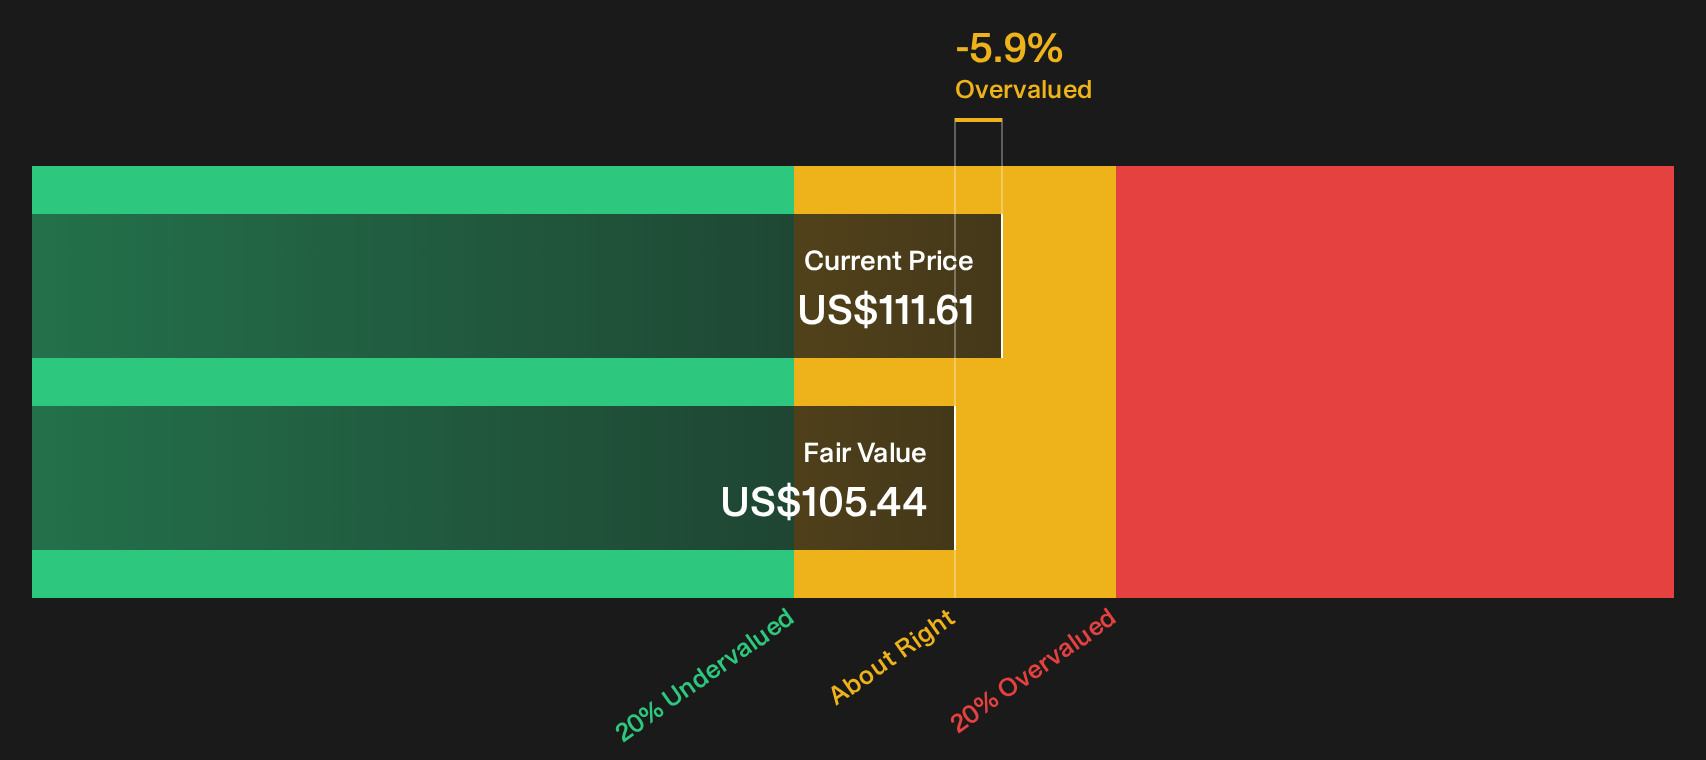
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out United States Lime & Minerals for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 33 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on valuation and fundamentals can spark debate quickly, so check the underlying figures for United States Lime & Minerals yourself and weigh both sides of the story. To see how the trade off between potential rewards and the key issues investors are watching lines up for you, start with this breakdown of 1 key reward and 1 important warning sign
Looking for more investment ideas beyond United States Lime & Minerals?
If United States Lime & Minerals has sharpened your focus on quality and pricing power, use that momentum and widen your watchlist with targeted screeners today.
- Target potential mispricings by scanning companies that pair quality fundamentals with lower valuations through our 33 high quality undervalued stocks.
- Prioritize resilience by reviewing a list of solid balance sheet and fundamentals (24 results) that can help you focus on financially stable businesses when conditions get tougher.
- Spot opportunities the market may be overlooking by filtering for 19 high quality undiscovered gems that still have strong fundamentals backing their case.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com