
United Rentals (URI) On Raised Outlook And New Buyback Looks Undervalued
Earnings, guidance and capital returns in focus
United Rentals (URI) just delivered a packed October update, combining third quarter results, higher full year revenue targets, fresh buyback activity and a continued dividend that together sharpen the picture for shareholders.
Recent news has landed on a stock that already has momentum behind it, with United Rentals delivering a 30 day share price return of 8.23% and a year to date move of 38.46%. The 1 year total shareholder return of 37.58% and 5 year total shareholder return of 209.43% frame the latest earnings beat, raised 2026 revenue guidance, affirmed dividend and fresh shelf registration as part of a longer run story, where positive operational news has often coincided with investors reassessing both growth potential and risk around the current US$1,170.05 share price.
Scan United Rentals alongside a curated shortlist of capital intensive businesses returning cash to shareholders with the 33 high quality undervalued stocks.
United Rentals now trades at a modest discount to both intrinsic estimates and analyst targets after a strong run. Is that a margin of safety, or a warning that the market sees risks you might be glossing over?
Most Popular Narrative: 8% Undervalued
On Simply Wall St, the most followed narrative currently tags United Rentals with a fair value of $1,269.33 compared with the recent $1,170.05 close. This frames the latest earnings, buyback activity and raised 2026 revenue guidance as part of a bigger capital deployment story.
The main thing that has to go right is that United Rentals continues to convert its large project pipeline and specialty expansion into attractive returns on the sizeable rental CapEx and M&A capacity it is committing.
The current valuation implies the share price does not fully reflect the combination of double digit rental revenue growth, historically high time utilization, and a balance sheet that management positions for both growth and ongoing capital returns. This narrative views the shares as undervalued and maintains a positive stance on the stock.
See why 15 investors see United Rentals as 8% undervalued.
Result: Fair Value of $1,269.33 (UNDERVALUED)
Still, the narrative can break if large project activity slows while local demand stays muted, or if high CapEx and mix shifts continue to squeeze margins and cash.
Find out about the key risks to this United Rentals narrative.
Another View: United Rentals Through The P/E Lens
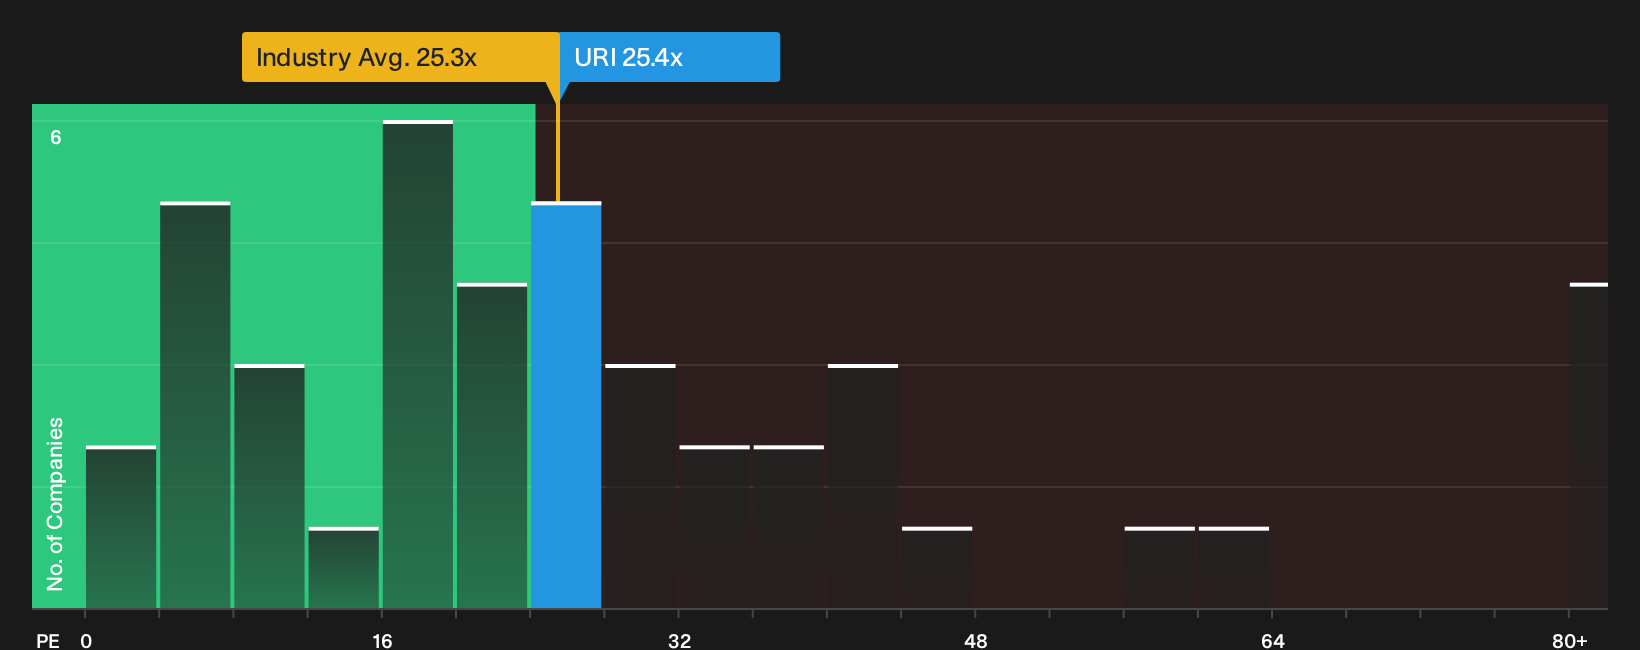
There is a different message coming from the simple P/E check. United Rentals trades at 25.4x earnings, almost identical to the 25.3x average for the US Trade Distributors industry, yet below a 31x peer average and a fair ratio of 30.8x. That combination points to less obvious upside, but also less room for error if sentiment cools.
For a closer look at how this earnings multiple stacks up against sector peers and the fair ratio the market could move towards, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If this mix of optimism and caution around United Rentals resonates, move fast. Study the data yourself, and then decide where you stand. To see both sides of the story in one place, start with the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond United Rentals?
If United Rentals has your attention, do not stop here. Use the Simply Wall St Screener to quickly surface other opportunities that match your investing style.
- Target reliable income and focus your watchlist around companies with robust payouts through the 5 dividend fortresses.
- Hunt for financially resilient operators by scanning the list of solid balance sheet and fundamentals (24 results) before capital markets reprice their strength.
- Get ahead of the crowd by tracking the 19 high quality undiscovered gems that other investors may not be watching yet.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com