
Exelixis (EXEL) Earnings Beat Puts Valuation Back In Focus
Exelixis (EXEL) moved after third quarter results topped market expectations for revenue and net income, while management reaffirmed full year sales guidance and highlighted progress on late stage oncology pipeline programs.
That earnings beat landed on a stock that already had strong momentum. Exelixis shares have logged a 1 month share price return of 18.84% and a year to date share price return of 59.22%, while the 1 year total shareholder return of 82.32% shows how much recent gains build on earlier price moves and dividends.
Capitalize on the momentum around Exelixis by scanning a curated set of oncology and biotech peers with resilient fundamentals using the list of solid balance sheet and fundamentals (24 results).Exelixis now trades well above the average analyst price target, yet screens at a large discount to some fair value estimates. Are investors being too cautious about execution and pipeline risk, or not cautious enough?
Most Popular Narrative: 20.4% Overvalued
Exelixis closed at $69.39 compared with a narrative fair value of $57.64, so the stock is priced well ahead of that framework even after the recent rally.
The main execution priority is turning CABOMETYX’s current multi billion dollar run rate and the planned zanzalintinib launches in GI and GU oncology into durable, multi franchise cash generation before the cabozantinib patent cliff early in the next decade.
The current view that Exelixis is fairly valued and bullish implies the share price already reflects a strong CABOMETYX cash engine, successful zanzalintinib approvals across key indications, and disciplined R&D and buyback-driven capital returns, without assigning much premium for additional potential beyond these elements.
See why 76 investors see Exelixis as 20% overvalued.
Result: Fair Value of $57.64 (OVERVALUED)
Still, concentrated reliance on cabozantinib and the ongoing securities investigations around prior guidance leave Exelixis exposed if future launches or disclosures disappoint.
Find out about the key risks to this Exelixis narrative.
Another View: What Exelixis’s P/E Is Really Pricing In
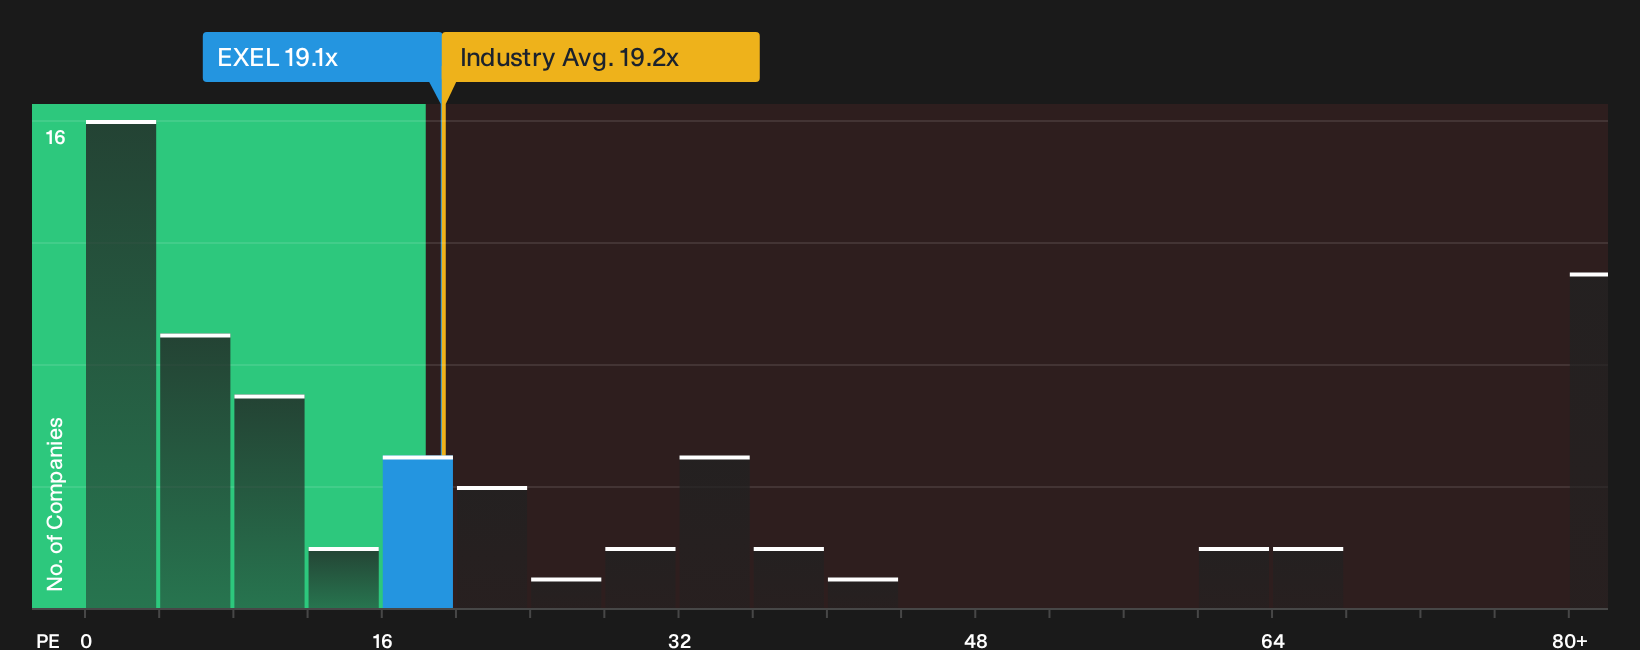
The earlier narrative fair value suggested Exelixis looks 20.4% overvalued at $69.39. A different lens tells a more forgiving story. On a 19.1x P/E, the stock trades in line with the US Biotechs industry at 19.2x, yet well below peers at 57.9x and under a fair ratio of 24.2x.
That combination of sector-level pricing, a sizeable gap to the peer average, and space up to the fair ratio highlights a valuation spread that could either narrow over time or remain wide if risks around patents, growth and management continue to influence sentiment. Which outcome do you think is more realistic for Exelixis?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Feeling unsure whether the recent enthusiasm around Exelixis is overdone or still justified? Put the numbers in context for yourself and see how the potential upside and execution risks balance out by reviewing the 4 key rewards.
Looking for more investment ideas beyond Exelixis?
If Exelixis has sharpened your focus, do not stop there. Broadening your watchlist with other well filtered opportunities can help you spot patterns and manage risk.
- Target potential mispricings early by reviewing the 19 high quality undiscovered gems that pair strong fundamentals with limited market attention.
- Prioritise resilience in tougher markets by scanning a 29 resilient stocks with low risk scores that filters for stronger balance sheets and more stable financial profiles.
- Build a shortlist of value focused candidates by checking the 33 high quality undervalued stocks that combine quality metrics with more modest pricing.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com