
Scholar Rock Holding (SRRK) Faces A Pullback, Is The Stock Still Cheap?
Scholar Rock Holding stock snapshot and recent performance
Scholar Rock Holding (SRRK) has drawn fresh attention after a recent move in its share price. The stock closed at $43.85 on 29 October 2026, with a market value near $5.4b.
Over the past month the share price declined about 9%, while the past 3 months show a fall of roughly 7%. Even with that pullback, the 1-year total return is about 48%.
Year to date, the stock is up around 2%. Over the past 3 years the total return is a little above 2.5x, and the 5-year figure is roughly 54%.
Scholar Rock Holding’s share price has pulled back over the past month, with a 30 day share price return of about 9% down, yet the 1 year total shareholder return of roughly 48% still points to substantial gains for longer term holders.
The recent slide from shorter term share price metrics hints at investors reassessing risk around its neuromuscular and oncology pipeline, while the much stronger multi year total shareholder returns suggest earlier optimism on the company’s drug development prospects remains a key part of the story.
Scan beyond Scholar Rock Holding and see how it compares with 34 healthcare AI stocks targeting complex diseases with advanced biology and data driven approaches.
Scholar Rock Holding has given short term traders a bumpier ride even as longer term holders still sit on strong gains. Are these swings tracking real shifts in the drug pipeline story, or mostly changing sentiment around the ticker as valuation stretches are tested next?
Most Popular Narrative: 38% Undervalued
Scholar Rock Holding’s most followed valuation story pegs fair value at about $70.44 per share, compared with the recent $43.85 close. This places significant emphasis on how the SMA and neuromuscular pipeline converts into future cash flows.
Regulatory progress around apitegromab, including preparation for BLA resubmission in the U.S. and an ongoing MAA review in Europe, could support a transition from a development stage profile to a revenue generating commercial business, with direct implications for future revenue and earnings.
See why 2 investors see Scholar Rock Holding as 38% undervalued.
Result: Fair Value of $70.44 (UNDERVALUED)
Still, the bullish Scholar Rock Holding story hinges on smooth FDA reinspection outcomes and on apitegromab launch spending not outpacing early ISEMBYLD uptake.
Find out about the key risks to this Scholar Rock Holding narrative.
Another view of Scholar Rock Holding’s valuation
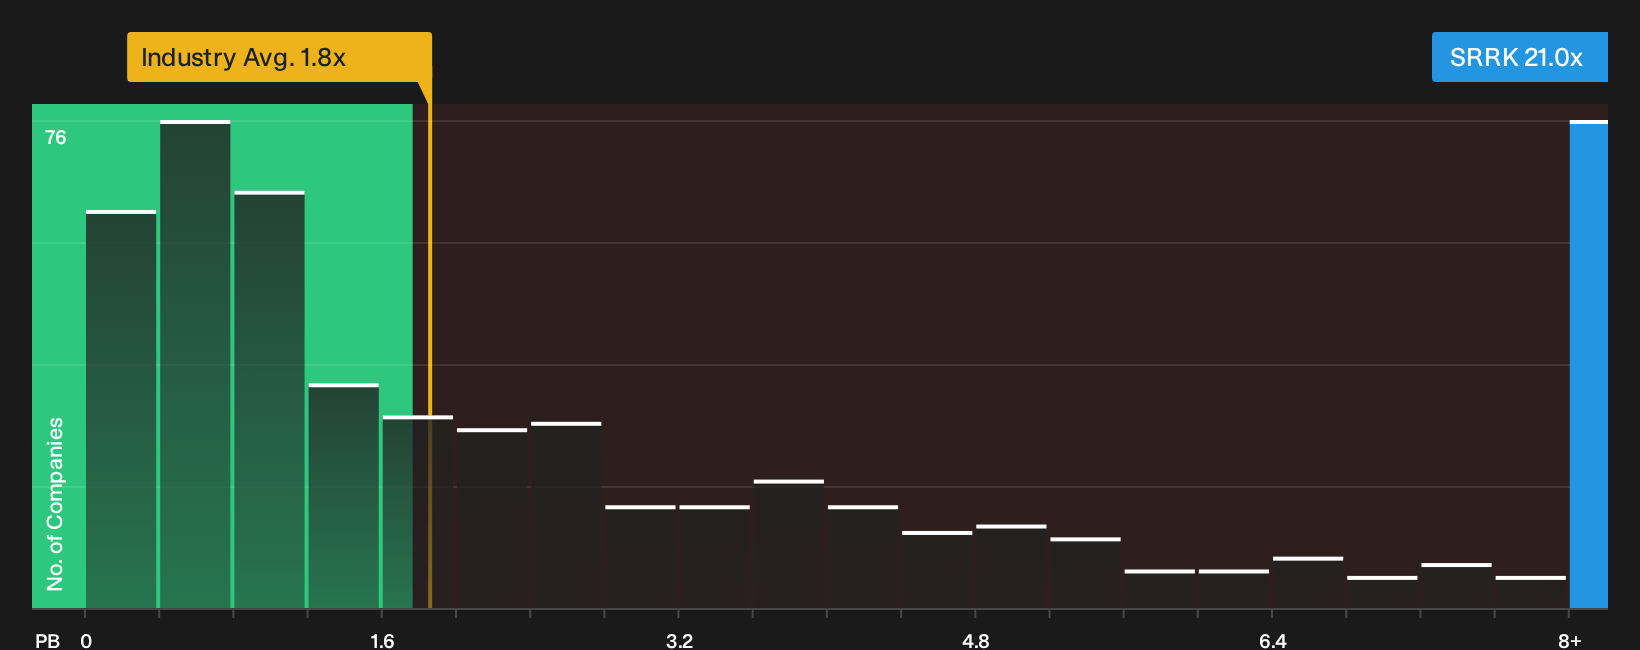
The story shifts when you look at Scholar Rock Holding through its P/B ratio. The stock trades around 21x book value compared with roughly 2x for the wider US Biotechs group and about 54x for its closer peer set. That gap points to both premium expectations and real downside risk if sentiment cools.
Instead of focusing only on headline discounts to fair value, it helps to ask whether a 21x P/B multiple can hold up if clinical execution, launch uptake or funding costs underwhelm from here.
For a closer look at how this price compares with peers and what the market could move toward as a fair ratio, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around Scholar Rock Holding is mixed, with optimism on potential rewards balanced by concern over key risks. Move quickly to review the underlying data, stress test the assumptions that matter most to you, and weigh up the 3 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Scholar Rock Holding?
Do not stop with a single biotech thesis. Use the Simply Wall Street Screener to pressure test your thinking across different sectors, styles and risk levels before you commit.
- Target potential mispricing by scanning 33 high quality undervalued stocks where quality fundamentals and lower implied expectations often sit side by side.
- Strengthen capital preservation by reviewing 29 resilient stocks with low risk scores that pair more resilient balance sheets with gentler volatility profiles.
- Hunt for fresher opportunities by combing through 19 high quality undiscovered gems that attract less attention but still show solid underlying numbers.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com