
Carter's (CRI) Faces A 17% Fair Value Gap As Soft Guidance Tempers Earnings Beat
Earnings beat meets softer outlook
Carter's (CRI) just delivered third quarter results that combined higher profitability with essentially flat sales, then paired that update with more cautious revenue guidance and a refresh of its senior leadership structure.
For the quarter ended October 3, 2026, Carter's reported sales of US$752.46 million compared with US$757.84 million in the same period a year earlier, while net income reached US$36.61 million versus US$11.59 million previously.
Basic and diluted earnings per share from continuing operations came in at US$1, up from US$0.32 a year ago. This sets a very different earnings picture for the period even though revenue stayed close to last year's level.
Across the first nine months of fiscal 2026, the children’s apparel specialist posted sales of US$2,049.06 million compared with US$1,972.98 million a year earlier, with net income of US$155.91 million versus US$27.58 million for the comparable stretch.
Earnings per share from continuing operations over those nine months were reported at US$4.27 on both a basic and diluted basis, compared with US$0.75 a year ago. This gives investors a clearer sense of how profit trends and top line performance have differed so far this year.
Carter's shares fell 5.5% on the day of the update and are down 20.8% over the past 90 days on a share price basis. The flatter revenue outlook and softer guidance appear to have weighed more heavily than the profit rebound and leadership refresh, while the 1 year total shareholder return of 7% contrasts sharply with a 3 year total shareholder return decline of 47.5% and a 5 year total shareholder return decline of 63.7%. This hints that longer term confidence has been much slower to recover than the recent quarter’s earnings headline might suggest.
Scan how Carter's stacks up against other potential rebound stories by reviewing our hand picked 33 high quality undervalued stocks with solid cash flows and balance sheets.
The recent slide in Carter's share price sits between two stories: stronger profits and softer guidance. To judge which one you are really pricing, the next step is to look at valuation.
Most Popular Narrative: 17% Undervalued
Carter's most followed valuation view pegs fair value at $38 per share versus the last close at $31.54. The story centers on whether the current discount reflects real business pressure or an overly cautious market.
Expanding consumer centric branding at Carter's, including higher marketing spend in 2026, collaborations such as Disney and Umbro, and campaigns like Watch Them Glow and Dadfirmations aimed at Gen Z and higher income parents, is expected to support higher average unit retail and potentially more resilient revenue growth.
See why 6 investors see Carter's as 17% undervalued.
Result: Fair Value of $38 (UNDERVALUED)
Still, Carter's story could change quickly if higher tariff costs squeeze margins more than analysts expect, or if cautious wholesale partners cut orders further.
Find out about the key risks to this Carter's narrative.
Another View on Carter's Valuation
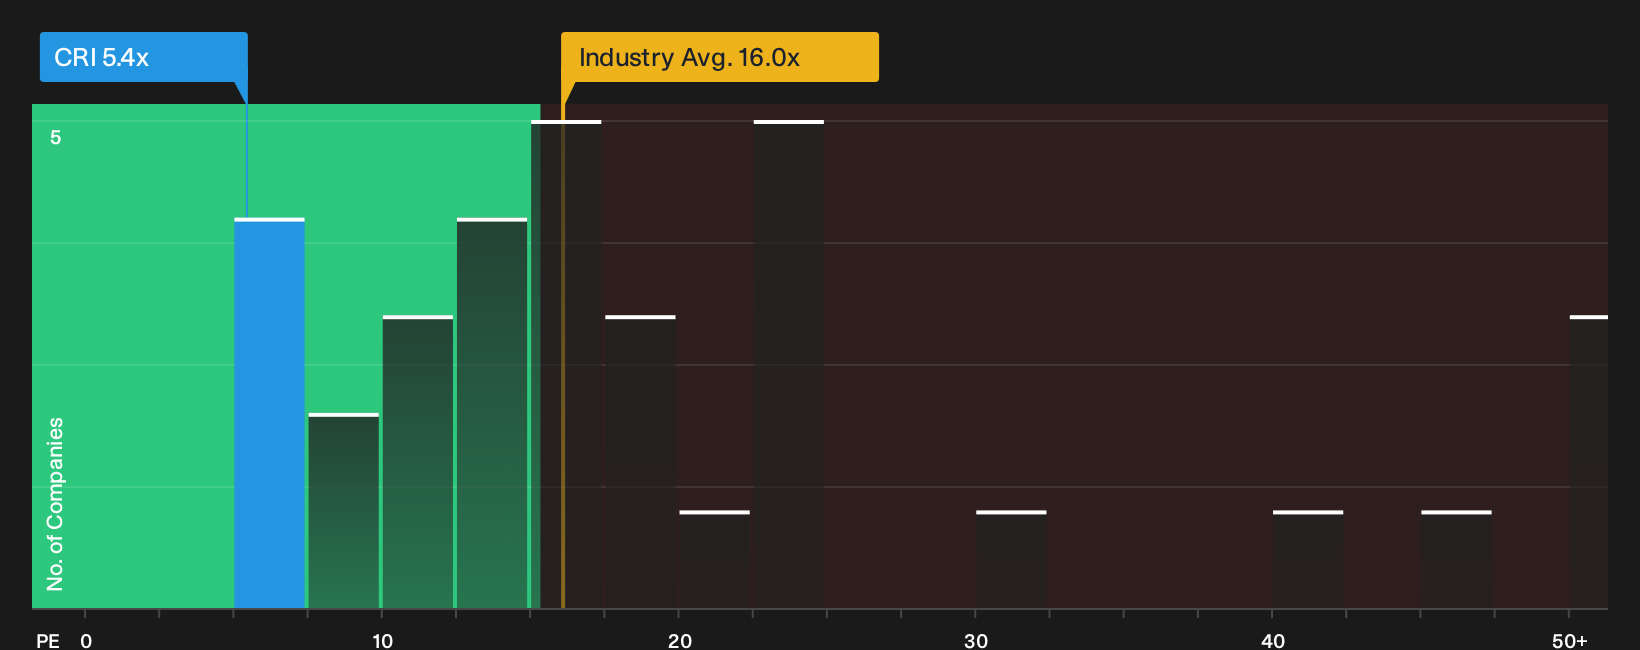
The first story around Carter's focuses on a fair value of $38 per share based on analyst forecasts. A different lens uses the current P/E of 5.4x versus the US Luxury industry at 16.5x and a peer average of 13.4x, while the fair ratio is also 5.4x.
That gap against industry and peers signals that investors are pricing Carter's much more cautiously than similar businesses, even though the fair ratio points to the present multiple already matching what the regression work suggests the market could move toward. The question is whether you view that wide spread as valuation risk or a potential opportunity.
To see how this pricing gap plays out in real numbers and context, take a look at the valuation breakdown in the See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on Carter's future can spark doubt, but momentum often moves before consensus. Weigh the risks and the upside yourself, starting with 2 key rewards and 3 important warning signs
Looking for more investment ideas beyond Carter's?
If Carter's has you rethinking value, do not stop here. Broader opportunities often sit just outside the headlines, and missing them can be costly over time.
- Target potential bargains with solid fundamentals by reviewing our hand picked 33 high quality undervalued stocks that pair quality businesses with compressed valuations.
- Prioritize resilience and sleep better at night by filtering for a 29 resilient stocks with low risk scores that screens for sturdier balance sheets and lower overall risk scores.
- Hunt for underfollowed opportunities by scanning a 19 high quality undiscovered gems that highlights companies with strong metrics but limited market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com