
3 UK Dividend Stocks With Strong Balance Sheets For Higher Rates
UK interest rates are edging higher again, inflation is running hotter than expected and dividend payers are being tested in real time. For income investors, that mix creates a rare moment where reliable cash payouts and balance sheet strength matter more than market mood. This article walks through three large cap UK dividend stocks that appear well aligned with this rate shock and explains how each might fit into your watchlist.
The three stocks profiled below are a starter set. The full screen also identified 26 additional UK large caps with similar yields, balance sheet quality and dividend histories that deserve a closer look.
If you want to go straight to the broader opportunity, use the UK Large-Cap Dividend Stocks screener to identify, filter and analyze the higher conviction ideas that fit your own income brief.
Big Yellow Group (LSE:BYG)
Big Yellow Group is a UK self storage REIT in the FTSE 250, aligned with the UK Large Cap Dividend Stocks theme as an asset backed, income focused play. It generated about £209 million from self storage and related services in the UK and has a market value of roughly £1.8b.
For income investors, Big Yellow Group combines a REIT structure, a dividend yield around 5% and a UK focused, asset heavy portfolio that can add a domestic, relatively defensive flavour to a dividend basket in a higher rate setting. The share price has come under pressure, which leaves the stock trading on a P/E of 14.7x and at a reported discount to estimated fair value. Activist investors are publicly arguing the real estate is worth more than the current market capitalisation suggests. The key question now is how that tension between cash payouts, debt costs and asset values ultimately lands if a single unseen pressure shifts.
If that unseen pressure worries you, go straight to the 2 key rewards and 2 important warning signs to see what might be masking value or signalling strain.
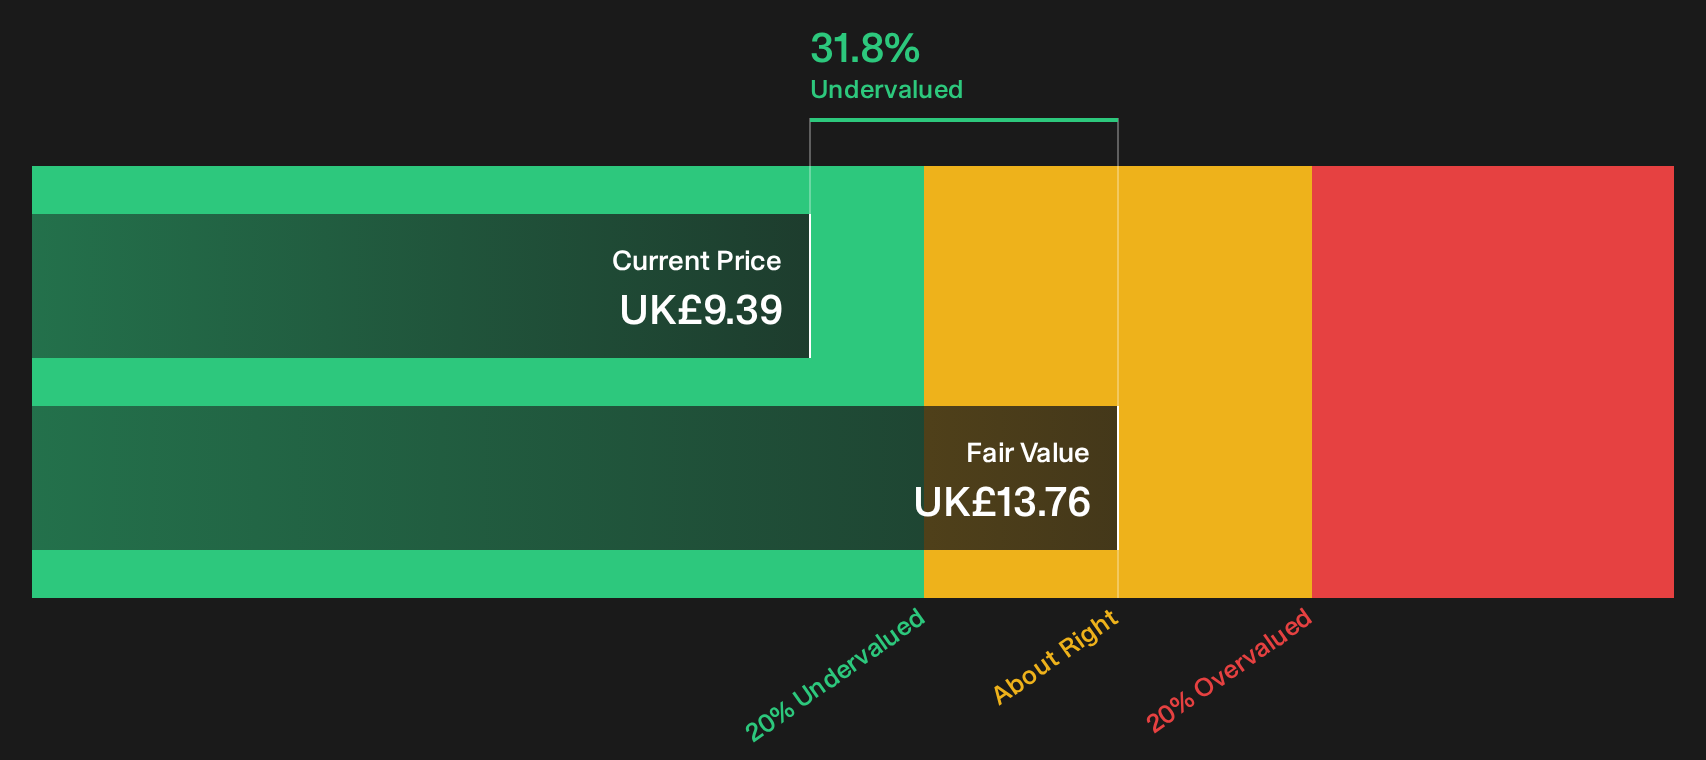
Ninety One Group (LSE:N91)
Ninety One Group is an independent asset manager listed in the UK, fitting the Large Cap Dividend Stocks theme through a fee based model that lends itself to steady cash generation and, in better markets, a supportive backdrop for regular income.
Ninety One Group runs a global investment management franchise for institutional and retail clients, earning £650 million from its Investment Management Business and carrying a market value of about £1.9b.
"Repositioning toward emerging market private credit and away from developed market private credit, backed by seed capital for new EM focused funds and a Saudi domestic credit vehicle, opens a distinct fee pool that can influence overall revenue mix and margin outcomes as these platforms are funded and scaled."
For income focused holders, a lot now hinges on how one unseen pressure shapes the balance between fee rates, expenses and long term payout capacity.
That pressure point is exactly what the full narrative for Ninety One Group unpacks, showing where Ninety One Group’s fee mix, capital returns and risks may be quietly decoupling.

Aberdeen Group (LSE:ABDN)
Aberdeen Group fits the UK Large Cap Dividend Stocks theme as a diversified, fee based asset manager where income potential leans on a broad platform rather than a single product cycle.
Aberdeen Group runs global investment, savings and insurance services, generating about £787 million from Investments, £360 million from Interactive Investor, £206 million from Adviser and £3 million from Other, on a market value near £4.0b.
"Rapid expansion of Aberdeen Group’s Interactive Investor platform, with AUMA at £112bn by Q3 2026 and year to date net inflows of £9.3bn that are 58% higher than the prior year, points to continued growth in platform revenue and a rising contribution to group earnings."
This raises the question of what happens to the dividend profile if a single unseen pressure shifts the balance between fee margins, funding costs and payout choices.
That pressure could be the real swing factor, and the full narrative for Aberdeen Group maps how Aberdeen Group’s platform shift, fee mix and risks might be quietly accelerating or masking the income story.

Seeking Alternatives Before Everyone Else?
Fresh opportunities rarely stay quiet for long. Some ideas are already building momentum, while others risk getting caught dropping off the radar. Scan these under the radar for now and act now.
- Spot resilient balance sheets before they fly, using the curated list of solid balance sheet and fundamentals (10 results) that highlights businesses built to handle shocks while income and cash flows still look stable.
- Track potential breakout trends in healthcare technology as 9 healthcare AI stocks surfaces companies riding AI driven shifts in diagnostics, treatment tools and data platforms before the crowd catches on.
- Ride structural power demand themes while they are still building, with 41 power grid technology and infrastructure stocks pinpointing infrastructure players exposed to grid upgrades, electrification and long run network investment.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com