
Will DCF Undervaluation Change SkiStar Stock Narrative
- SkiStar has been assessed using a Discounted Cash Flow model that indicates an intrinsic value above the current market price, supported by a low net debt to EBITDA ratio and a proposed higher dividend. Together, these factors underline the company’s focus on disciplined financing and shareholder returns.
- The valuation work puts SkiStar’s cash generation and balance sheet in the spotlight, since low leverage and a rising dividend proposal can affect how investors view the resilience of its resort investments and the sustainability of capital spending on lifts, snow production and upgrades.
- We will now look at how SkiStar's investment narrative is shaped by this DCF-suggested undervaluation and its low net leverage.
Compare SkiStar's DCF story with other potential opportunities by scanning our hand-picked 197 high quality undervalued stocks that also pair healthy balance sheets with disciplined cash generation.
SkiStar Investment Narrative Recap
To own SkiStar, you need to be comfortable with a resort operator that leans into heavy ongoing investment in lifts, snow systems and beds, while still aiming to fund dividends and keep leverage low. The big near term swing factor is how effectively fresh capacity converts into skier volumes and guest spending through the coming seasons.
Weather remains the clear operational risk. Warmer or inconsistent winters can force higher snowmaking and staffing costs, which pressures margins even if visitor numbers hold up. At the same time, high capital expenditure near 12 to 15% of revenue leaves limited room for cost overruns before free cash flow feels tight.
The recent focus on a higher dividend proposal is the clearest linked announcement. It ties directly into the DCF argument that SkiStar’s cash flows and low net debt to EBITDA ratio can support both investment and shareholder distributions from a position of balance sheet strength.
For you as an investor, that proposed dividend increase is best viewed alongside the firm’s heavy resort and snow production program. A richer payout can be a short term draw, yet it also raises the bar for consistent earnings, particularly if weather or underperforming retail operations limit the benefit from all the new infrastructure.
SkiStar Forecasts Put Numbers Around the DCF Story
SkiStar's narrative projects SEK 5.7b revenue and SEK 797.2m earnings by 2029. This implies 4.6% yearly revenue growth and an earnings increase of about SEK 170m from SEK 627.0m today.
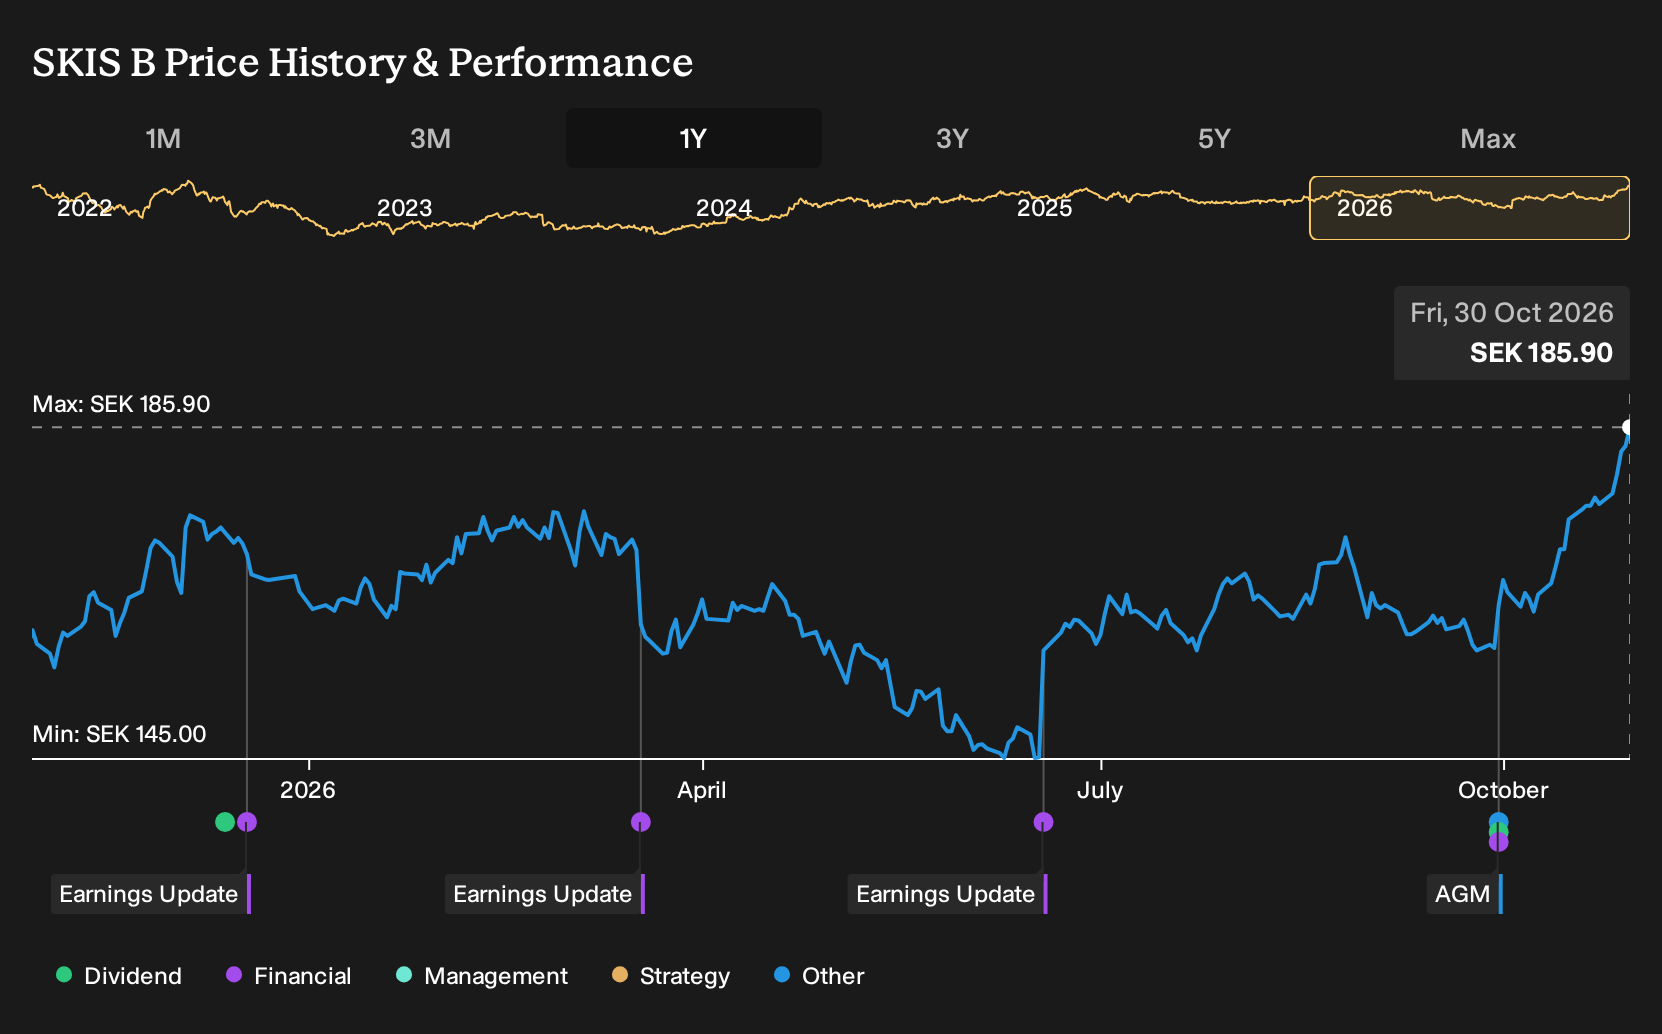
Uncover why SkiStar's fair value indicates a 4% potential upside to its current price and why this gap could narrow quickly.
Exploring Other Perspectives
Across the Simply Wall St Community, two fair value estimates for SkiStar cluster between SEK 193 and SEK 234 per share, so even a small sample shows a wide spread in expectations. Those views sit alongside weather and capex risks on one side, and resort upgrades plus new snow capacity as possible supports on the other. Investor opinions can differ sharply, so it is worth exploring several of these perspectives before deciding how SkiStar fits in your portfolio.
Explore another SkiStar fair value estimate, including one that suggests as much as 26% upside from the current price!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider forming your own view.
- A great starting point for your SkiStar research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for SkiStar. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate SkiStar's overall financial health at a glance.
Looking For More Ideas Beyond SkiStar?
Once you have formed a view on SkiStar, it can help to widen the lens and compare it with other potential opportunities that fit different risk and income profiles. The Simply Wall St Screener lets you move quickly from this single stock to curated sets of companies that match the kind of balance sheet strength, income potential or under-the-radar profile you want to focus on next.
- For investors who like smaller, higher risk opportunities but still care about financial quality, scan through a curated 119 elite penny stocks with strong financials that meet strict balance sheet and profitability filters.
- If you want candidates that mix quality fundamentals with the possibility of mispricing, review a hand picked 611 high quality undiscovered gems that could warrant a closer look.
- Those who care most about resilience and capital protection can filter for a 217 resilient stocks with low risk scores and compare how each one stacks up on debt, cash flow and earnings stability.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com