
Capital Clean Energy Carriers Stock Gains Attention After Strong Q3 Earnings
- Capital Clean Energy Carriers reported Q3 2026 sales of US$138.14 million and net income of US$34.61 million, with basic and diluted earnings per share of US$0.57 from continuing operations.
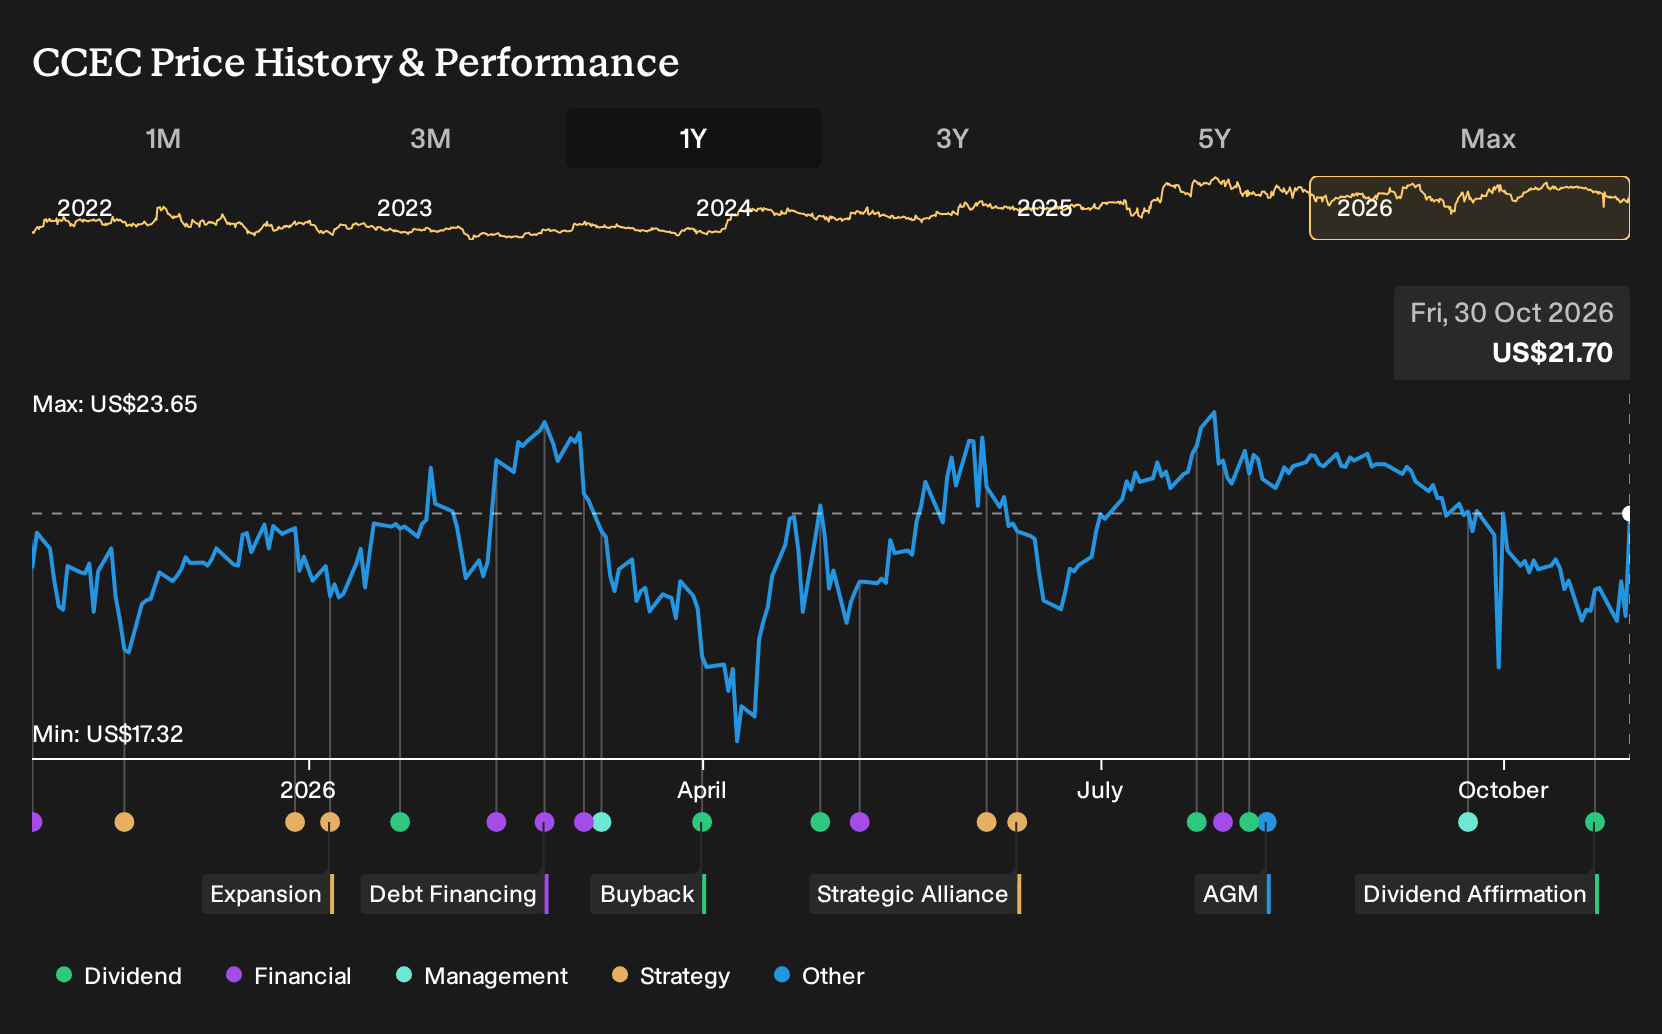
- The nine month 2026 figures show sales of US$341.04 million and net income of US$85.48 million, alongside an affirmed US$0.15 Q3 dividend that reflects the company’s stated focus on contracted cash generation and shareholder payouts.
- This article will now examine how Capital Clean Energy Carriers' third quarter earnings performance may influence the existing investment narrative around contracted cash flows.
Scan beyond Capital Clean Energy Carriers and compare its contracted cash flow profile with list of solid balance sheet and fundamentals (24 results) to see how other businesses combine recurring revenue with balance sheet support.
Capital Clean Energy Carriers Investment Narrative Recap
An investor in Capital Clean Energy Carriers needs to be comfortable with a simple idea. The story leans on multi decade gas shipping charters and a growing fleet that turns contracted days into cash, while leverage and interest costs stay contained. The latest quarter delivered higher sales and earnings per share year on year, which supports that contracted cash flow angle in the near term.
The immediate swing factor still looks like execution on the vessel program and funding, with management previously guiding to leverage peaking over the next few quarters. Nine month net income and earnings per share from continuing operations trailed the prior year, so the main risk around debt costs and non cash items affecting earnings quality remains very much live.
The most relevant recent announcement for this story is the Q3 2026 dividend affirmation of US$0.15 per share. That payout, declared for shareholders of record on 3 November and payable on 12 November 2026, lines up with management’s message that contracted cash generation can support ongoing distributions.
For you as a shareholder, that dividend looks like a real time test of the balance between growth capex and cash returns. Interest payments are not well covered by earnings and free cash flow coverage of dividends is flagged as weak, so any pressure on funding for the newbuild program or a sustained squeeze on margins could quickly turn the payout from a support to a stress point for the Capital Clean Energy Carriers equity story.
Capital Clean Energy Carriers' narrative projects US$892.5 million revenue and US$263.3 million earnings by 2029. This assumes 31.0% yearly revenue growth and an earnings increase of about US$165 million from US$98.3 million today.
Uncover why Capital Clean Energy Carriers' fair value indicates a 19% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
For a very different angle on Capital Clean Energy Carriers, focus on the bearish concern about long haul LNG and ammonia demand. The lowest analysts were pencilling in about US$904.3 million of revenue and US$273.7 million of earnings by 2029 before this Q3 release. That is actually higher than consensus, yet paired with a stricter 8.4x P/E. You can treat this as a reminder that equally informed analysts can read the same backlog and dividend track record and still reach far more cautious conclusions about what today’s valuation already prices in. This fresh earnings print may eventually pull those narratives closer together or push them further apart. It is therefore worth comparing both views before you decide how much risk you want to carry.
Explore 2 other Capital Clean Energy Carriers fair value estimates, including one that suggests it could be worth just $25.83.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Capital Clean Energy Carriers research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Capital Clean Energy Carriers. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Capital Clean Energy Carriers' overall financial health at a glance.
Looking For More Investment Ideas Beyond Capital Clean Energy Carriers?
If the Capital Clean Energy Carriers story has sharpened your thinking about contracted cash flows and balance sheet risk, it can help to view it alongside other opportunities that fit different return profiles and risk appetites. The Simply Wall St Screener lets you filter for very specific traits so you can build a watchlist that matches your own playbook rather than relying on a single stock to carry the thesis.
- For investors who want potential upside with tighter budgets and are willing to research smaller businesses carefully, scan through 8 elite penny stocks with strong financials that already show stronger fundamentals than many peers.
- If value is your priority and you want companies that combine quality metrics with what our models flag as possible mispricing, start with a curated set of 33 high quality undervalued stocks that may merit a closer look.
- Income focused readers who care about consistency and balance sheet resilience can review a hand picked pool of 5 dividend fortresses that aim to pair higher yields with sturdier financial footing.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com