
CoStar Group (CSGP) Could Be 16% Below Fair Value On Profit Return And Guidance Update
CoStar Group (CSGP) has returned to the spotlight after reporting third quarter 2026 results and updating both full-year and fourth-quarter revenue guidance, giving investors fresh numbers to reassess the stock.
The guidance update landed alongside a sharp 7.21% one-day share price gain to US$30.17, even though the stock is still down 54.07% on a year-to-date share price basis and total shareholder return has fallen 56.15% over the past year. Recent momentum has picked up from a low base as investors reassess CoStar Group after the earnings swing back to profit and the refined outlook for 2026 revenue.
Scan how CoStar Group compares to other real estate and data-driven platforms by reviewing our hand picked 33 high quality undervalued stocks that also pair cash generation with balance sheet strength.
That 7.21% jump on the day, against a share price that is still heavily lower over the year, raises a simple question. Is the market finally catching up to CoStar Group’s fundamentals, or just swinging back on sentiment as investors reprice the stock’s valuation?
Most Popular Narrative: 16% Undervalued
CoStar Group’s most followed narrative pegs fair value at $35.85 versus the latest $30.17 close. The story hinges on how well management executes from here rather than on a lack of upside in the model.
The key thing that has to go right is that CoStar Group turns Homes.com, Apartments.com, Zonda, international portals and AI products into a durable, profitable multi-vertical platform, despite muted bookings, lower revenue guidance and competitive pressure in multifamily advertising.
The current valuation of CoStar Group implies that the market is discounting execution risk around revenue growth, Homes.com scalability and AI disruption more heavily than the recent uplift in margins and record adjusted EBITDA guidance.
See why 31 investors see CoStar Group as 16% undervalued.
Result: Fair Value of $35.85 (UNDERVALUED)
Still, the CoStar Group story can change quickly if muted net new bookings persist or if pricing pressure at Apartments.com continues to weigh on segment revenue.
Find out about the key risks to this CoStar Group narrative.
Another View: CoStar Group On Earnings Multiples
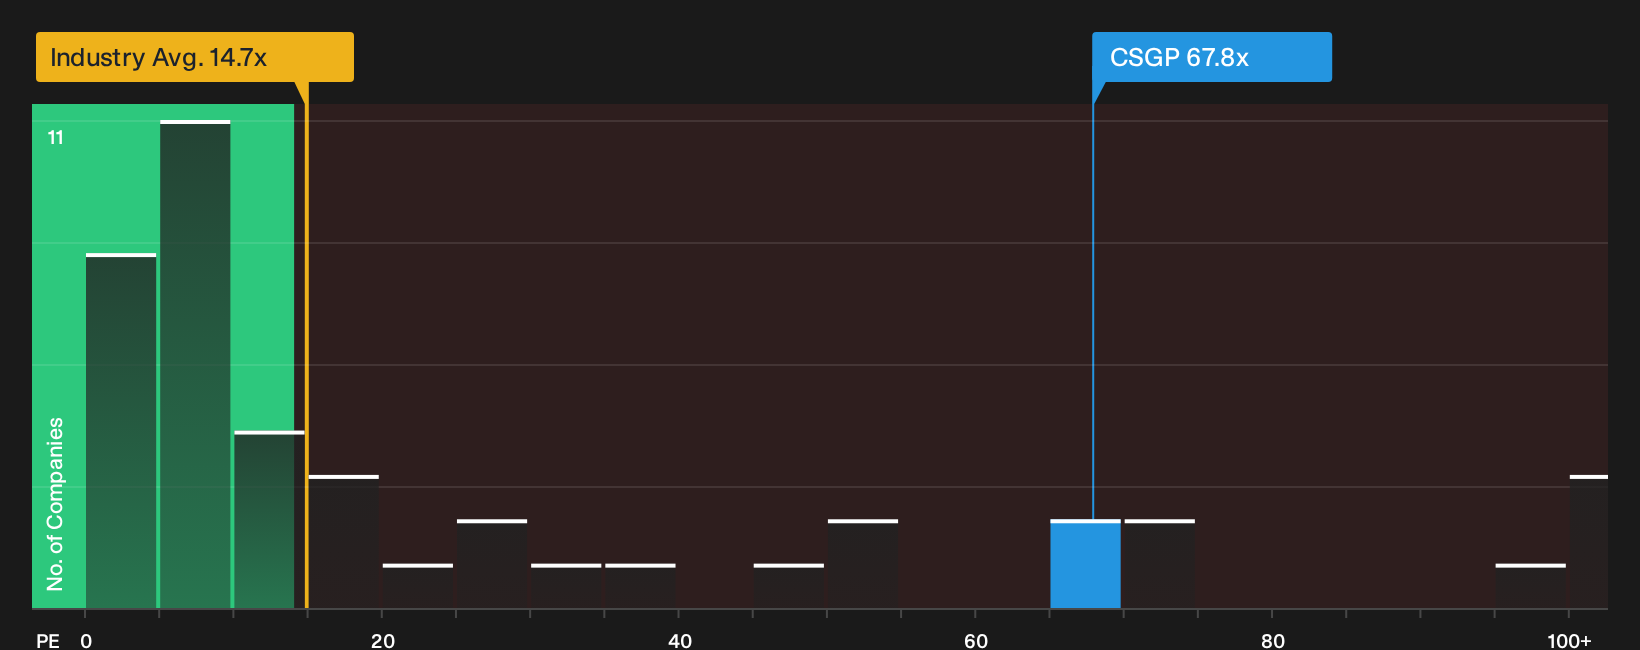
The DCF story presents CoStar Group as trading about 60% below an estimated fair value of $75.35, yet the earnings multiple suggests a very different picture. At a P/E of 67.8x versus a US Real Estate average of 14.7x and a fair ratio of 44.4x, the stock appears expensive on profits, both relative to the sector and relative to where the ratio could migrate over time. That gap highlights valuation risk if earnings forecasts or sentiment weaken. Investors may therefore wish to decide which lens they find more useful for their own work on CSGP.
For a deeper look at what the current profit-based valuation implies for CoStar Group, and how that compares to peers, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If sentiment around CoStar Group feels split after these numbers, that is the moment to move quickly and interrogate the figures yourself rather than follow the crowd. To see what the most optimistic investors are focusing on, review the 3 key rewards
Looking for more investment ideas beyond CoStar Group?
If CoStar Group has sharpened your focus, use that momentum and line up your next potential opportunities with a few targeted stock searches on Simply Wall St.
- Target potential mispricings by scanning a 33 high quality undervalued stocks that combines solid cash flows with quality fundamentals.
- Strengthen your defense by reviewing a 29 resilient stocks with low risk scores designed for resilience when conditions get choppy.
- Hunt for future leaders early by checking a 19 high quality undiscovered gems that highlights quality companies still flying under most investors' radar.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com