
Is RBC Bearings (RBC) Fully Valued As Strong Q2 Results And Guidance Meet A Selloff?
RBC Bearings stock reacts to strong Q2 results and guidance
RBC Bearings (RBC) just paired a solid fiscal Q2 earnings report with fresh guidance for the upcoming quarter, yet the share price dropped on the news, giving investors a fresh setup to reassess the stock.
The immediate reaction has been harsh. The share price fell 6.8% on the day of the Q2 release and is down about 10.4% over the past month and 19% over the past quarter, even though the year-to-date share price return is slightly positive and the 1-year total shareholder return sits near 8%, building on a very large 3-year total shareholder return and a near doubling over 5 years.
Scan how RBC Bearings compares to other engineered industrial players by running the curated list of solid balance sheet and fundamentals (24 results) before this post earnings move fully resets expectations.
So is this pullback in RBC Bearings a verdict on the business, which just posted higher sales and earnings, or a sharp reset in what investors are willing to pay? The valuation section has the clues.
Most Popular Narrative: 26.7% Undervalued
RBC Bearings last closed at $462.21, while the most widely followed narrative anchors fair value near $630.67. As a result, the recent pullback is being weighed against a much higher long term valuation story built on backlog, cash generation and capacity investment.
Consistent free cash flow generation, shown by US$342.6 million of free cash flow in fiscal 2026 with conversion above 100% and US$146.9 million in fiscal Q1 2027, together with ongoing debt reduction and the plan to fully repay the term loan by November 2026 while still funding acquisitions like PSC Couplings, can widen RBC Bearings’ capacity for future M&A and capital investment that supports revenue and net margins.
See why 4 investors see RBC Bearings as 27% undervalued.
Result: Fair Value of $630.67 (UNDERVALUED)
Still, this narrative can crack if supply chain issues hit specialty alloys for aerospace and defense, or if new capacity investments end up underutilized.
Find out about the key risks to this RBC Bearings narrative.
Another View: RBC Bearings Looks Expensive On Earnings
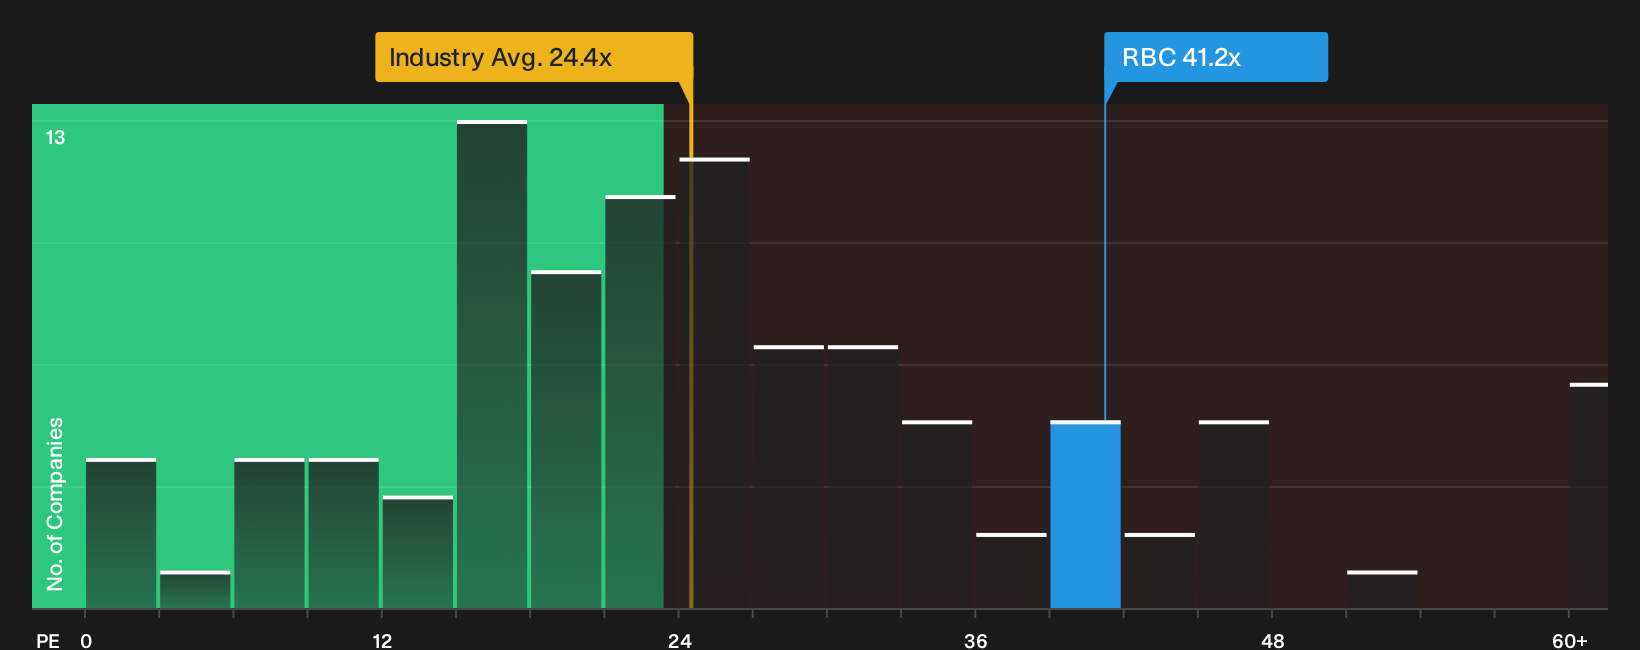
The fair value story around RBC Bearings points to upside, yet the plain P/E math paints a very different picture. The stock trades at 41.2x earnings compared with 24.2x for the US Machinery group and a peer average of 32.6x, while the fair ratio sits nearer 26.1x.
That gap suggests investors are already paying a rich premium for RBC Bearings, with limited room for disappointment if execution or demand stumbles. The question is simple for anyone reassessing the pullback: Is this premium a margin of safety, or a valuation risk that could compress if sentiment cools, as shown in See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Sentiment around RBC Bearings might look split, so move quickly, review the full dataset, and weigh the upside case for yourself with 3 key rewards.
Looking for more RBC Bearings sized investment ideas?
If you like how RBC Bearings sharpens your focus, do not stop here. Cast the net wider now so you are not chasing the next move late.
- Target potential mispricings early by scanning the 33 high quality undervalued stocks and line up candidates before the crowd starts paying attention.
- Identify potential income ideas by reviewing the 5 dividend fortresses and shortlist companies that might support a more predictable cash return profile.
- Limit potential downside by filtering through the 29 resilient stocks with low risk scores and concentrate on businesses with sturdier financial footing.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com