
Proximus Stock In Focus After Mixed Third Quarter Earnings
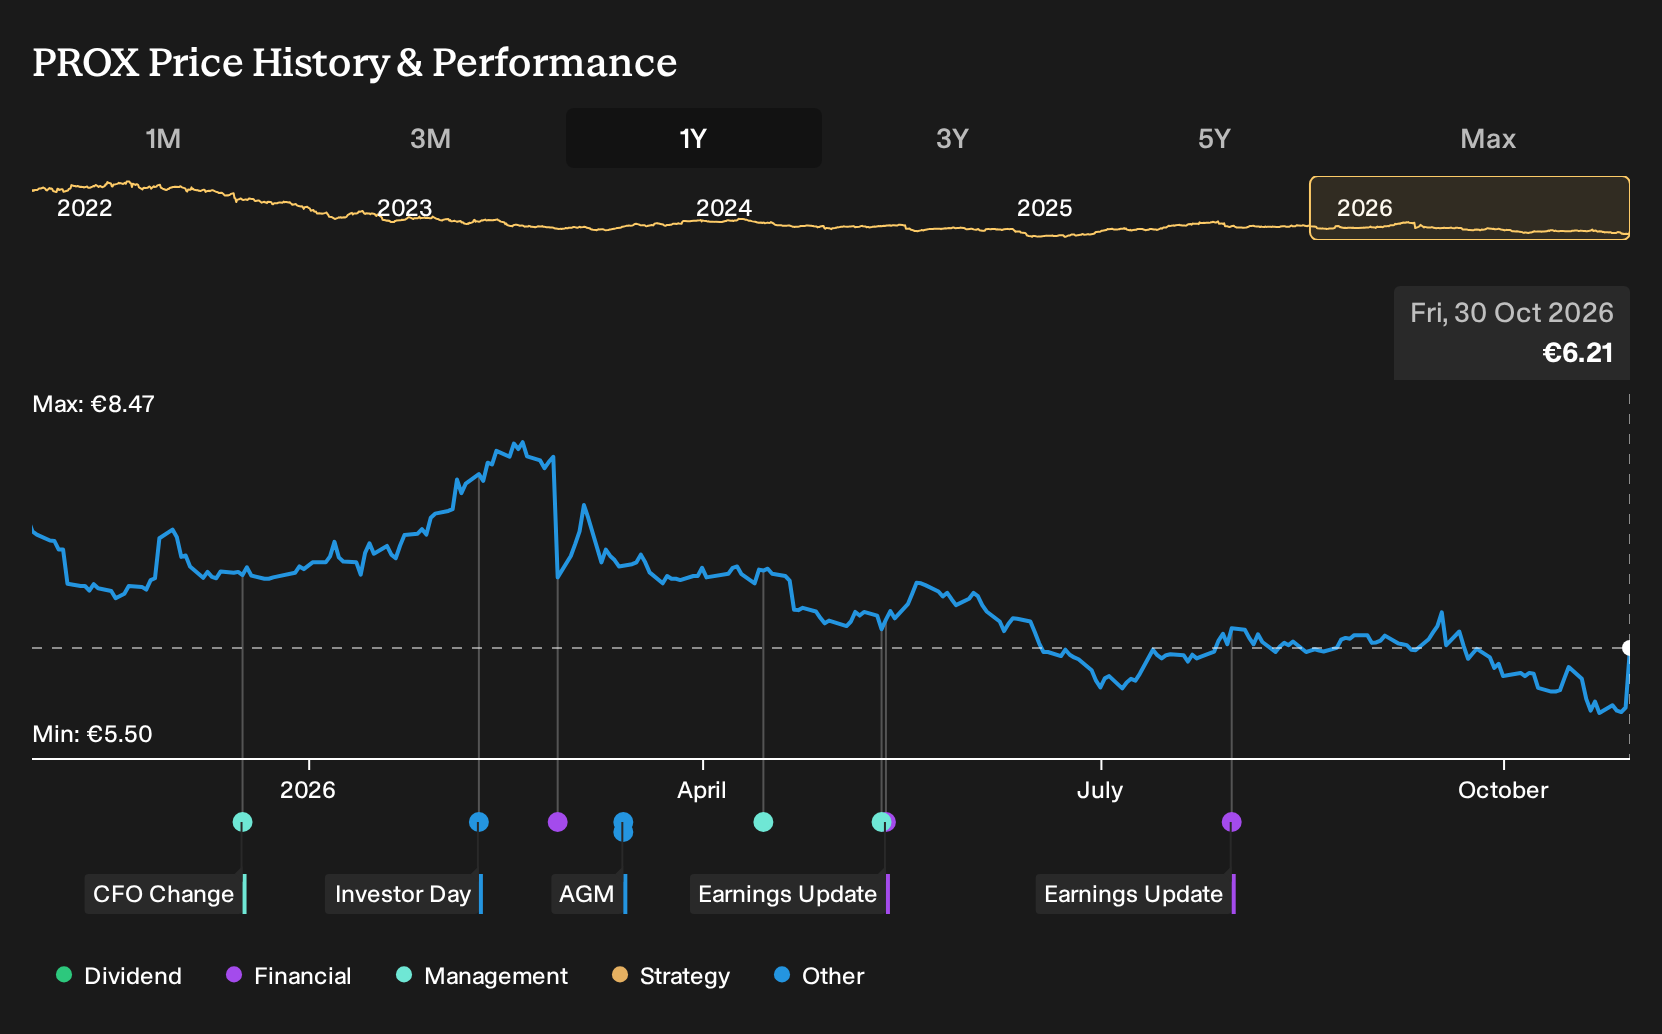
- Proximus PLC reported third quarter 2026 revenue of €1,537 million and net income of €96 million, with basic earnings per share from continuing operations of €0.30.
- Across the first nine months of 2026, Proximus reported pressure on sales and revenue, while earnings per share from continuing operations remained above €1.
- This raises the question of how Proximus's investment narrative could be influenced by higher quarterly net income alongside softer third quarter revenue.
Proximus Investment Narrative Recap
To own Proximus, you need to be comfortable with a story where heavy fiber spending and cost savings eventually support steadier earnings, while competition in Belgium keeps pricing tight. The third quarter results fit that picture. Revenue for the period softened, but net income and earnings per share from continuing operations were higher than a year ago.
The key short term swing factor is still execution on fiber rollout and efficiency plans without further pressure on domestic service revenue. The biggest risk remains a mix of high CapEx, debt and a dividend path that leans on funding beyond organic free cash flow. This quarter does not materially change that risk balance.
With no fresh corporate announcements tied directly to this earnings release, the most relevant context is management’s existing guidance around CapEx and leverage. The group is still targeting around €1.3b of investment in 2026 and a leverage ratio just below 3x net debt to EBITDA through 2028, alongside a dividend trajectory that is not fully cash covered in the near term.
In that context, the third quarter pattern of softer revenue but higher quarterly profit sharpens the focus on execution. Investors will likely keep testing whether Proximus can deliver on fiber build, Unifiber integration and the cost efficiency program, while avoiding further erosion in domestic margins. The current setup leaves limited room for missteps before pressure builds on earnings and the balance sheet.
Analysts expect Proximus to reach about €6.2 billion in revenue and €236.3 million in earnings by 2029, with revenue described as relatively flat and earnings projected to decline by €126.7 million from €363.0 million today.
Uncover how Proximus' fair value indicates a 27% potential upside to its current price, which could narrow quickly if sentiment improves.
Exploring Other Perspectives
One alternate view around Proximus focuses on a tougher competition story rather than fiber execution. The lowest analysts were already pencilling in flat revenue at around €6.0b by 2029 and earnings closer to €230.1 million. That is a much more cautious script. This new earnings release could prompt those projections to shift, in either direction, so compare several viewpoints before forming your own.
Explore 2 other Proximus fair value estimates, including one that suggests it could be worth just €7.92.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis.
- A great starting point for your Proximus research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Proximus. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Proximus' overall financial health at a glance.
Looking For More Investment Ideas Beyond Proximus?
If the Proximus story has you thinking about earnings resilience, balance sheets and dividends, broaden your watchlist with a few focused stock sets built to highlight different strengths.
- For investors who care most about financial strength, start with a list of solid balance sheet and fundamentals (198 results) that can better withstand pressure on cash flow.
- If steadier income matters more to you than price swings, scan a curated pool of 225 dividend fortresses that aim to keep distributions flowing.
- If you prefer potential mispriced opportunities, even if they are less widely followed, then sort through a targeted group of 611 high quality undiscovered gems that pair quality fundamentals with lower market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com