
How Strong Earnings Growth Will Impact Balchem (BCPC) Investors
- Balchem Corporation reported third quarter 2026 sales of US$290.66 million and net income of US$46.73 million, with basic EPS from continuing operations of US$1.47, alongside a nine month sales figure of US$845.36 million and net income of US$131.63 million.
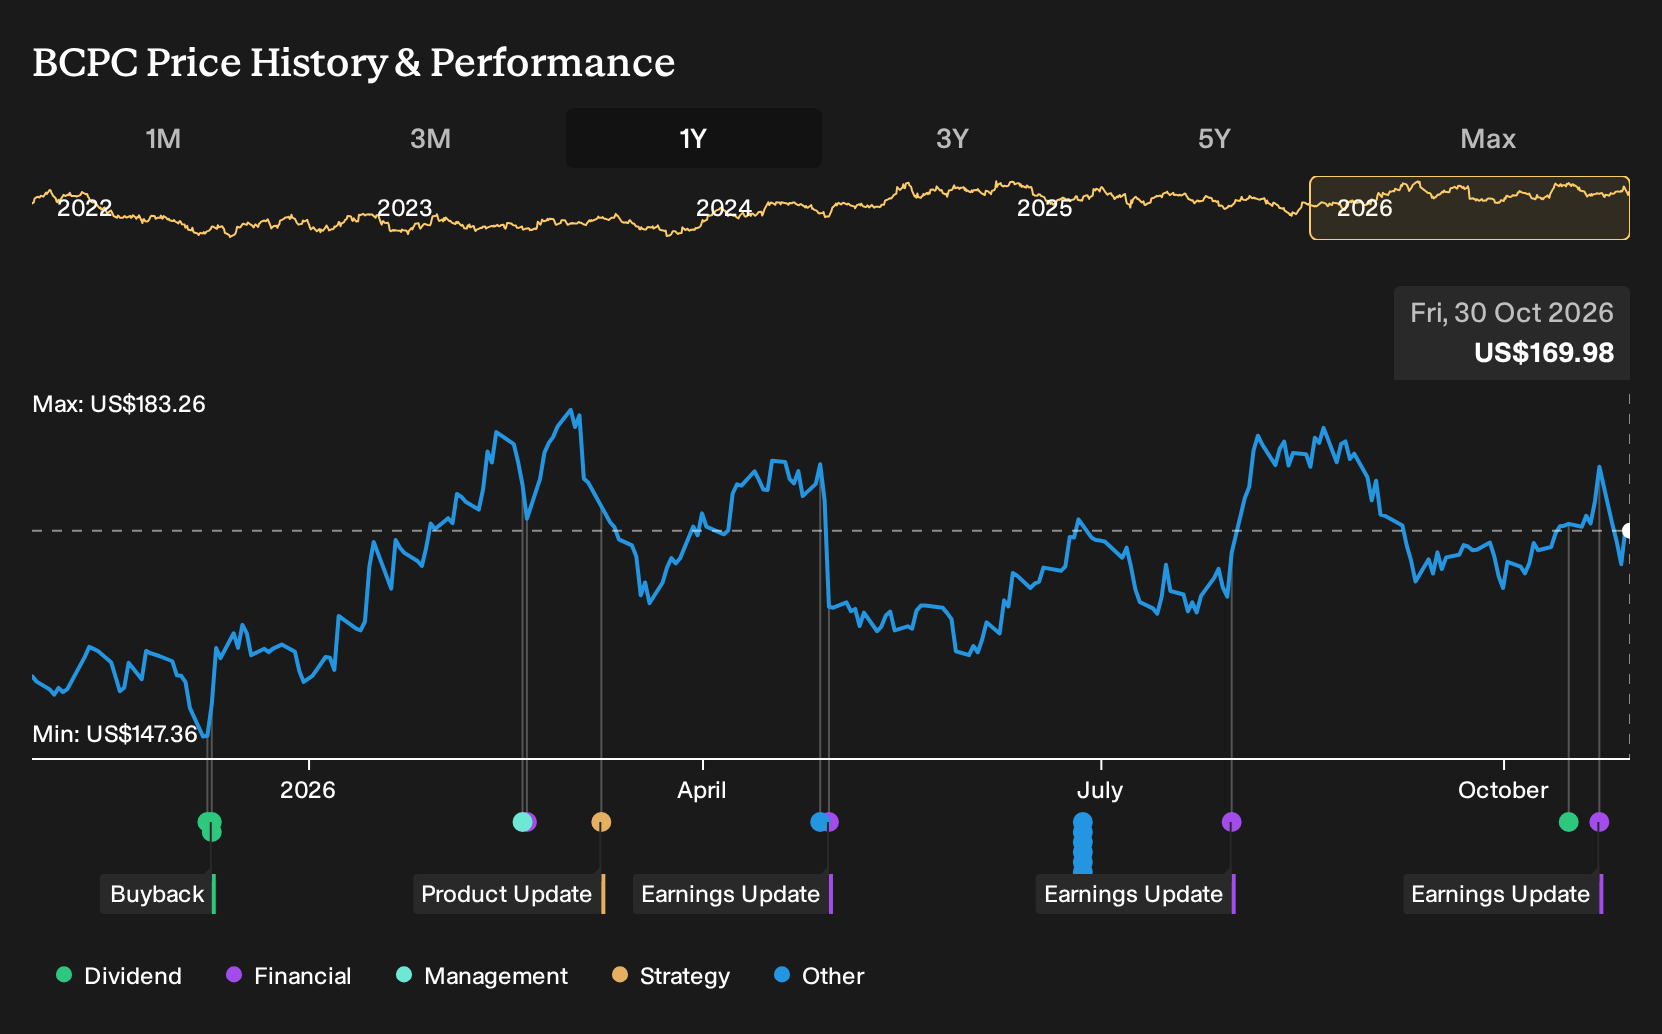
- The business also completed a share repurchase of 507,286 shares for US$83.49 million under its existing program, which reduces the share count and concentrates future earnings over a smaller base.
- We will now look at how Balchem's higher earnings per share might influence the existing investment narrative that analysts have outlined.
Balchem Investment Narrative Recap
To own Balchem, you need to be comfortable with a specialty ingredients producer that leans on science backed products, capacity investments and disciplined cost control. The latest quarter shows sales and net income for both the three and nine month periods at levels that support this thesis, without dramatically changing it. The key near term swing factor still sits in execution around capacity ramp and mix toward higher value ingredients.
The main operational risk remains input cost and freight volatility, especially where petrochemical based materials and routes linked to Middle East conflict are involved. If these pressures stay elevated while pricing power in Human and Animal Nutrition softens, the recent earnings strength could be harder to sustain. On the flip side, any continued benefit from European trade measures on choline keeps supporting Animal Nutrition economics.
The most relevant announcement alongside the results is the completion of the 507,286 share repurchase for US$83.49 million. That buyback trims the share count, so each dollar of earnings now spreads over fewer shares, which you see in the higher basic EPS from continuing operations in both the quarter and year to date figures.
For you as a shareholder or prospective buyer, this repurchase links directly to the existing catalysts. A lower share count amplifies any future benefit from the new microencapsulation facility, the clinical data supporting VitaCholine and the ongoing shift toward branded nutrition ingredients. At the same time, it can magnify any hit to earnings if trade support in Europe weakens or if input costs rise faster than Balchem can reprice its portfolio.
What The Current Forecasts Assume For Balchem
Balchem's narrative projects US$1.3b revenue and US$202.3 million earnings by 2029. That aligns with analyst expectations for 6.2% yearly revenue growth and an earnings increase of about US$37.9 million from the current US$164.4 million level.
Uncover why Balchem's fair value indicates a 23% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternate narrative focuses on underused capacity at Balchem's new microencapsulation plant. The more cautious analysts were already assuming lower margins and only about US$1.3b revenue and US$196.1 million earnings by 2029 before this earnings beat and buyback update. That group presents a tighter story. You can compare both views and decide which assumptions feel more realistic to you.
Explore 3 other Balchem fair value estimates, including one that suggests as much as 100% downside from the current price!
The Verdict Is Yours
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Balchem research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for Balchem. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Balchem's overall financial health at a glance.
Looking For More Investment Ideas Beyond Balchem?
Once the Balchem story is clear in your mind, the next step is to compare it with other opportunities that fit different risk and income profiles. The Simply Wall St Screener can help you quickly narrow the market down to a shortlist that matches what you care about most.
- If capital preservation is high on your list, start with companies that screen well on resilience and financial risk through the 29 resilient stocks with low risk scores.
- If reliable income streams matter more to you than fast growth, scan high yield payers with stronger balance sheets using the 5 dividend fortresses.
- If you want to stay early on quieter stories with solid fundamentals, hunt for lesser known quality businesses through the 19 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com