
Is Shutterfly Photo Gifts Altering The Investment Case For Disney Stock (DIS)?
- Shutterfly and Walt Disney announced a photo gift alliance that makes Shutterfly the Official Photo Gift Partner for major Disney parks, cruises and Aulani, with expanded Disney themed products and a dedicated shopping hub for vacation keepsakes.
- The partnership deepens Disney's ability to turn park and cruise visits into higher margin merchandise and direct to consumer sales, extending each trip's economic value beyond the days spent on site.
- We will look at how Disney's investment narrative is shaped by this Shutterfly alliance that links Experiences attendance to merchandise demand.
Scan other experience driven consumer stocks that could see similar merchandise momentum by reviewing our curated 19 high quality undiscovered gems, which is aligned with Disney's focus on turning guests into long term customers.
Walt Disney Investment Narrative Recap
To own Walt Disney, you generally have to believe the Experiences engine, parks, cruises and resorts, and a more profitable streaming portfolio can keep turning its intellectual property into steady earnings, even as consumer demand and ad markets move around. The Shutterfly alliance fits that story, but on its own it looks incremental rather than a major swing factor for near term results.
Right now, the key short term swing factor is how Experiences and streaming perform into the November 17 quarterly report, especially with prior commentary about streaming ad softness and regional park pressure. The biggest risk is that weaker ad markets or prolonged consumer strain in Asia parks offset cost savings and operational progress elsewhere.
The Shutterfly partnership links directly to Disney Experiences, where management has been investing in capacity and new offerings to support revenue and earnings over time. By tying PhotoPass output to a broader range of licensed merchandise, Disney is trying to extract more value from each visit without relying only on ticket pricing or on site spending.
This matters as investors watch Experiences and streaming as key catalysts at the upcoming earnings release and through the holiday season. If guest engagement around EPCOT's International Festival of the Holidays and new content like Hexed feeds into higher demand for personalized keepsakes through Shutterfly, it could modestly support merchandise revenue, although the financial impact is likely small relative to Disney's US$98.9b in annual sales.
Walt Disney's current analyst narrative points to revenues of US$113.7b and earnings of US$13.5b by 2029, built on an assumed 4.8% yearly revenue growth rate. That path implies earnings today of about US$8.6b would need to rise by US$4.9b to reach the 2029 consensus target.
Uncover why Walt Disney's fair value indicates a 14% potential upside to its current price that may not last much longer.
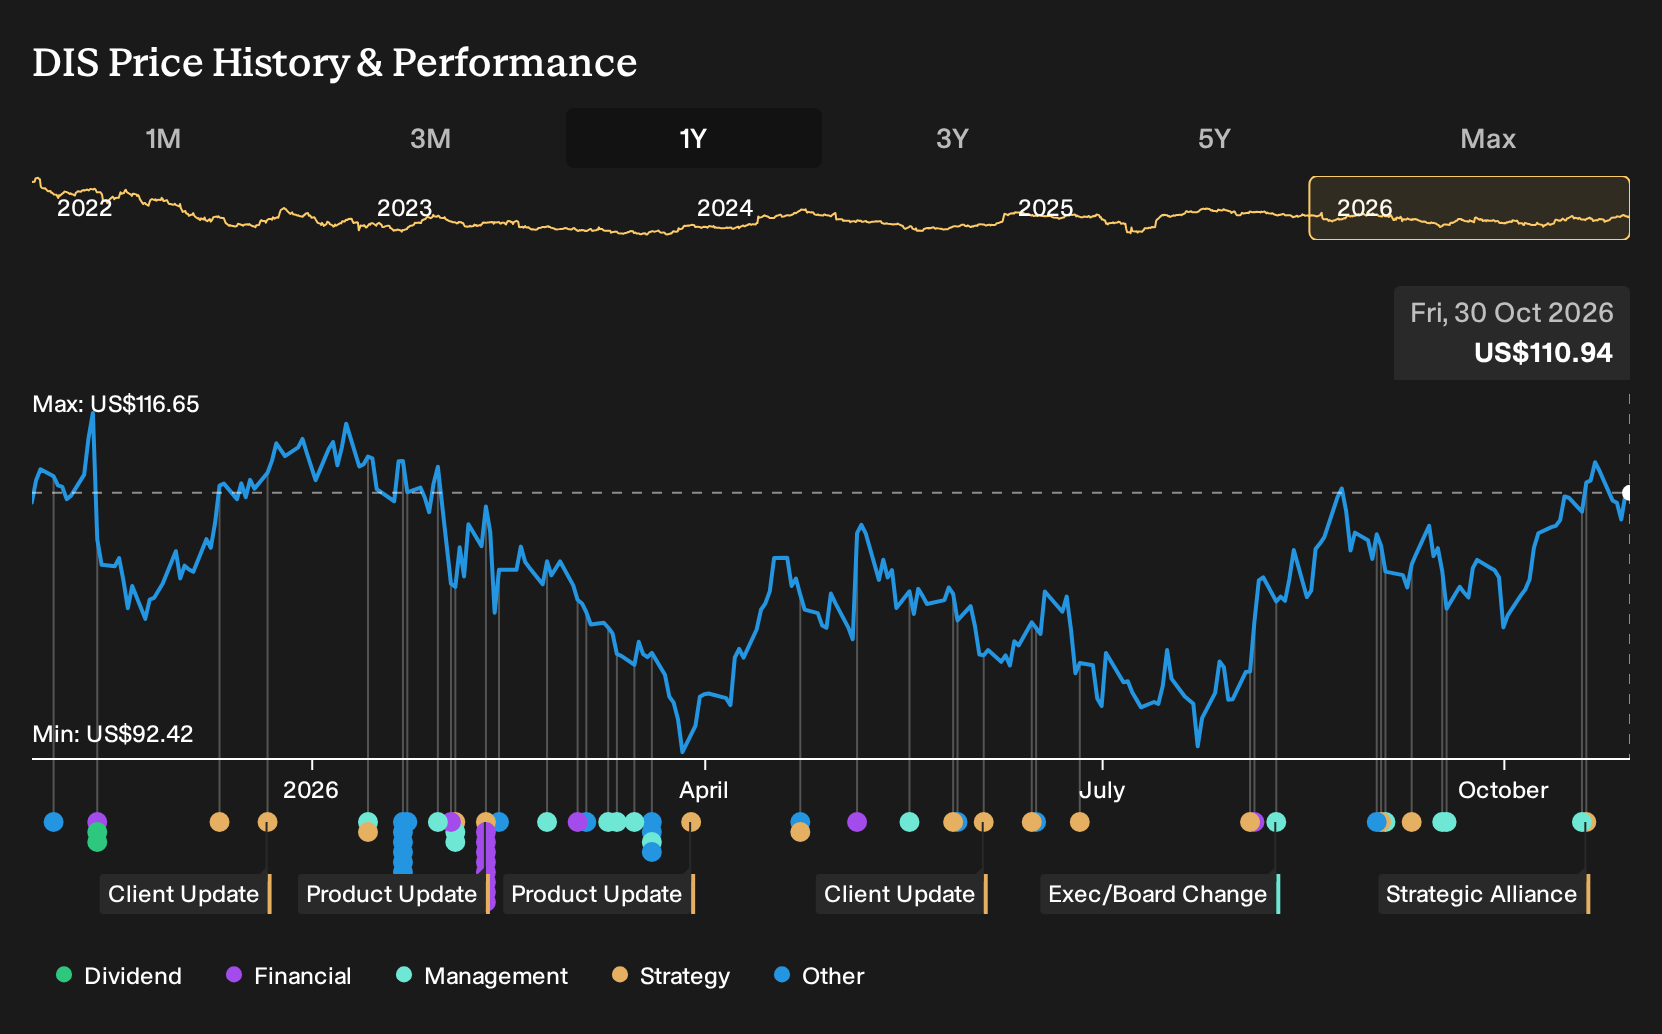
Exploring Other Perspectives
Across five fair value estimates from the Simply Wall St Community, Disney lands in a tight band between about US$117.6 and US$134.6, which still leaves plenty of room for disagreement on upside. When this is set against risks around streaming ad softness and park demand, it results in a wide spectrum of views worth exploring.
Explore 4 other Walt Disney fair value estimates, including one that suggests as much as 21% upside from the current price.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Walt Disney research is our analysis highlighting 2 key rewards that could impact your investment decision.
- See our latest analysis for Walt Disney. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Walt Disney's overall financial health at a glance.
Looking for more Walt Disney style investment ideas?
If the Walt Disney story has you thinking about where else long term compounding might come from, the Simply Wall St Screener can help you sift through the market in a structured way rather than jumping from ticker to ticker.
- If you want potential value combined with quality fundamentals, start by scanning a curated set of 33 high quality undervalued stocks that may warrant a closer look.
- For investors who care most about balance sheet strength and resilience, focus on our list of solid balance sheet and fundamentals (24 results) to see which businesses currently clear that hurdle.
- If you prefer steadier profiles with fewer red flags, narrow your search with a 29 resilient stocks with low risk scores that aims to highlight companies with more measured risk profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com