
Is Eagle Bancorp (EGBN) Fairly Valued After Its Return To Profit?
Eagle Bancorp (EGBN) returned to profitability in its third quarter, reporting US$24.25 million in net income after a loss a year earlier, along with a US$0.01 per share cash dividend.
The earnings rebound and dividend announcement come alongside a strong price recovery for Eagle Bancorp, with a 30-day share price return of 17.27% and a year-to-date move of 59.62%. The 1-year total shareholder return of 99.03% points to momentum that has built over time, although longer-term holders still face a 5-year total shareholder loss of 32.39%.
Compare Eagle Bancorp's rebound with hand picked regional financials by scanning the list of solid balance sheet and fundamentals (24 results) that may offer similar earnings momentum with sturdier fundamentals.
Eagle Bancorp shares have already rebounded sharply on the earnings turnaround, yet the valuation still needs to answer a basic question: Is most of the upside already in the price, or not yet?
Most Popular Narrative: 40% Undervalued
The most followed narrative on Eagle Bancorp pins fair value at about $33.42, almost exactly in line with the recent $33.28 close, yet still frames the stock as meaningfully undervalued when weighing its future cash generation against that price.
Completion of the office credit cleanup, backed by independent portfolio validation and aggressive charge offs, positions the balance sheet for lower future provisions and a clearer path to growing earnings and book value.
A shift in loan mix toward C&I, with growing C&I balances and deposits in a defense and security oriented government contractor base, should support more diversified revenue and a structurally higher net interest margin.
See why 2 investors see Eagle Bancorp as 0% undervalued.
Result: Fair Value of $33.42 (UNDERVALUED)
Still, the Eagle Bancorp story can break if office and multifamily credit issues deepen, or if funding stays expensive and squeezes the expected margin rebuild.
Find out about the key risks to this Eagle Bancorp narrative.
Another View: Eagle Bancorp Through The P/E Lens
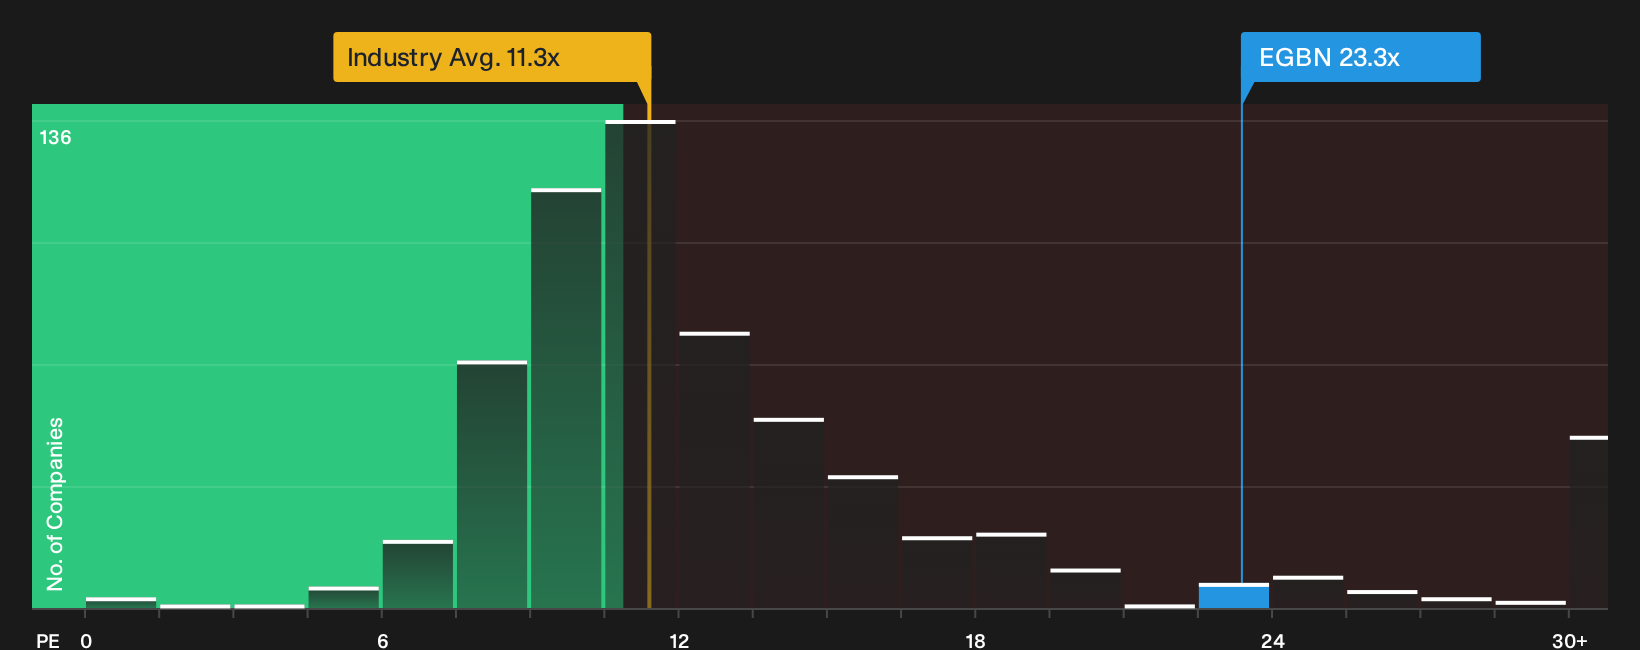
The fair value narrative around Eagle Bancorp leans on future cash generation, yet the current P/E of 23.3x paints a tighter picture. That multiple is higher than the US Banks industry at 11.4x and above a fair ratio of 17.2x, which points to less room for error if earnings disappoint.
For investors who prefer to anchor on earnings multiples rather than cash flow models, this richer P/E versus both peers and the fair ratio hints at valuation risk that relies heavily on strong execution. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
The Eagle Bancorp story so far presents mixed messages. Move quickly, consider both the potential upside and the red flags, and weigh the 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Eagle Bancorp?
If Eagle Bancorp has sharpened your focus, do not stop here. Broaden your watchlist with fresh opportunities that match your risk appetite and income goals.
- Target resilient balance sheets and steady fundamentals by scanning the list of solid balance sheet and fundamentals (24 results), which can help anchor a portfolio when conditions change.
- Look for potentially mispriced quality and compare Eagle Bancorp with a 33 high quality undervalued stocks, which might present different valuation characteristics.
- Explore your income options by reviewing potential higher-yield opportunities through a curated 5 dividend fortresses ahead of upcoming payout dates.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com