
Earnings Beat At Bunge Global Stock Has Changed Its Investment Story
- Bunge Global reported third quarter 2026 sales of US$23,804 million and net income of US$318 million, with basic EPS from continuing operations of US$1.65.
- An unusual feature of this update is the nine month sales figure of US$69,706 million alongside net income of US$1,064 million, which highlights how thin profitability can be in global agribusiness processing.
- The focus now turns to how Bunge Global's stronger soybean processing earnings might reshape the investment narrative built around the Viterra integration.
Scan other global processors riding similar earnings storylines by comparing Bunge Global against the hand picked list of solid balance sheet and fundamentals (24 results) in agribusiness and adjacent food supply chains.
Bunge Global Investment Narrative Recap
Bunge Global appeals to shareholders who want exposure to global food, feed and renewable fuel flows, with earnings tied closely to processing spreads and volume rather than to more speculative growth narratives. The big operational swing factor remains how efficiently the enlarged platform runs. The latest quarter shows soybean and softseed processing contributing meaningfully, which supports that thesis.
In the short term, the catalyst is clear. Investors are watching whether Viterra integration, cost savings and portfolio pruning continue to translate into steadier segment profits, while softer refined oils and merchandising do not erode group margins. The key risk remains cash generation. Higher leverage and thinner free cash flow leave less room for execution missteps.
A central datapoint for that discussion is the recent US$69,706 million nine-month sales figure and US$1,064 million in net income. These numbers sit alongside basic EPS from continuing operations of US$5.51 and illustrate that processing-focused agribusiness can produce sizeable earnings on slim net margins when operations are closely aligned with demand.
Regarding catalysts, that earnings profile is directly linked to the Viterra combination. Cost and commercial synergies, together with a broader origination and crush footprint, give Bunge Global additional levers if any one segment encounters challenges. The operational question for you as a shareholder is whether integration, capital discipline and debt service all progress in step from here.
What Analyst Assumptions Signal for Bunge Global
Analysts sketch a fairly specific path for Bunge Global. They are penciling in revenue growth of 1.2% per year over the next three years and a lift in profit margins from 1.1% today to 3.5% by around 2029. On their numbers, earnings today of about US$1.0b would rise to consensus earnings of US$3.4b by 2029, with some forecasters sitting lower at US$2.8b. That implies roughly a 3.4x increase in profits over the period if the higher figure is reached.
Those same projections assume the share count gradually shrinks as buybacks continue, with an expected 0.64% annual reduction in shares outstanding over the next three years. For an existing investor, that backdrop ties the earnings story to both operational execution on the enlarged platform and disciplined capital returns. It means your view on Bunge Global is not just about volume and crush spreads, but also about whether the business can expand margins while steadily retiring stock and servicing a larger debt load.
The forecast path also builds in a meaningfully lower valuation multiple. To bridge from current pricing to the analyst target, the stock would need to trade on a P/E of 9.7x applied to those 2029 earnings, down from 21.0x today and below the current 16.9x P/E seen across the wider US food peer group. That assumption effectively bakes in both higher earnings and a cheaper earnings multiple, which can serve as a useful stress test for readers checking whether their own expectations around Bunge Global line up with the consensus work.
Bunge Global's narrative projects US$95.3b revenue and US$3.4b earnings by 2029. This rests on 1.2% yearly revenue growth and roughly a 3.4x earnings increase from about US$1.0b today.
Uncover why Bunge Global's fair value signals a 47% potential upside to its current price, a gap that could narrow quickly if sentiment shifts.
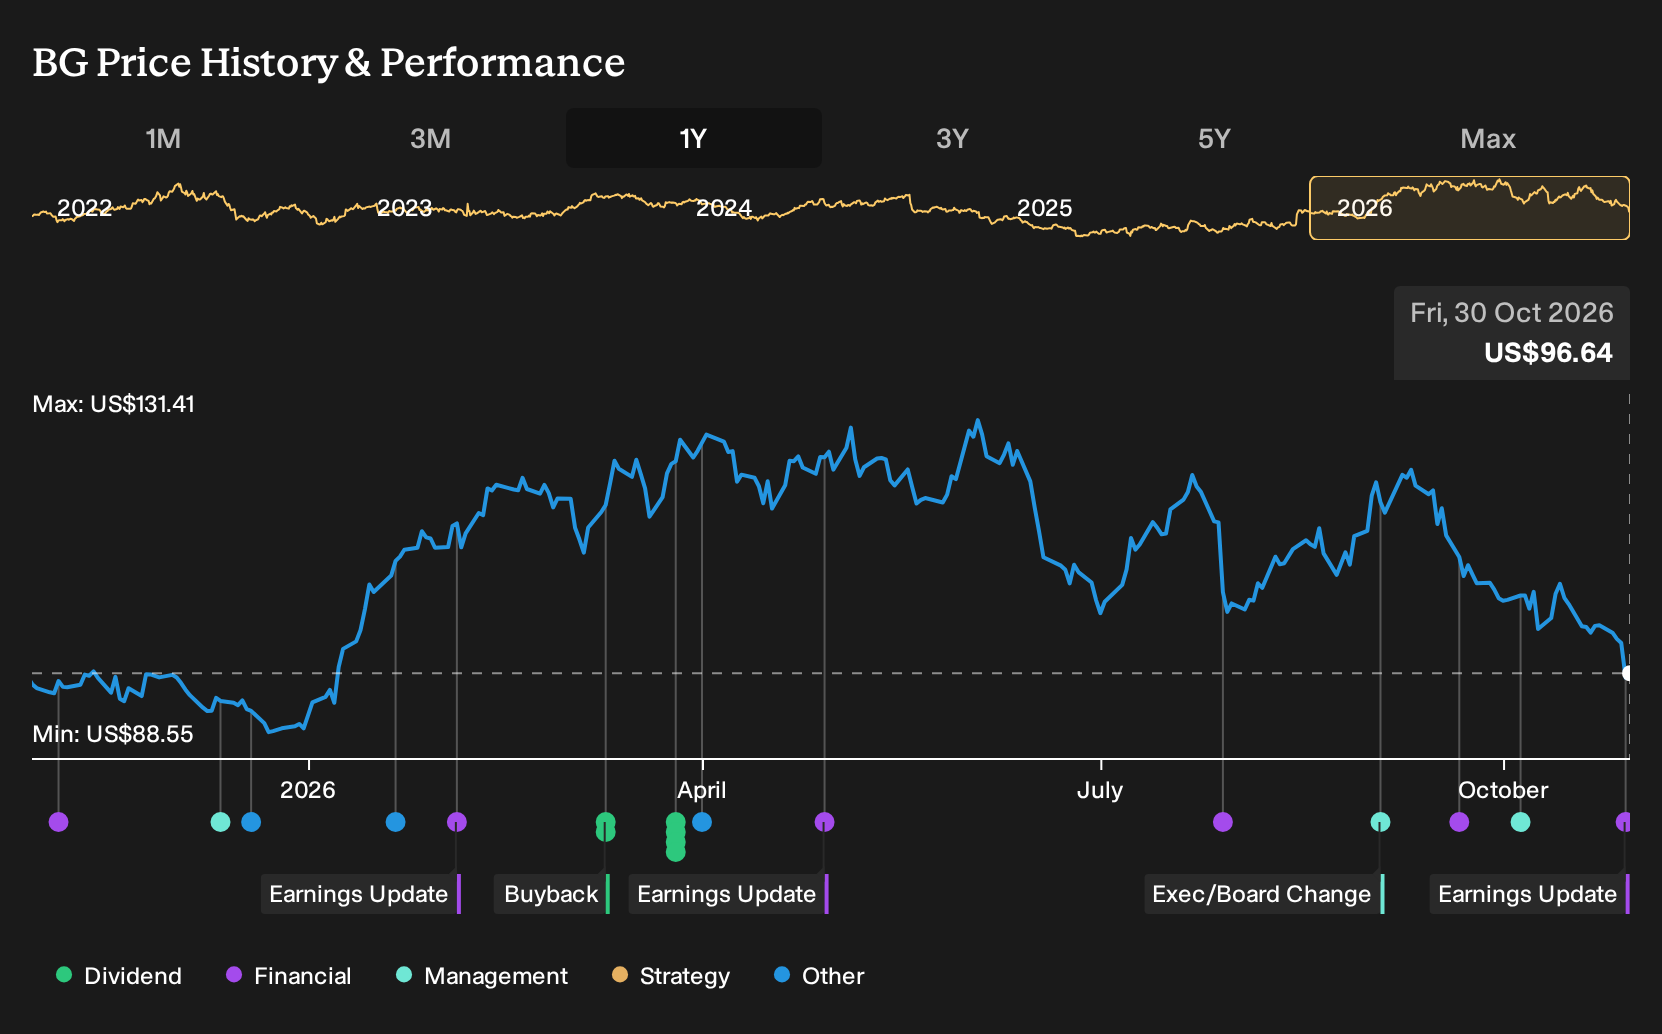
Exploring Other Perspectives
For Bunge Global, the alternate story hangs on biofuel policy risk. The most cautious analysts were assuming revenue trends of about a 1.6% yearly decline and earnings of US$2.8b by 2029 before this quarter's update, which is far more pessimistic. Use this latest earnings news to reassess where your own view lands between those extremes.
Explore 3 other Bunge Global fair value estimates, including one that suggests it could be worth just $140.38!
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider forming your own view.
- A great starting point for your Bunge Global research is our analysis highlighting 4 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Bunge Global. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easier to evaluate Bunge Global's overall financial health at a glance.
Looking for more investment ideas beyond Bunge Global?
If the Bunge Global story has sharpened your thinking about risk, balance sheets and earnings quality, use that same lens to scan a wider opportunity set with the Simply Wall St Screener.
- For investors who want quality at a discount, start with 33 high quality undervalued stocks that combine strong fundamentals with prices that analysts consider attractive relative to earnings power.
- If steady compounds appeal to you, focus on income resilience by reviewing 5 dividend fortresses that pair higher yields with robust financial profiles.
- For a different twist on quality, narrow in on resilience and capital strength through a 29 resilient stocks with low risk scores designed to highlight companies with more durable balance sheets and lower overall risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com