
Our Pick Of The Best Canadian Value Stocks In November 2026
Heavy selling in global tech stocks after weaker earnings has pushed many Canadian companies further out of favour, even when their cash generation looks solid on paper. That gap between mood and maths is where mispricing can appear. This article focuses on Canadian businesses that generate healthy cash flows yet trade below estimated fair value. You will see three such stocks from our screener that may merit a closer look.
The three stocks below are just a sample, with the full screen surfacing 2 more cash flow focused businesses with equally compelling stories that are not covered here.
If you want to quickly identify and analyze a wider set of value ideas built on discounted cash flow signals, head straight to the Undervalued Stocks Based On Cash Flows screener.
Stantec (TSX:STN)
Overview: Stantec is a global design and consulting firm that helps governments and businesses plan and deliver infrastructure, especially sustainable water and wastewater systems that generate steady project fees.
Operations: Stantec earns about CA$3.6b from the United States, CA$1.7b from Global operations, and CA$1.6b from Canada, with additional geographic reporting showing CA$4.7b from the U.S., CA$1.8b from Canada, and CA$2.0b across Australia, the U.K., and other regions.
Market Cap: CA$11.3b
Stantec matters for this cash flow focused screen because its long term infrastructure and water projects often come with multiyear fee streams that can be valued quite cleanly.
"Demand for infrastructure upgrades, water and wastewater treatment, energy transition and climate adaptation projects remains very strong globally. This is reflected in double digit organic growth in Water across multiple regions and a record contract backlog of about $9.2b, which points to an extended runway for net revenue and earnings growth as multiyear projects are executed."
What you really need to watch now is how a single pressure on future profitability shapes the payoff from that growing backlog.
That pressure point is exactly what the full narrative for Stantec tackles, highlighting where backlog strength could be masking margin risk or accelerating future cash generation.

Torex Gold Resources (TSX:TXG)
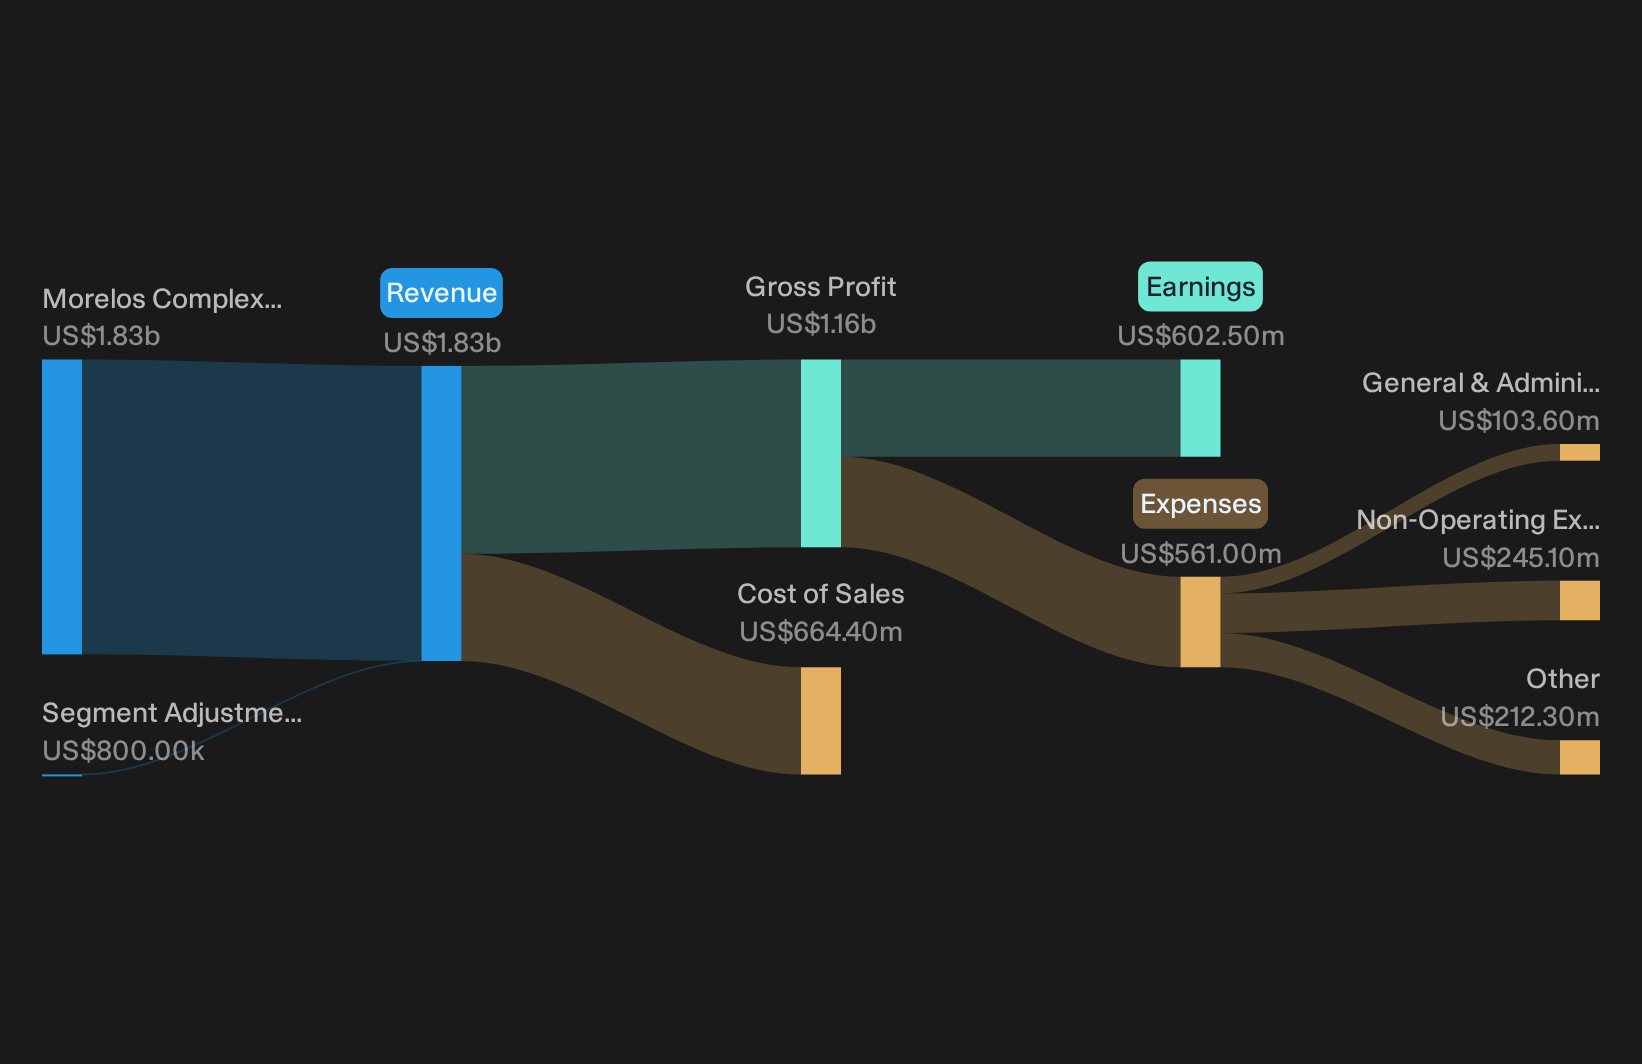
Overview: Torex Gold Resources is a Toronto based miner whose 100% owned Morelos Complex in Mexico generates gold focused cash flows for metals buyers.
Operations: Torex Gold Resources generates about $1.8b in revenue from the Morelos Complex, with virtually all sales tied to production in Mexico.
Market Cap: CA$5.9b
For a cash flow oriented screen, Torex Gold Resources matters because the Morelos Complex already throws off hard gold revenue today while giving investors a direct line of sight to potential future output from ongoing expansion work.
"Successful completion and ramp-up of the Media Luna project, now supported by underground mining rates ahead of plan at Media Luna and ELG and on-schedule progress toward first ore at Media Luna North by late 2026, is set to materially increase production volumes and extend mine life, supporting long-term revenue growth and cash flow stability."
What could really reshape the Torex Gold Resources story is how one stubborn cost pressure interacts with that expanding production base and projected cash generation.
That cost pressure is exactly where the full narrative for Torex Gold Resources pulls the story apart, showing how Torex Gold Resources’ cash engine could either accelerate or stall from here.
Canadian Natural Resources (TSX:CNQ)
Overview: Canadian Natural Resources produces and sells crude oil, natural gas and NGLs from long life upstream assets across Western Canada, the U.K. North Sea and Offshore Africa, which drive the cash flows behind its DCF based undervaluation.
Operations: Canadian Natural Resources generates about CA$21.3b from North American exploration and production, CA$20.8b from oil sands mining and upgrading, with smaller midstream and international contributions.
Market Cap: CA$161.7b
Canadian Natural Resources matters for this Undervalued Stocks Based On Cash Flows screen because its long life upstream production generates sizable cash that directly underpins the DCF work suggesting a discount to fair value.
"The large inventory of long-life, low- or zero-decline oil sands reserves, including mining and synthetic crude oil assets with multi decade reserve life indices, provides scope for Canadian Natural Resources to sustain production levels and associated revenue over an extended period if current operating performance is maintained."
The key factor now is how one unresolved cost and policy pressure ultimately feeds through to margins and future cash returns.
That unresolved pressure is exactly where the full narrative for Canadian Natural Resources steps in, showing whether those long life assets are masking margin strain or setting up accelerating future cash returns.

Seeking Alternatives Before The Crowd?
Fresh ideas move first, and slow money often gets caught chasing momentum after prices are already flying. Scan new themes while it matters and get in early.
- Spot income opportunities that aim to ride through market swings by reviewing a curated group of resilient payers in the 3 dividend fortresses.
- Track where robotics demand could build long term momentum by scanning the carefully filtered companies inside the 95 robotics and automation stocks.
- Follow the picks tied to potential AI build out waves by reviewing the screened infrastructure enablers in the 54 AI infrastructure stocks.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com