
DSV (CPSE:DSV) Narrows EBIT View After Earnings As Fair Value Debate Builds
What DSV’s earnings, buyback, and guidance update tell you
DSV (CPSE:DSV) just packed a lot into one day, combining fresh third quarter results, a narrowed 2026 EBIT outlook, and the launch of a multi year share repurchase plan.
The freight and logistics group reported detailed revenue and profit figures for both the quarter and the first nine months of 2026, while also tightening its earnings range for the full year and confirming expected gains from ongoing property disposals.
The latest results, the tighter 2026 EBIT range and the fresh buyback program arrive after a sharp shift in sentiment. DSV’s share price has returned 17.35% over the past month but is still down 12.06% year to date, while the 3-year total shareholder return of 31.98% signals that longer-term holders have seen steadier progress.
Scan how DSV’s capital return move compares by lining it up against other buyback heavyweights in our curated list of 197 high quality undervalued stocks.
The rebound in DSV after a weak year to date and a fresh buyback plan leaves an important question for you: Is meaningful upside still in front of the stock, or did most of it already arrive over the past month?
Most Popular Narrative: 22% Undervalued
Against DSV’s last close at DKK1,407, the most followed narrative points to a fair value of DKK1,812.95, which implies a wide gap that hinges on successful integration and margin recovery rather than just short term sentiment.
The ongoing large scale integration of Schenker is expected to drive further synergy realisation, with roughly 45% of the planned DKK 9b already in the run rate and management guiding to complete integration by the end of 2026 and reach the full synergy level in 2027, which directly targets higher EBIT and EPS.
DSV is rolling out a central data platform and AI use cases together with new transport management systems such as Tango and STAR, with management quantifying around DKK 6b of additional productivity gains and roughly DKK 3b of network optimisation benefits by 2030, which is aimed at lifting conversion ratios and net margins.
See why 44 investors see DSV as 22% undervalued.
Result: Fair Value of DKK1,812.95 (UNDERVALUED)
Still, if DSV’s Road integration issues persist, or if working capital and property sale timing keep free cash conversion subdued, that upbeat undervaluation story comes under pressure.
Find out about the key risks to this DSV narrative.
Another View on DSV’s Valuation
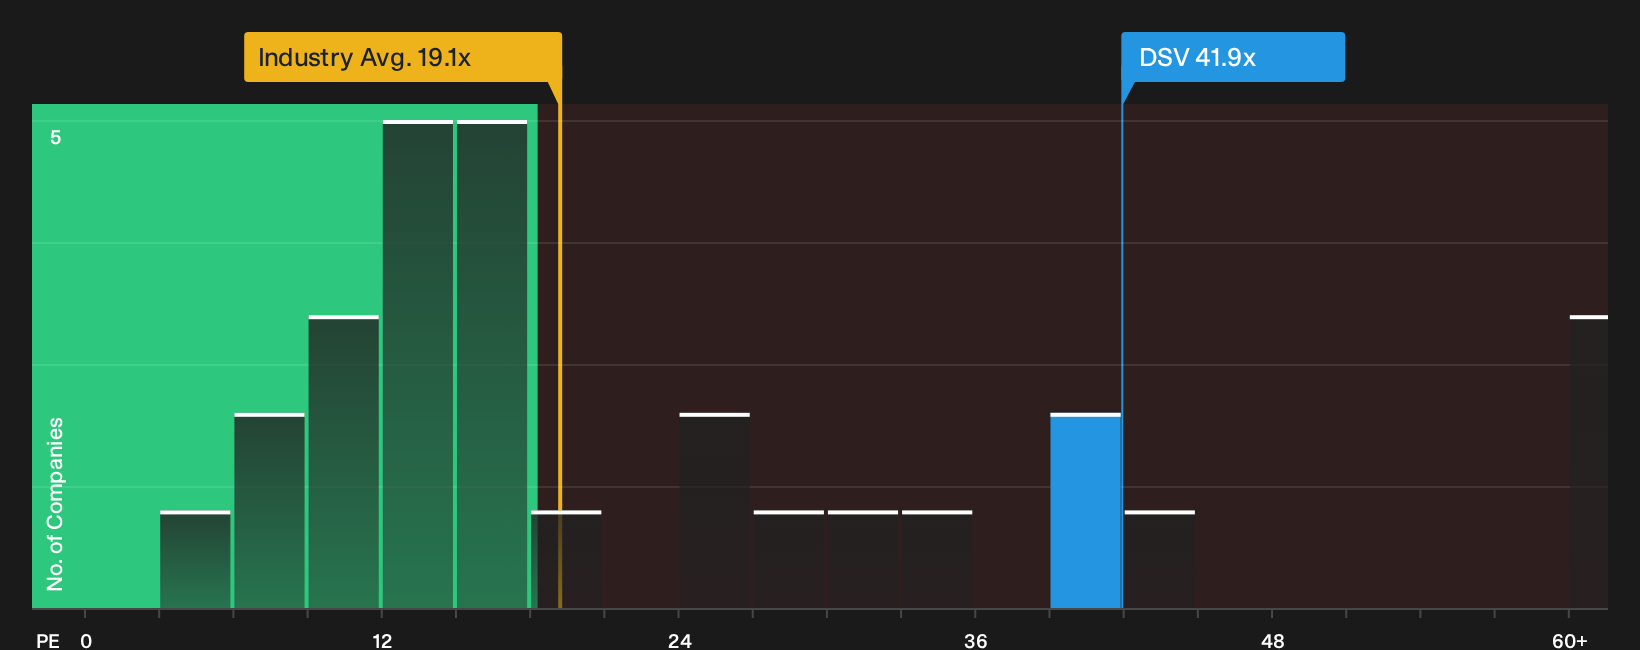
The DSV fair value narrative leans heavily on future cash generation. A different lens looks at today’s P/E. The stock trades on 41.9x earnings, which is much higher than both the European logistics group on 19.1x and its peer average on 21.9x.
Yet the estimated fair ratio sits even higher at 48.9x, which suggests the market could still move toward a richer earnings multiple if the story plays out as planned. With such a wide spread between current, industry and fair ratios, how comfortable are you with the valuation risk baked into DSV today?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If this DSV story feels finely balanced between promise and risk, consider acting while the data is fresh and pressure test it yourself against our breakdown of 3 key rewards and 3 important warning signs
Looking for more investment ideas beyond DSV?
Do not stop at one opportunity. Cast the net wider and give yourself more ways to win by lining up DSV against other clear, data driven ideas.
- Target income first and stress test your yield expectations against 225 dividend fortresses built around higher payout opportunities.
- Hunt for resilient balance sheets and compare DSV to companies in our list of solid balance sheet and fundamentals (198 results) that can better withstand shocks.
- Spot potential opportunities early by scanning the 611 high quality undiscovered gems that the wider market may not be watching yet.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com