
Is Stewart Information Services (STC) Undervalued Following Mixed Third Quarter Earnings?
What Stewart Information Services’ Latest Earnings Tell You
Stewart Information Services (STC) set the tone for recent trading after third quarter 2026 results showed higher revenue alongside softer quarterly profit, giving investors fresh data on how the title insurer is handling cost pressures.
That mix of stronger top line and softer quarterly profit has landed on a weak price trend. Stewart Information Services’ share price has fallen about 37% year to date, with the 1 year total shareholder return down roughly 33%. This suggests recent earnings have reinforced concerns about cost pressure and profitability rather than reigniting momentum.
Compare how Stewart Information Services stacks up on profitability and balance sheet strength against a hand picked list of solid balance sheet and fundamentals (24 results) as this earnings season shakes out winners and laggards.
Stewart Information Services now trades well below the average analyst price target, yet the share slide reflects real concern about earnings quality. Is that discount compensation for risk, or an overreaction you are being paid to accept?
Most Popular Narrative: 42% Undervalued
Against the last close of $44.50, the most followed narrative pegs Stewart Information Services’ fair value at $76.25, putting today’s depressed share price in sharp contrast with a more optimistic long term model built on growth, margins and capital returns.
Use of excess capital and an upsized credit facility, together with a rising dividend that reached US$2.20 per share in 2026 with a payout ratio around 39%, gives Stewart Information Services flexibility to keep funding acquisitions and shareholder returns in ways that may support earnings per share and total capital return over time.
See why 2 investors see Stewart Information Services as 42% undervalued.
Result: Fair Value of $76.25 (UNDERVALUED)
Still, this story can break if higher operating expenses squeeze margins further, or if weak existing home sales keep Stewart Information Services’ residential volumes under pressure.
Find out about the key risks to this Stewart Information Services narrative.
Another View on Stewart Information Services’ Value
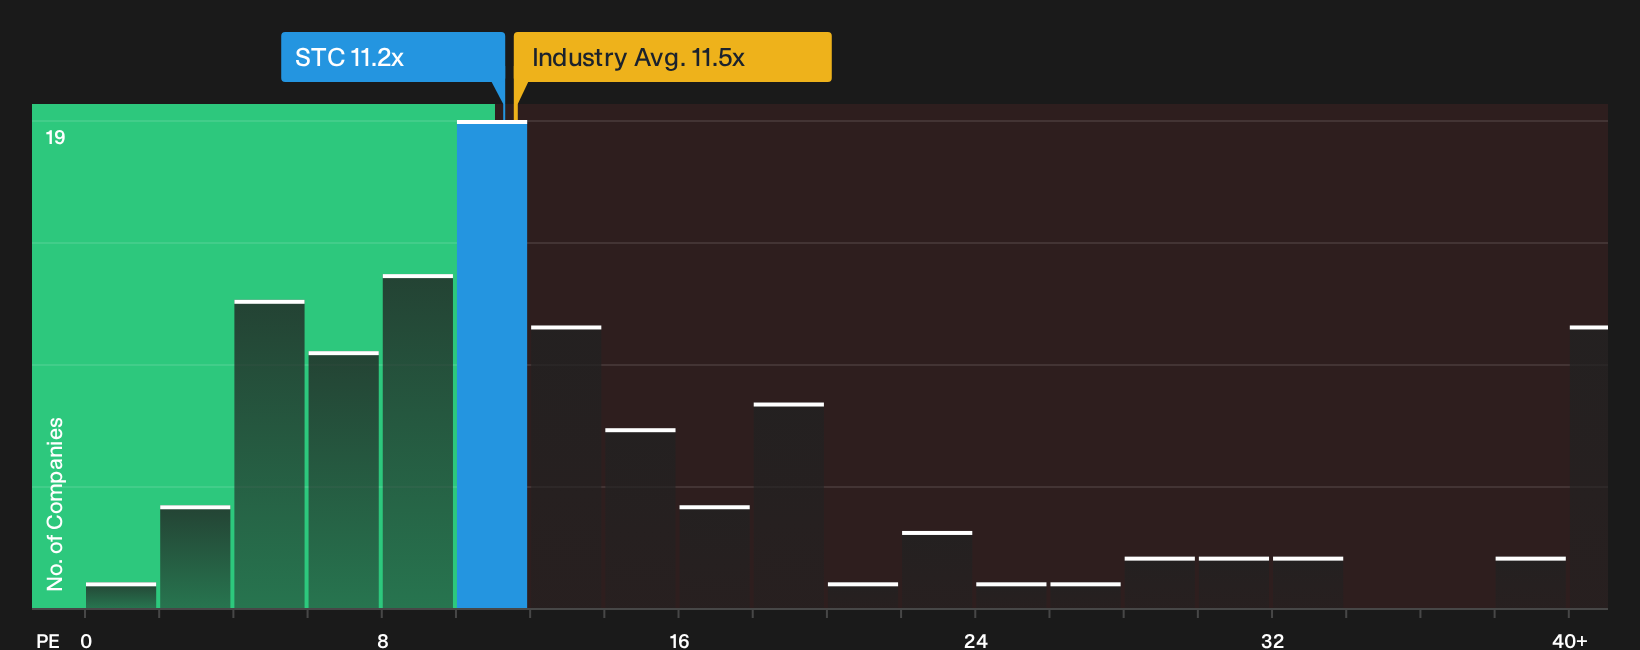
A second lens on Stewart Information Services comes from its P/E ratio. The stock trades at 11.2x earnings, slightly below the US Insurance industry on 11.5x and under its own fair ratio of 11.7x. That discount may indicate mispricing, but it also highlights the risk that expectations could reset.
To see how this earnings based view compares with a fuller breakdown of the valuation drivers, take a closer look at the See what the numbers say about this price — find out in our valuation breakdown.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Stewart Information Services for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 33 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals or a clear message, Stewart Information Services only makes sense once you stress test the numbers yourself and decide what actually matters. To see which potential upsides others are watching, review the 5 key rewards
Looking For More Investment Ideas Beyond Stewart Information Services?
If you stop with Stewart Information Services, you miss chances elsewhere. Use the Simply Wall St screener to spot other opportunities that fit your risk and income goals.
- Target steadier potential with companies that show resilient balance sheets and solid fundamentals through the 29 resilient stocks with low risk scores.
- Hunt for mispriced opportunities where quality and valuation meet by scanning the 19 high quality undiscovered gems.
- Stack income ideas by zeroing in on companies serious about shareholder payouts using the 5 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com