
Armstrong World Industries (AWI) Could Be 17% Undervalued Following Earnings Guidance And Dividend Raise
Armstrong World Industries (AWI) just packed a lot into one week, pairing third quarter earnings growth with fresh full year guidance and a 10% bump to its quarterly dividend.
In share price terms, Armstrong World Industries has given up ground this year, with the year to date share price return down 15.5% and the 90 day share price return also in decline. However, the 3 year total shareholder return of 110.83% points to a still strong longer term story that recent earnings, guidance and the dividend increase are now being measured against.
Scan how Armstrong World Industries fits into the wider opportunity set and see which other companies show similar earnings and dividend momentum in our curated 33 high quality undervalued stocks.
Armstrong World Industries just delivered growth, guidance and a richer dividend. The business looks solid. The real tension sits in the price. Do today’s numbers justify paying this much for AWI?
Most Popular Narrative: 17% Undervalued
Armstrong World Industries last closed at $166.34, while the most followed narrative pegs fair value closer to $200.55. As a result, the valuation debate now hinges on whether the growth levers in ceilings, grids and Architectural Specialties actually deliver.
The build out of Architectural Specialties through acquisitions and integration of platforms like Eventscape, which is expected to be a positive contributor in 2026 and to pull through more Armstrong solutions on complex projects, is widening the project scope the company can serve and supports higher net sales and segment EBITDA margins over time.
See why 2 investors see Armstrong World Industries as 17% undervalued.
Result: Fair Value of $200.55 (UNDERVALUED)
Still, the story around Armstrong World Industries can change quickly if commercial construction stays soft or if Architectural Specialties stumbles again on project execution and margins.
Find out about the key risks to this Armstrong World Industries narrative.
Another View: Cash Flows Tell A Tighter Story
Analyst narratives around Armstrong World Industries focus on a fair value of about $200.55, yet the SWS DCF model comes in lower, with AWI trading slightly above an estimated future cash flow value of $164.62. That points to less obvious upside and a greater need for precision in expectations.
Before leaning on any single method, it helps to see how this cash flow view is built and what would need to change for AWI to appear clearly cheap again. Look into how the SWS DCF model arrives at its fair value.
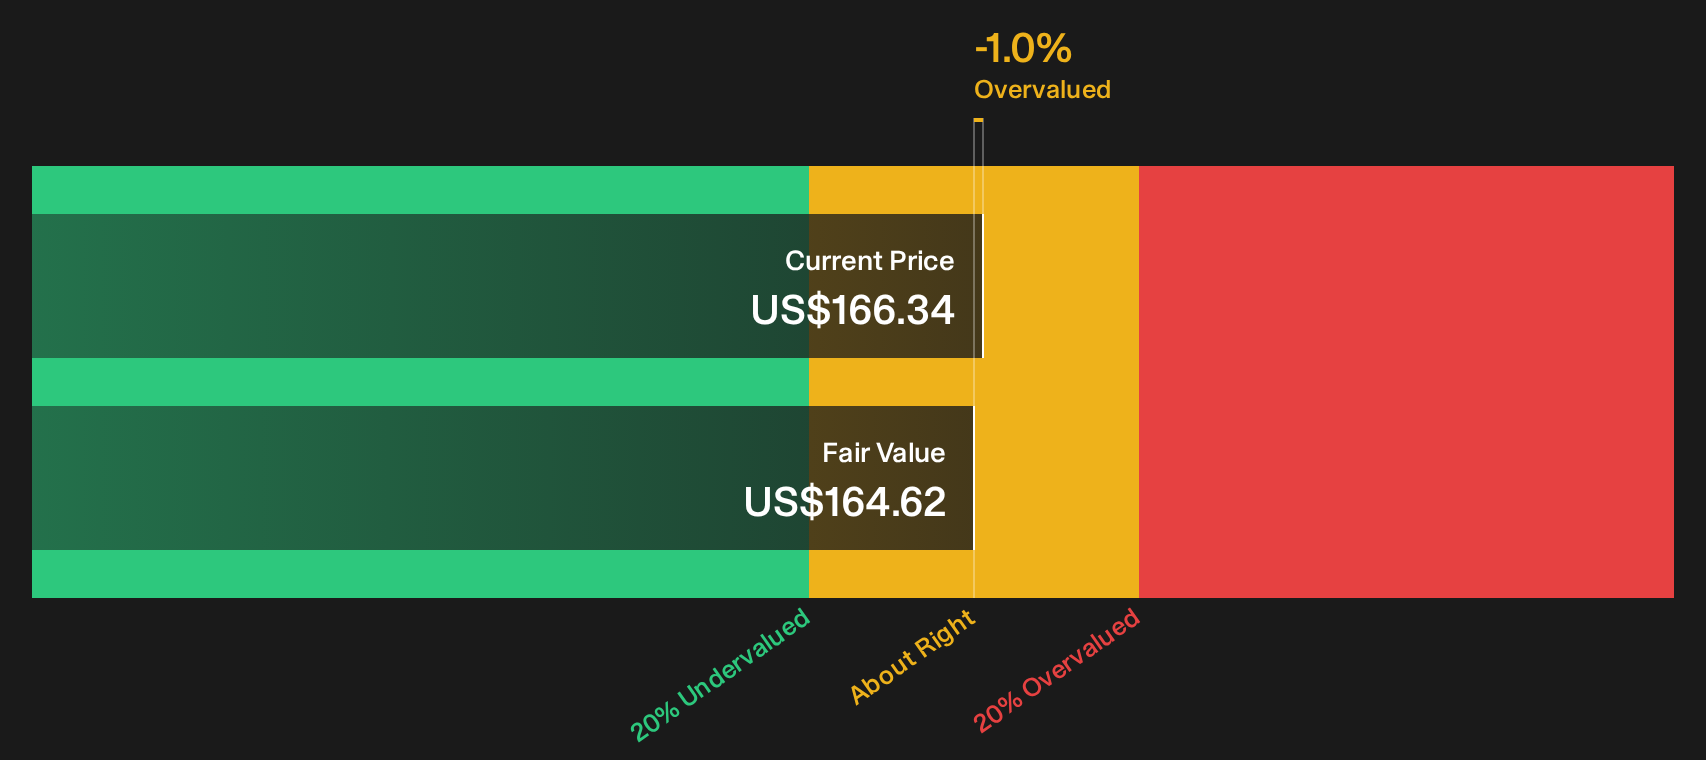
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Armstrong World Industries for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 33 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed feelings on Armstrong World Industries after this week’s updates. Move quickly to check the full picture yourself, including the 3 key rewards and 1 important warning sign
Looking for more investment ideas beyond Armstrong World Industries?
If Armstrong World Industries has your attention, do not stop here. Use the Simply Wall St screener to quickly surface fresh ideas before the crowd does.
- Spot potential bargains early by scanning a curated 19 high quality undiscovered gems that focuses on quality businesses still flying under most investors' radar.
- Strengthen your core holdings with a list of solid balance sheet and fundamentals (24 results) that focuses on companies built on healthier financial foundations.
- Reduce portfolio stress by filtering for a 29 resilient stocks with low risk scores that highlights resilient businesses with lower risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com