
How Strong Q3 Earnings Will Impact KeyCorp (KEY) Stock
- KeyCorp reported third quarter 2026 results with net interest income of US$1,300 million and net income of US$579 million, alongside a completed US$1b fixed to floating senior note offering due 2032 and continued share repurchases under its existing buyback plan.
- The bank is tightening full year 2026 net interest income growth guidance to about 10%, and is relying on preferred capital optimization, lower preferred dividends, and net loan charge offs of US$89 million to fine tune its earnings mix and capital structure.
- We will look at how KeyCorp's investment narrative is influenced by the stronger third quarter earnings profile and refined income guidance.
Scan how KeyCorp’s funding moves compare with peers by reviewing a curated set of banks and lenders in the list of solid balance sheet and fundamentals (24 results).
KeyCorp Investment Narrative Recap
To own KeyCorp, you need to be comfortable with a story that leans on net interest income, deposit mix and fee businesses all pulling their weight together. The tightened full year 2026 NII growth outlook of about 10% and a stronger third quarter earnings profile keep that thesis intact rather than transforming it.
The near term swing factor is still whether asset quality and funding costs stay contained while fixed rate assets reprice. Net loan charge offs of US$89 million and lower preferred dividends help earnings today, but any renewed pressure from nonperforming loans or weaker fee activity would quickly become the main risk.
The fresh US$1b fixed to floating senior notes due 2032 sit right in the middle of this earnings and risk balance. Longer term unsecured funding at variable rates interacts directly with KeyCorp’s effort to manage deposit costs, support commercial loan growth and keep net interest margin aligned with its refined guidance.
For you as a shareholder, that bond issue links to the same catalysts as the buyback and preferred capital moves. Stronger net interest income, higher quality earnings and capital returns all rely on execution in areas like credit discipline and fee growth, so any setback in those building blocks would matter more than this single funding action.
KeyCorp Analyst Assumptions and Valuation Anchors
Analysts looking at KeyCorp are working off a fairly specific playbook. They are building their models around earnings moving from US$1.9b today to US$2.5b by 2029, with profit margins edging up from 25.6% to 26.6% over roughly the same period. That path assumes the bank delivers on both net interest income and fees while continuing to buy back stock and retire preferreds.
Revenue expectations sit on an 8.9% yearly growth rate over the next three years, which is a punchy top line assumption for a large regional bank. Those forecasts tie directly into the consensus view that by 2029 KeyCorp can reach about US$9.5b of revenue and still convert a slightly higher share of that into profit. For you, the question is whether that pace of expansion looks realistic when set against what you know about its balance sheet, loan appetite and fee engines.
The earnings bridge from today to the analyst endpoint is equally important. Moving from US$1.9b of earnings to US$2.5b implies an increase of about US$0.6b, supported by both margin improvement and lower share count as outstanding shares are expected to decline by roughly 2.36% a year. That combination means a lot of the heavy lifting in the forecasts is coming from execution on efficiency and capital returns as much as from pure revenue growth.
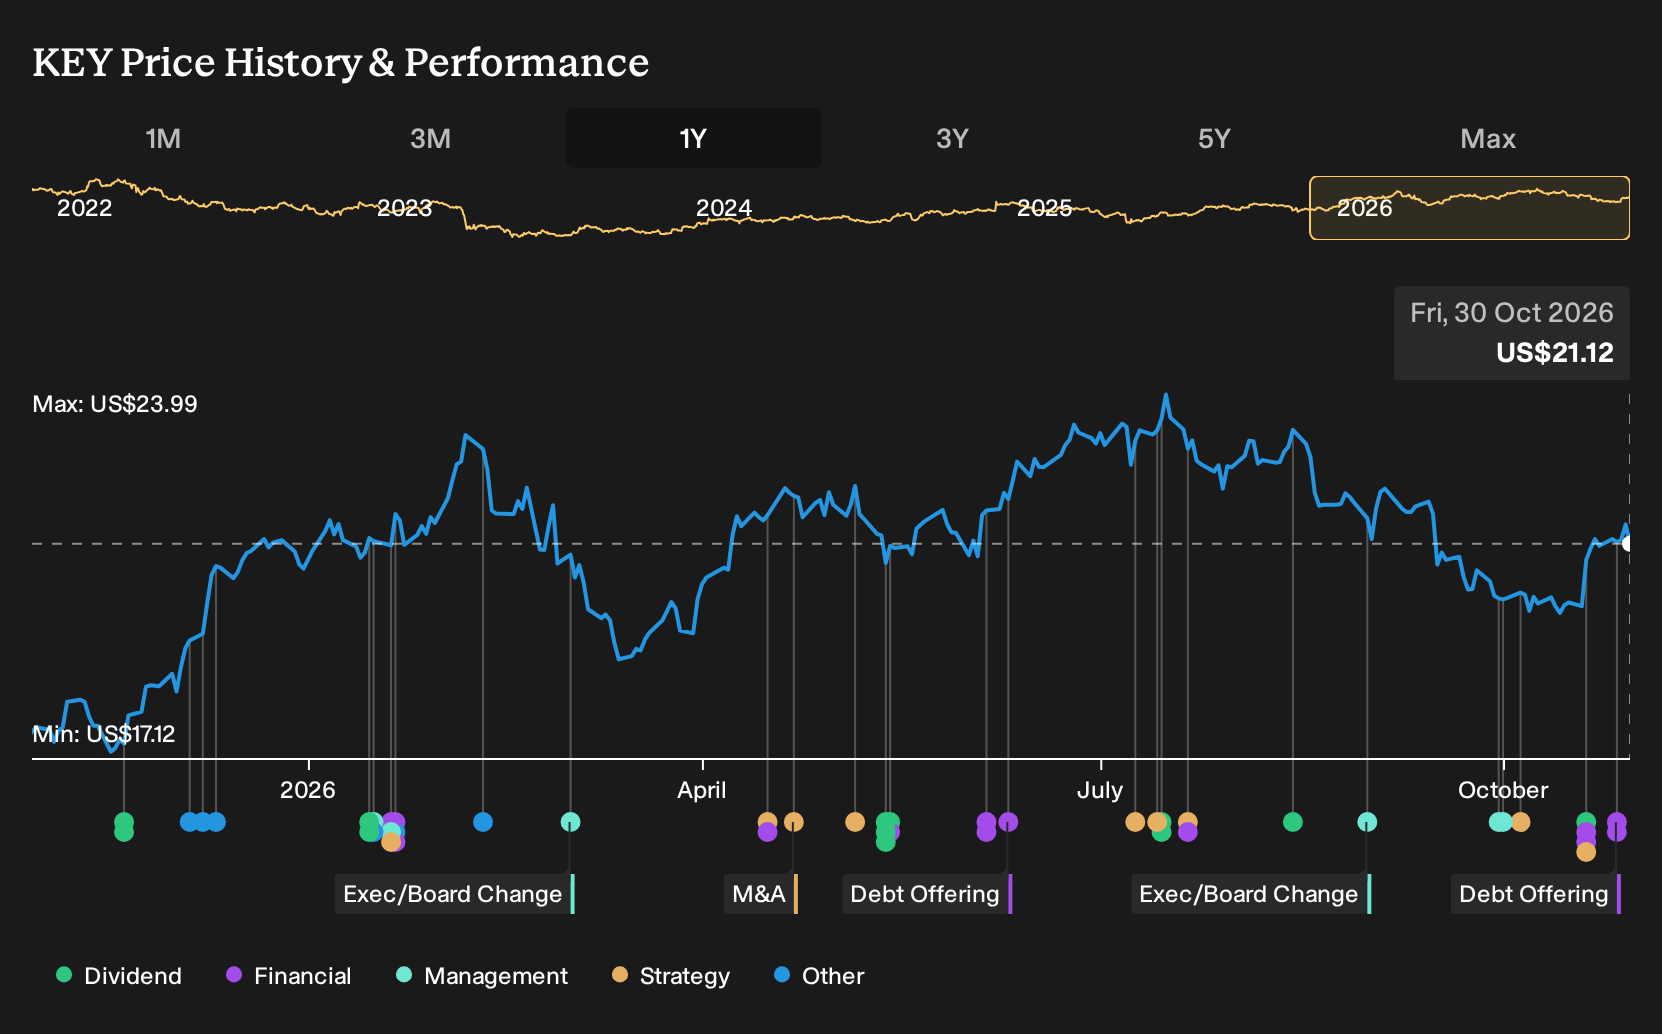
Valuation work in the consensus numbers leans on KeyCorp eventually trading at a P/E of about 12.3x on those 2029 earnings, compared with about 11.4x today and a current US Banks sector level of roughly 11.5x. The implied fair value math then points to a price target of US$25.37 per share versus a current price of US$20.18, with a wide range of analyst views from US$22.00 at the low end to US$43.00 at the top. That spread shows how sensitive the outcome could be to small changes in margin, growth or investor appetite for bank stocks.
None of these figures are destiny for KeyCorp; they are just the scaffolding around the current debate. Treat the consensus assumptions as a starting grid. Then pressure test whether 8.9% annual revenue growth, gently rising profitability and a slightly richer future P/E all line up with your own reading of its funding mix, credit cycle exposure and ability to keep fee income humming.
KeyCorp's narrative projects US$9.5b revenue and US$2.5b earnings by 2029. This assumes 8.9% yearly revenue growth and about US$0.6b earnings increase from US$1.9b today.
Uncover how KeyCorp's fair value indicates a 20% potential upside to its current price. This opportunity could narrow quickly if sentiment shifts back toward bank caution.
Exploring Other Perspectives
One bullish twist on KeyCorp focuses on credit rather than funding. The most optimistic analysts were already assuming US$9.8b of revenue and US$2.8b of earnings by 2029, helped by cleaner asset quality. You can now ask whether the new US$1b variable rate notes and lower preferred dividends push that credit friendly story even further, or prompt analysts to rethink it. Strong views can differ a lot, so explore several angles before deciding which version of KeyCorp’s future feels most convincing to you.
Explore 2 other KeyCorp fair value estimates, including one that suggests as much as 86% upside from the current price!
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your KeyCorp research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for KeyCorp. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate KeyCorp's overall financial health at a glance.
Looking For More Investment Ideas Beyond KeyCorp?
Once you have a view on KeyCorp, it can help to pressure test that thinking against other opportunities using the Simply Wall St Screener.
- If you want potential value with quality behind it, scan a curated set of 33 high quality undervalued stocks and see which businesses line up with your return and risk expectations.
- For income focused investing, assess which high yield payers look robust by reviewing a group of 5 dividend fortresses that combine stronger payouts with resilience.
- If capital preservation matters most to you right now, concentrate on a universe of 29 resilient stocks with low risk scores that aim to keep balance sheets and risk scores front and center.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com