
Fiduciary Probe Might Change The Case For Investing In STAAR Surgical Stock (STAA)
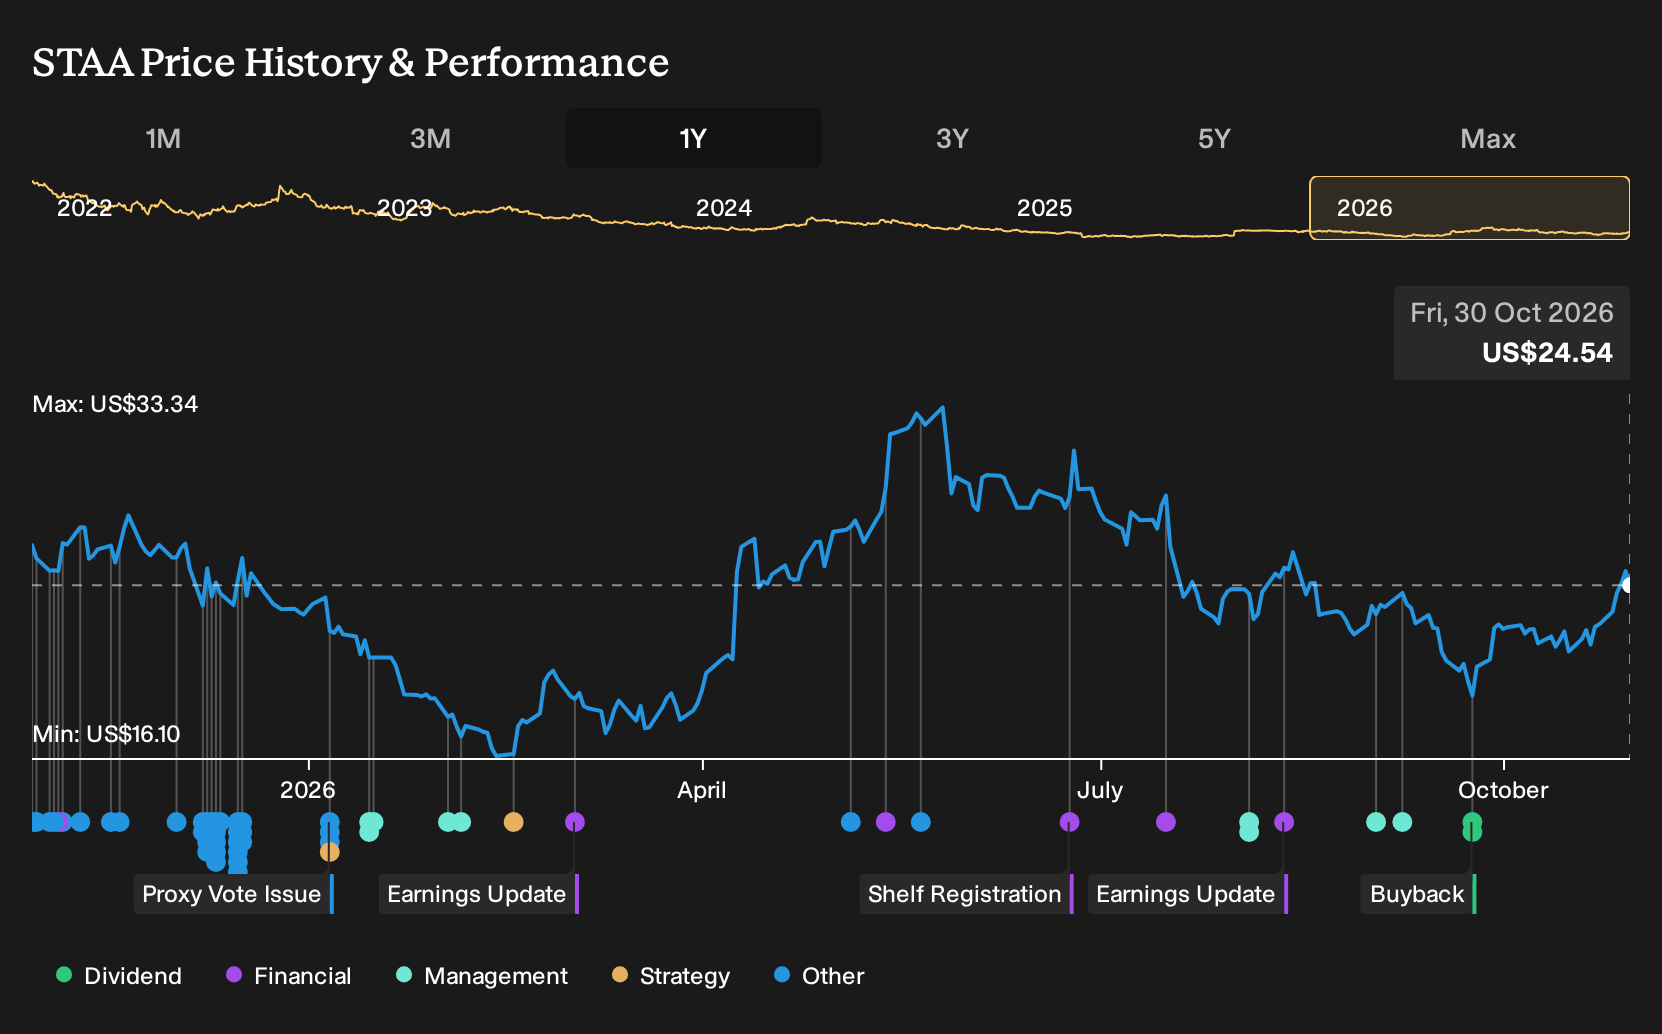
- STAAR Surgical is facing an investigation into potential fiduciary breaches by certain officers and directors, raising fresh questions about governance and oversight.
- The planned Nidau, Switzerland manufacturing site, intended to supply EVO and EVO+ lenses for China without tariffs by 2026, now sits under a brighter spotlight given these governance concerns.
- We will now look at how STAAR Surgical's investment narrative could be affected by the fiduciary investigation into its leadership.
Compare how the governance overhang at STAAR Surgical stacks up against other potential opportunities by scanning our hand picked list of 29 resilient stocks with low risk scores.
STAAR Surgical Investment Narrative Recap
To own STAAR Surgical, you need to believe that lens based refractive procedures keep gaining traction and that the firm can convert its presence in China and the underpenetrated US into steady procedure volumes and healthier margins. The fiduciary investigation hangs over that story but does not directly change demand for EVO and EVO+ lenses or day to day operations.
In the near term, the key swing factor is still execution in China and the Nidau manufacturing ramp. This initiative is intended to remove tariffs on lenses shipped to that market. The main operational risk remains softer procedures or a slower mix shift to premium products, which could leave revenue and earnings below what the current narrative implies.
The Nidau, Switzerland project is the operational announcement that ties most closely to the current governance questions. It is intended to eventually supply all EVO and EVO+ lenses shipped to China and to remove tariffs on those units. This matters for gross margin and cash generation once higher cost inventory is worked through.
For you as a shareholder, the lens plant is a clear execution test. Timelines, capital discipline and quality control around Nidau could influence how much benefit STAAR Surgical ultimately sees from its China exposure. Any distraction for leadership from the fiduciary investigation that affects this build out or regulatory approvals would be important to monitor as you weigh risk against that potential margin uplift.
What The Consensus Numbers Assume For STAAR Surgical
STAAR Surgical's narrative projects US$416.6 million in revenue and US$41.5 million in earnings by 2029. Analysts are building this on 7.0% yearly revenue growth and an earnings increase of about US$37.7 million from US$3.8 million today.
Uncover why STAAR Surgical's fair value indicates a 14% potential upside to its current price before the valuation gap starts to close.
Exploring Other Perspectives
One alternate view leans heavily on the Nidau plant as a catalyst. The most optimistic analysts were modelling about US$452.7 million of revenue and US$53.7 million of earnings by 2029, far above consensus, before any governance investigation headlines. Those expectations may now be reconsidered, so compare several viewpoints before deciding how you feel about STAAR Surgical.
Explore 2 other STAAR Surgical fair value estimates, including one that suggests up to 18% upside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider forming your own view.
- A great starting point for your STAAR Surgical research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for STAAR Surgical. This report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, which makes it easier to review STAAR Surgical's overall financial profile at a glance.
Looking For More Investment Ideas Beyond STAAR Surgical?
Once you have a view on STAAR Surgical, it can help to widen the frame and compare it against other businesses that fit different risk and quality profiles using the Simply Wall St Screener.
- If capital preservation is front of mind, start by scanning a curated 29 resilient stocks with low risk scores that may better align with a cautious approach.
- If balance sheet strength matters most to you, review a list of solid balance sheet and fundamentals (24 results) to see which businesses pair financial resilience with underlying fundamentals.
- If you prefer under the radar potential, cast a wider net across a 19 high quality undiscovered gems that might suit a more opportunistic style.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com