
Gun Ei Chemical Industry (TSE:4229) Q2 Earnings Sharpen Profit Growth Questions
Gun Ei Chemical Industry came into this Q2 2027 report with a stock that had quietly climbed 5.8% over the past week and 3.0% over the past month, pricing in a steady, quality earnings story. The actual headline was louder. Quarterly net income reached ¥867 million with basic earnings per share of ¥130.62, a powerful profit print for a specialist chemicals producer. That strength now has to be weighed against a market already paying a 12.6x P/E and questioning dividend cover, setting up a sharp expectation gap between a strong quarter and a cautious share price.
Love the strong Q2 earnings print from Gun Ei Chemical Industry but uneasy about the questions around dividend cover and valuation at a 12.6x P/E? Take a look at our screener of solid balance sheet specialists in the same zone with the list of solid balance sheet and fundamentals stocks (22 results).
Q2 2027 Earnings Summary
- Revenue (Q2 2027 vs. Q2 2026): ¥8,934 million vs. ¥7,841 million (up about 13.9%)
- Net Income (Q2 2027 vs. Q2 2026): ¥867 million vs. ¥510 million (up about 70.0%)
- Basic EPS (Q2 2027 vs. Q2 2026): ¥130.62 per share vs. ¥76.87 per share (up about 70.0%)
- Trailing 12M Net Profit Margin (Q2 2027 vs. Q2 2026): 6.8% vs. 6.2% (reported improvement in earnings quality over the year)
Gun Ei Chemical’s margins and EPS both stepped up this quarter. Ask Charlie what makes Gun Ei Chemical’s earnings look higher quality.
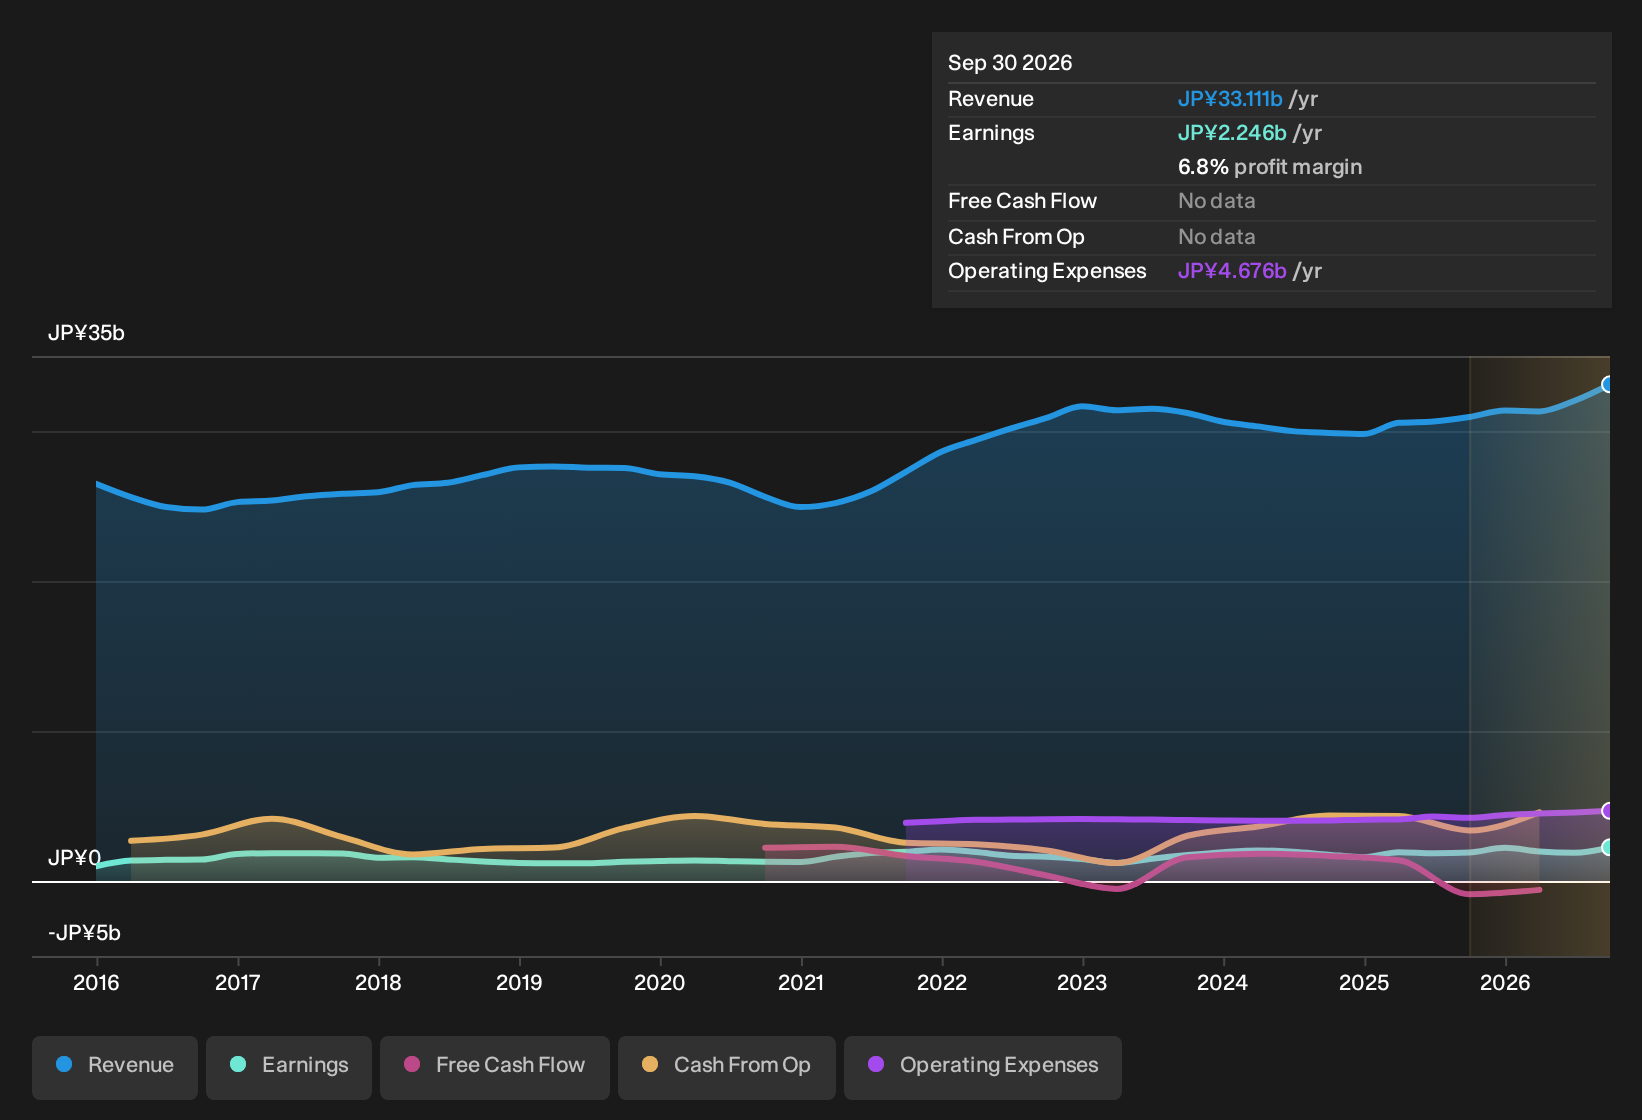
Gun Ei bullish story meets stronger earnings base
Gun Ei Chemical Industry looks closer to the mildly bullish narrative than it did a quarter ago. Revenue rose to ¥8,934 million and net income lifted to ¥867 million, so the business is converting a higher sales base into healthier profit. Basic EPS moving to ¥130.62 supports the idea of niche, value added chemicals that can support better earnings quality, reflected in the higher trailing 12 month margin. For a group framed as steady, these results show the specialty materials engine doing more of the heavy lifting.
Bearish concerns narrow but capital questions linger
Bears have argued that a diversified chemicals group like Gun Ei Chemical Industry might struggle to protect profitability. The step up in trailing 12 month net profit margin to 6.8% from 6.2% contrasts with that worry for now. Revenue and earnings both point in the same direction, which makes near term pressure on the core business model look less intense. The open questions sit more around how this stronger income line intersects with dividend cover and future capital allocation, areas that these figures do not fully answer yet.
Before assuming that higher earnings solve everything, it is worth asking if dividend strain is a symptom of deeper balance sheet pressure. Review the independent risk analysis for Gun Ei Chemical Industry which shows 1 important warning sign to scan for other structural weak spots already flagged by the data team.
Hunt For Balance Sheet Strength
Gun Ei Chemical Industry just showed how a cleaner earnings story can still leave capital questions hanging. The real opportunity is finding stocks that could be low debt before the market corrects them.
- Company 1 - 45% below our estimate - uses an AI focused security platform and subscription incentives to deepen recurring protection in customer workflows.
- Company 2 - 35% below our estimate - applies AI to match job seekers and service providers through paid listings and volume linked fees.
- Company 3 - 18% below our estimate - targets elevator maintenance contracts and then scales modernization work as denser regional coverage lifts productivity.
Three companies from the same screener. Open all 22 companies with the balance sheet to back it up →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com