
Mapletree Pan Asia Commercial Trust (SGX:N2IU) Earnings Keep Fair Value In Focus
Mapletree Pan Asia Commercial Trust (SGX:N2IU) just posted its second quarter and half year results, giving investors fresh numbers on rental income, earnings per unit and portfolio resilience across its Asian properties.
Against this earnings release, Mapletree Pan Asia Commercial Trust’s share price has slipped over recent months, with a 30-day share price return of -3.36% and a year-to-date share price return of -21.77% from the current SGD 1.15 level.
Compare how Mapletree Pan Asia Commercial Trust stacks up against other income-focused plays by scanning our hand picked 221 dividend fortresses that investors are watching after this earnings update.
Given Mapletree Pan Asia Commercial Trust’s weak share price over 2026 despite steady earnings per unit, the big call now is simple: Is most of the repricing already done, or does meaningful upside still sit ahead on valuation?
Most Popular Narrative: 20.5% Undervalued
On the most followed view, Mapletree Pan Asia Commercial Trust screens below an estimated fair value of SGD1.45, compared with the latest SGD1.15 close. This puts the current debate squarely on whether balance sheet repair and asset upgrades can keep pulling more weight than offshore pressure.
The main thing that has to go right is that the refocused Singapore portfolio and asset enhancement initiatives, especially at VivoCity and Festival Walk, continue to offset weak contributions from China and Japan and help stabilise group earnings.
The current valuation implies that the market is heavily discounting the benefits of deleveraging, fixed rate and FX hedging, and high return asset enhancements.
See why 21 investors see Mapletree Pan Asia Commercial Trust as 20% undervalued.
Result: Fair Value of SGD1.45 (UNDERVALUED)
Still, the thesis on Mapletree Pan Asia Commercial Trust can unravel quickly if Greater China and Japan experience deeper rent cuts, weaker occupancies or fresh valuation hits.
Find out about the key risks to this Mapletree Pan Asia Commercial Trust narrative.
Another View: What Multiples Say About Mapletree Pan Asia Commercial Trust
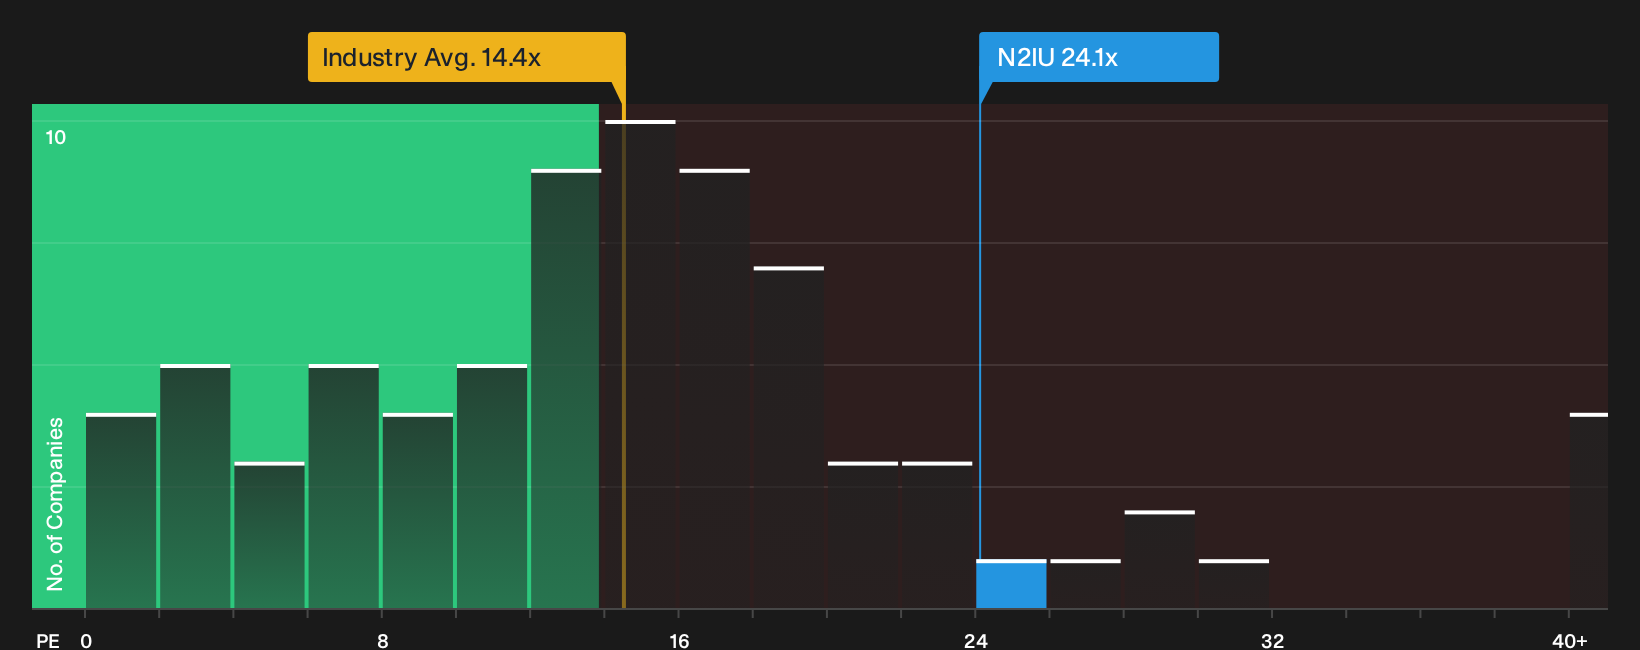
While the narrative points to Mapletree Pan Asia Commercial Trust trading below fair value, the current P/E of 24.1x tells a tougher story. It sits above both the Asian REITs industry at 14.4x and the peer group at 23.6x, and even exceeds a fair ratio of 17.2x.
That gap means you are paying a richer price multiple for a REIT with low current return on equity and an unstable dividend track record, which raises the risk that sentiment rather than fundamentals has to keep doing the heavy lifting from here. The question is whether you are comfortable with that trade off.
See what the numbers say about this price and find out in our valuation breakdown See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on value and risk often create the most interesting setups, so move quickly, review the full data in detail, then weigh up the 3 key rewards and 4 important warning signs.
Looking For More Ideas Beyond Mapletree Pan Asia Commercial Trust?
If you stop at Mapletree Pan Asia Commercial Trust, you risk missing other opportunities. Use the screener, compare a few angles, then decide where your next dollar works hardest.
- Target reliability first and check a curated 217 resilient stocks with low risk scores to help you focus on businesses with more resilient profiles.
- Hunt for mispriced quality and scan a focused 203 high quality undervalued stocks that filters for stronger fundamentals at prices that may not fully reflect them.
- Prioritise stability in your income mix and review a hand picked list of solid balance sheet and fundamentals (199 results) that highlights companies with sturdier financial footing.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com