
Learn Why The Bull Case For Extreme Networks Stock Could Change Following Strong Earnings Guidance
- Extreme Networks reported first quarter results for the period ended September 30, 2026, with revenue of US$341.09 million and net income of US$15.98 million, alongside guidance that outlines specific revenue, operating margin and earnings per share ranges for the second quarter and full fiscal year.
- The company also laid out an on prem enterprise AI roadmap through its planned Extreme Exchange zones, targeting customers that need tight control over data residency, latency and operational resilience by using existing access points and switches to run AI workloads locally.
- We will now examine how Extreme Networks' stronger profitability and detailed on prem AI roadmap could reshape the existing investment narrative.
Scan other network and AI infrastructure players showing similar momentum in enterprise workloads with our hand picked 54 AI infrastructure stocks as a comparison set to Extreme Networks.
Extreme Networks Investment Narrative Recap
To be comfortable owning Extreme Networks, you need to believe this is a networking vendor that can turn AI centric products and subscription models into steadier earnings while managing lumpier public sector demand. The latest quarter, which showed higher revenue and a larger profit than a year ago, supports the idea that the operating machine can produce more leverage when conditions are favorable.
The main factor in the near term is whether management can deliver within its new revenue and earnings per share guidance ranges while keeping operating margin inside the targeted band. The biggest risk is still concentration in government and other public verticals, where any slowdown in large deals could quickly pressure those margin ambitions.
The most relevant update for that thesis is the fresh full year outlook. This frames how Extreme Networks views its own execution capacity. Management guided total net revenue, operating margin and earnings per share ranges that, if met, would reflect a tighter handle on costs and demand visibility than in more volatile periods.
For you as a shareholder, the guidance becomes a practical scoreboard. Meeting those ranges would support the view that Extreme Networks can fund its AI heavy roadmap and newer commercial models from its own cash generation. Missing them, especially on operating margin, would revive questions about pricing pressure, deal lumpiness and the scalability of newer offerings.
Extreme Networks' current analyst blueprint points to revenue of US$1.7b and earnings of US$60.2 million by 2029. That path assumes 9.8% yearly revenue growth and an earnings increase of about US$18.1 million from US$42.1 million today.
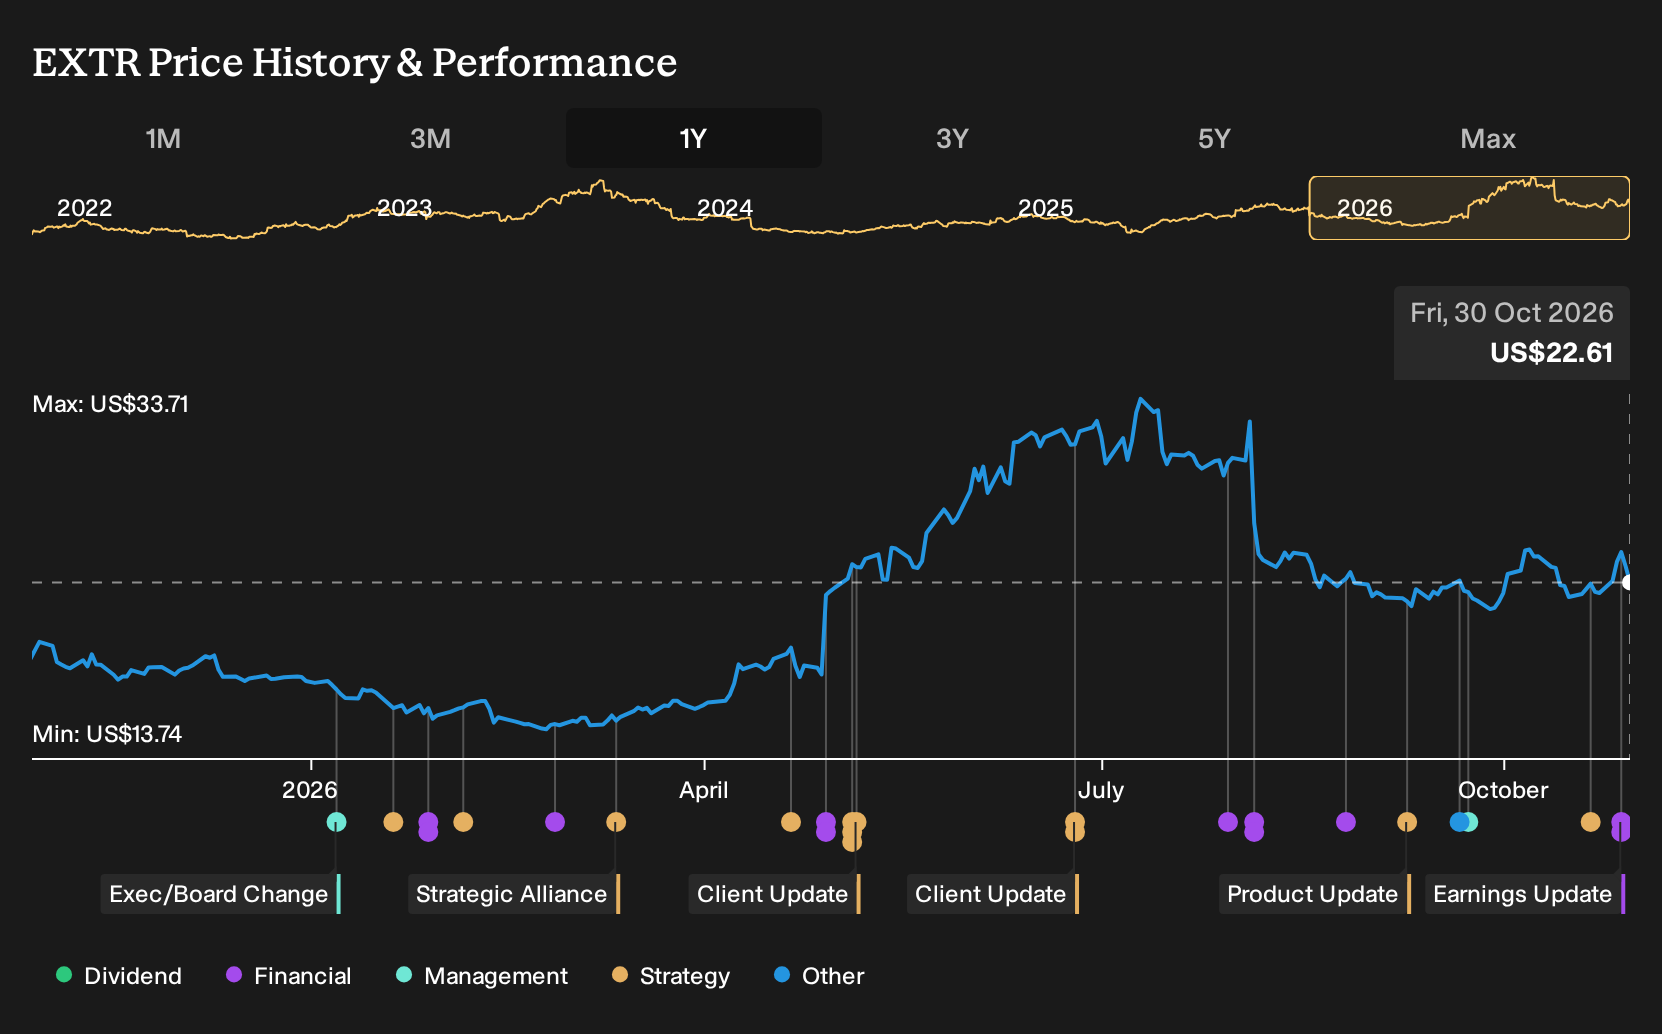
Uncover why Extreme Networks' fair value indicates a 48% potential upside to its current price before that discount to Extreme Networks closes further.
Exploring Other Perspectives
One alternate view focuses on Extreme Networks' sensitivity to big AI driven network refresh projects. The most pessimistic analysts were assuming about US$1.7b in revenue and US$61.2 million in earnings by 2029, yet still only saw a US$28.0 fair value. Those forecasts came before this quarter's AI roadmap and guidance, so opinions may evolve.
Explore 4 other Extreme Networks fair value estimates, including one that suggests as much as 22% downside from the current price.
Form Your Own Verdict
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Extreme Networks research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for Extreme Networks. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Extreme Networks' overall financial health at a glance.
Looking for more investment ideas beyond Extreme Networks?
If the Extreme Networks story has sharpened your thinking, use that momentum to build a broader watchlist. A focused screener can help you find other stocks with balance sheets, income profiles and risk levels that line up with your own playbook.
- If capital preservation and consistency sit high on your list, filter for sturdier businesses through a 29 resilient stocks with low risk scores that can help you spot candidates with calmer risk profiles.
- When you want quality at a sensible entry point, scan a curated 33 high quality undervalued stocks to see which companies combine stronger fundamentals with pricing that may not fully reflect them.
- For investors hunting for less crowded opportunities, tap into a 19 high quality undiscovered gems that highlights smaller, fundamentally sound stocks that are easier to overlook in the headlines.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com