
Is Cyber Contract Momentum Altering The Investment Case For Leidos Holdings (LDOS)?
- Leidos Holdings recently secured two sizable U.S. defense awards, including a US$99 million U.S. Cyber Command prototype platform and a US$95 million Defense Logistics Agency contract to apply AI automation to a long running Pentagon asset management system.
- These wins deepen Leidos Holdings' role inside core cyber operations and logistics infrastructure, reinforcing how integral its software, AI, and mission services are to day to day federal defense workflows.
- We will now look at how Leidos Holdings' investment narrative around defense technology and AI platforms connects to these fresh Pentagon contracts.
Scan how Leidos Holdings fits into the broader defense tech and AI story by comparing it with 41 profitable AI stocks that aren't just burning cash that are already turning algorithms into recurring cash flows.
Leidos Holdings Investment Narrative Recap
To own Leidos Holdings, you need to believe that long term U.S. spending on cyber, defense technology, and digital modernization stays supportive enough for its contract backlog to keep converting into steady work. The recent U.S. Cyber Command and Defense Logistics Agency wins reinforce that operating backdrop, although each contract is relatively small against a US$17.6b revenue base.
The near term swing factor is still execution on higher margin defense tech, AI platforms, and munitions programs, as well as maintaining Health & Civil profitability and preventing further erosion. A key risk remains reliance on U.S. federal budgets, so any shift in priorities or health contract terms could matter more than these individual awards.
The U.S. Cyber Command prototype platform is the announcement that aligns most clearly with the current news. A US$99 million award to build an integrated cyber mission planning environment fits directly into Leidos Holdings’ push into AI supported mission software, where performance and user adoption can influence future cyber related task orders.
For investors watching catalysts, this contract places more scrutiny on delivery discipline, integration of third party tools, and security accreditation timelines. Any delays, scope changes, or cost overruns would feed back into perceptions of risk on other complex programs, while smooth execution would support the wider AI and cyber operations narrative already built into expectations.
Leidos Holdings' narrative projects US$20.0b revenue and US$1.5b earnings by 2029. That framework assumes 4.4% yearly revenue growth and an earnings increase of about US$0.1b from US$1.4b today.
Uncover why Leidos Holdings' fair value indicates a 6% potential upside to its current price that could narrow quickly.
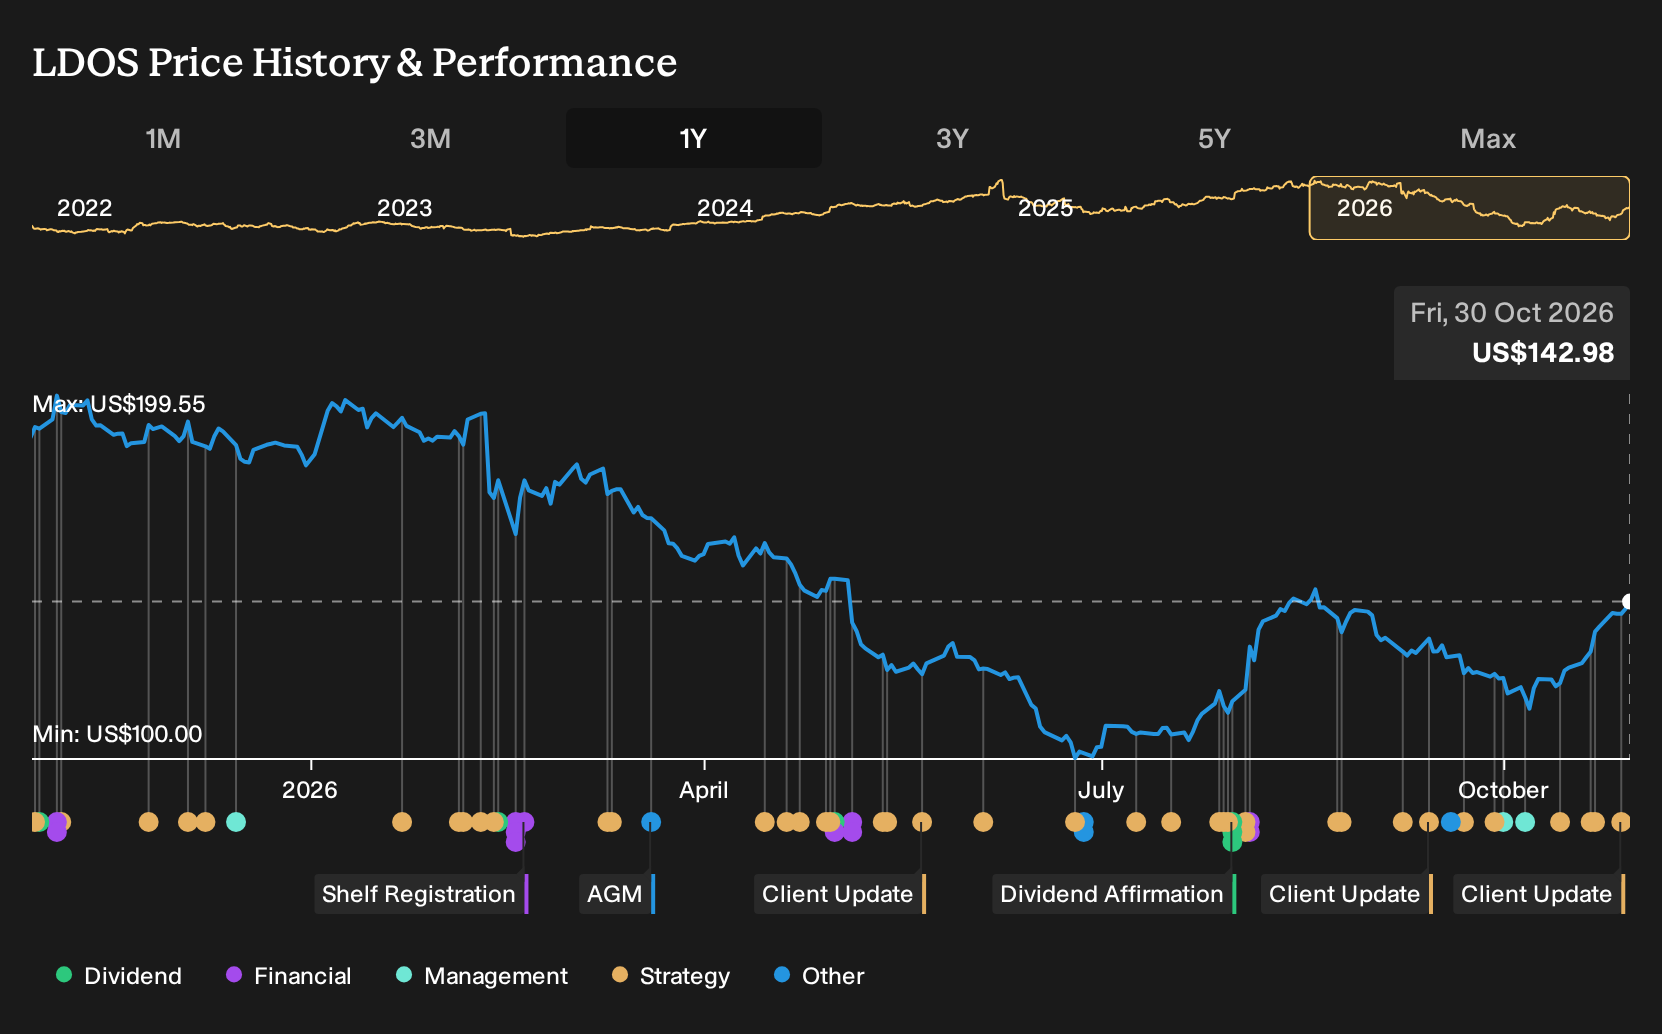
Exploring Other Perspectives
One alternate view focuses on AI execution risk. Some of the lowest Leidos Holdings analysts worry agencies could keep more AI work in house, which would blunt the impact of contracts like the new cyber platform award. Before this news, they were modeling revenue at about US$19.8b and earnings of roughly US$1.3b by 2029. That is a more cautious story than the consensus, so treat this contract news as a chance to compare both sets of expectations and decide which camp you think may adjust more from here.
Explore 2 other Leidos Holdings fair value estimates, including one that suggests it could be worth just $151.73.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider forming your own view.
- A great starting point for your Leidos Holdings research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Leidos Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Leidos Holdings' overall financial health at a glance.
Looking For More Ideas Beyond Leidos Holdings?
Once you have a handle on how Leidos Holdings fits your portfolio, it often helps to line it up against other opportunities that match different risk and return profiles. The Simply Wall St Screener lets you scan for stocks by quality, valuation, balance sheet strength, income potential, and more, so you can build a watchlist that reflects how you actually want to invest.
- If you are hunting for companies that pair resilience with measured risk, start with a basket of 29 resilient stocks with low risk scores that may help smooth out portfolio volatility.
- For investors who care about financial strength first and share price second, consider filtering for a list of solid balance sheet and fundamentals (24 results) to see which businesses look built to withstand tougher conditions.
- Income focused readers who want cash returns from day one can scan a universe of 5 dividend fortresses that already offer sizeable yields.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com