
MarineMax (HZO), Why Is The Stock Back In The Spotlight?
MarineMax (HZO) has quietly put up a very strong run, with the stock showing a total return above 110% over the past year and more than 70% over the past 3 months.
The sharp 50.2% 90 day share price return and 119.1% year to date share price gain have pushed MarineMax to about $52.76, while the 1 year total shareholder return of 113% and 3 year total shareholder return of 74.9% point to strong, sustained momentum.
Scan beyond MarineMax's surge and see how other retailers with strong recent moves compare in our curated list of 33 high quality undervalued stocks.
Bulls view MarineMax as an earnings rebound and margin improvement story, while bears point to a muted price target and a choppy five-year return. Which case does the current valuation actually support?
Most Popular Narrative: 7% Overvalued
MarineMax last closed at $52.76, while the most followed narrative assigns a fair value of $49.40 using a 10.4% discount rate. That view leans heavily on how profitable service lines and marinas shape the earnings mix and help offset a softer boat market.
Expansion into higher margin service and marina activities, including parts and service, finance and insurance, marinas and superyacht services, which recently lifted consolidated gross margin into the mid 30% range, can continue to increase the share of recurring revenue and support more resilient net margins.
Ongoing investment in MarineMax digital platforms such as Boatyard and Customer IQ, which have been adding subscribers and wider rollouts, can deepen customer relationships and cross sell opportunities across the marine and financial services network, with potential benefits for both revenue and operating margins.
See why 7 investors see MarineMax as 7% overvalued.
Result: Fair Value of $49.40 (OVERVALUED)
Still, double digit declines in U.S. powerboat registrations in 2026 and legal uncertainty around the proposed US$53 Safe Harbor deal could easily knock this MarineMax narrative off course.
Find out about the key risks to this MarineMax narrative.
Another View: What Multiples Say About MarineMax
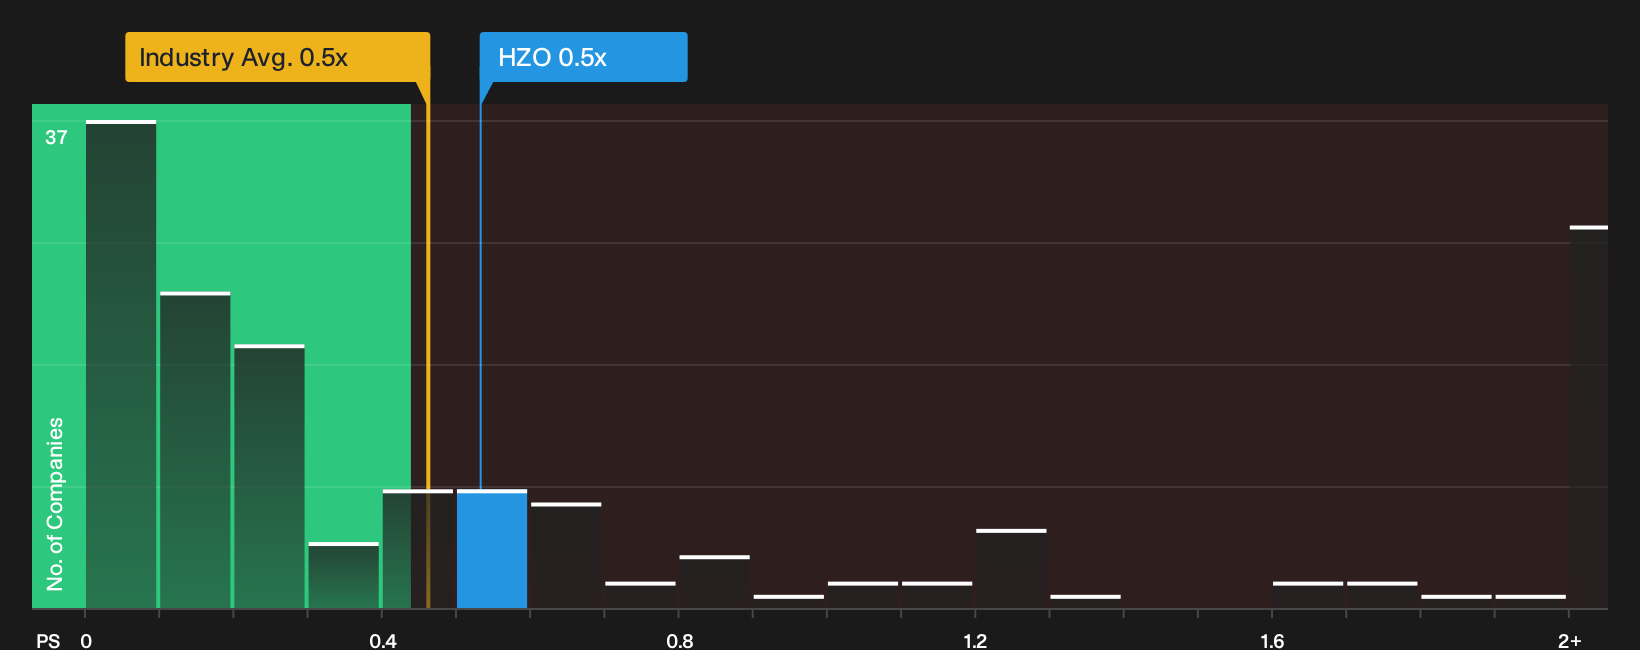
The first narrative tags MarineMax as about 7% overvalued versus a $49.40 fair value, yet its P/S of 0.5x undercuts the peer average of 3.1x and sits slightly above a 0.4x fair ratio. That mix of apparent cheapness on sales, but a premium to the fair ratio, raises a simple question: How much margin and growth improvement do you think the market will actually pay for?
For a closer look at how this pricing stacks up against both peers and the fair ratio, including what that gap might mean for upside or downside risk, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
MarineMax now has bulls and bears both speaking up, which makes this a moment for you to look closely and move with intention. If you want to weigh those concerns and potential upsides side by side, start with the 3 key rewards and 3 important warning signs.
Looking for more MarineMax-sized ideas?
If MarineMax has you thinking bigger, broaden your watchlist with fresh stock ideas built from clear fundamentals, resilient balance sheets, and income focused opportunities.
- Target under-the-radar opportunities that still pass tough quality checks with a curated 19 high quality undiscovered gems.
- Strengthen your downside protection by focusing on companies with robust finances using the list of solid balance sheet and fundamentals (24 results).
- Build a steadier income stream by focusing on reliable payouts through the 5 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com