
What Wacker Chemie Doubters Overlooked
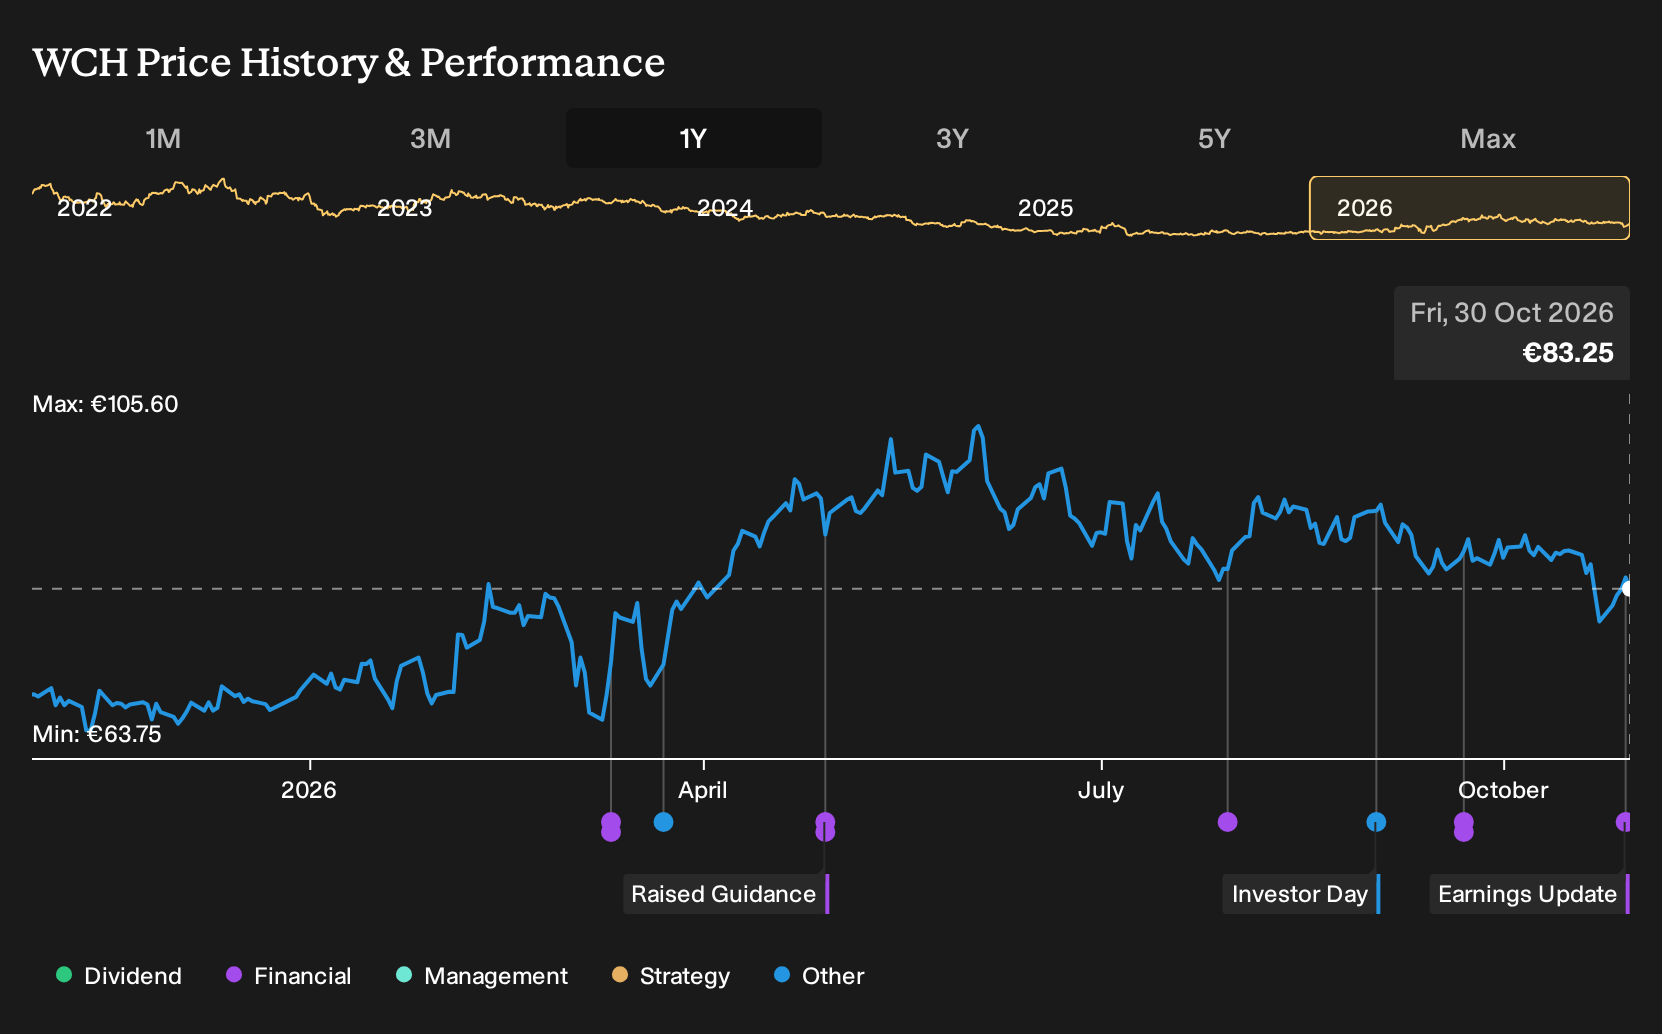
If you followed Wacker Chemie headlines this year, the concrete news was not about a moonshot product but a new thermally conductive silicones line in Japan aimed at e-mobility clients and a tougher PACE cost program that fed into stronger EBITDA and a higher 2026 sales outlook. Investors who held Wacker Chemie over the past year are up 21.6%, including dividends. If you were deciding back on 30 October 2025, what did you need to believe about polysilicon contracts, carbon costs, and restructuring to back that outcome?
This theme extends beyond Wacker Chemie. See which of 33 best rare earth metal stocks may still merit a closer look.
The Argument You Would Have Been Weighing Up On Wacker Chemie
The shares cost €68.75 at the start. Anyone buying Wacker Chemie then was really choosing between two sharply different stories about polysilicon, carbon costs, and what the new assets could earn.
The bullish narrative pointed to a Fair Value of €113, a price implied by expectations. It was built on the idea that new polysilicon and silicones capacity would feed renewables, batteries, and semiconductors, with long duration premium contracts and higher EBITDA margins over time.
The bearish view anchored on a Fair Value of €52 and stressed that persistent global overcapacity, weak solar demand, and rising carbon related regulation could keep utilization low, squeeze net margins, and hold back free cash flow even after the expansion spend.
What The Results Changed For Wacker Chemie
The key update was Wacker Chemie lifting its 2026 EBITDA outlook to the upper half of the range after Q3 2026, with EBITDA helped by the PACE savings program and a terminated polysilicon contract. Revenue moved from €1,340.3m in Q3 2025 to €1,465.7m in Q3 2026. At the same time, a net loss of €86.1m turned into profit of €83.6m and net margin shifted from 6.4% negative to 5.7% positive. That mix of contract support and cost cuts supported the more optimistic interpretation of the results rather than a more cautious one.
The lesson is simple. When an investment thesis depends on margin repair from contracts and carbon-exposed assets, it is important to track reported EBITDA and net margin against prior loss levels and management guidance, not just sales. It is also important to test whether one-off gains, such as contract terminations, or repeatable savings and volume changes are driving the improvement.
What Wacker Chemie’s Recent Run Already Prices In
Today Wacker Chemie trades at €83.25, after a 21.6% gain over the past year, with this Narrative’s Fair Value sitting above that quoted level rather than below it.
The Narrative hangs on Wacker Chemie converting REFOCUS and PACE into sturdier margins and returns. The key question is whether sustained €300m plus PACE savings, while keeping capex within the guided band, can really hold.
"The current narrative that Wacker Chemie is undervalued rests on numbers that imply investors are paying little for the combination of a 15% ±2pp structural EBITDA margin ambition, ROCE above 10%, and leverage guided around 1x EBITDA with a roughly 50% dividend payout of net income."
One Narrative has put a figure on that disagreement. → See the Narrative with its higher Fair Value, assumptions and all
Before The Next Story Makes Headlines
By the time a rally makes headlines, you are reading about returns someone else has already earned. Why not go straight to the source and look for your own contrarian opportunity? These three companies trade below our estimated value.
- Company 1 - 38% below our estimate - uses expanded high horsepower capacity to supply long-duration power contracts for data centers.
- Company 2 - 48% below our estimate - shifts from low-margin assembly to co-designing complex hardware through a sketch-to-scale model.
- Company 3 - 43% below our estimate - scales digital platforms that process mortgage, housing and insurance transactions for interconnected industry participants.
Those are three of them. See all 204 potentially undervalued companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com