
Chugai Ro (TSE:1964) Stock Can Q2 Earnings Sustain Its Value Case?
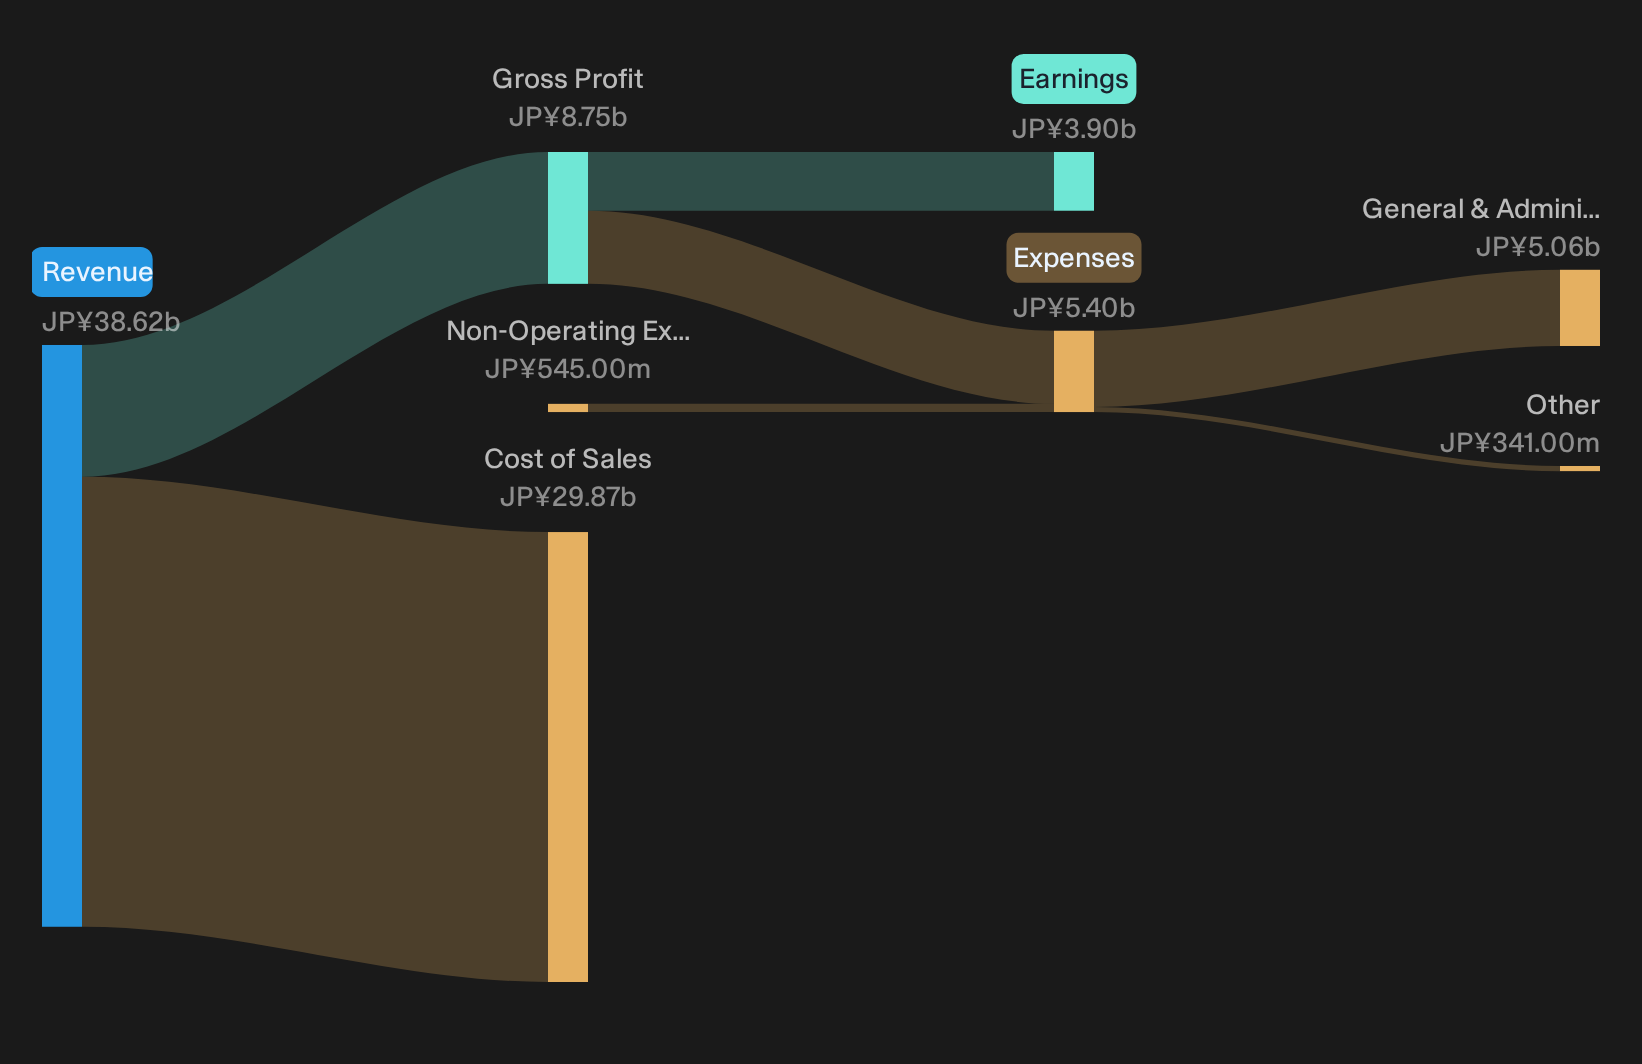
Chugai Ro just released its Q2 2027 numbers and the story is sharper than today’s flat close at ¥3,635 suggests. Traders have spent the last month edging the stock down about 4%, yet the business reported revenue of ¥9,936m and recorded a quarterly profit of ¥359m after a loss in Q1. The key tension is between sentiment and valuation. The shares trade on a P/E of 6.5x while carrying a 4.95% dividend yield, so today’s muted reaction appears more like caution around recent volatility than a clear response to these earnings.
Like the low P/E and near 5% yield on Chugai Ro but wary that a single quarter of profit after a loss might signal value trap risk rather than a clean turnaround? Compare this setup with our list of resilient, low-risk candidates in the 23 resilient stocks with low risk scores
Q2 2027 Earnings Summary
- Revenue (Q2 2027 vs. Q2 2026): ¥9,936m vs. ¥8,422m (up about 18%)
- Net Income (Q2 2027 vs. Q2 2026): ¥359m vs. ¥351m (broadly flat, modest improvement)
- Basic EPS (Q2 2027 vs. Q2 2026): ¥51.29 vs. ¥48.45 (up about 6%)
- Trailing 12-month Net Margin (Q2 2027 vs. Q2 2026): 10.1% vs. 9.7% (slight margin improvement over the year)
A ¥1.7bn one-off gain lifted reported margins. Ask Charlie which one-off gain is boosting Chugai Ro’s earnings.
Chugai Ro’s Earnings and the Supportive Bull Case
For a reader leaning positive on Chugai Ro, the revenue line helps. Sales of ¥9,936m compare against ¥8,422m a year earlier, which fits a story of customers still investing in the company’s thermal and environmental kit. Profitability is not surging, yet net income and basic EPS both show modest year on year improvement. For an industrial supplier tied to customer capex cycles, that combination of higher turnover and slightly better earnings suggests the underlying offering still has traction with manufacturers upgrading or maintaining their production lines.
Where The Bear Case Still Finds Ammunition
Bears do not run out of talking points here. Chugai Ro only just moved back into the black after a Q1 loss, and net income of ¥359m is only slightly ahead of last year. That makes the earnings base look thin. Margins on a trailing 12 month view have only inched up, which means any slowdown in orders or project delays could squeeze profitability again. Recent share price weakness over 7, 30 and 90 days also shows investors have not rushed to re-rate the stock on this set of results.
After a loss in Q1 and only a slight net income lift this quarter, thin margins leave little room for error. Review our risk analysis for Chugai Ro which shows 1 important warning sign to see whether one off items and other potential pressure points hint at deeper structural vulnerabilities.Hunt Quiet Disconnects In Japan
Chugai Ro shows how a solid headline improvement can still leave investors cautious and slow to re-rate the shares. The real opportunity is finding stocks that could be undervalued before the market adjusts its view.
- Company 1 - 27% below our estimate - supplies grinding tools and specialty ceramics that help equipment makers meet tighter tolerance and reliability demands.
- Company 2 - 45% below our estimate - expands deposit and lending relationships and cross-sells securities, leasing and research services to smaller corporates and households.
- Company 3 - 29% below our estimate - sells motion guides and bearings that equipment builders specify when precision and compactness become non negotiable in their designs.
Those are three of them. See the full list of 16 companies trading below our fair value estimates →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com