
3 Canadian Growth Stocks With Earnings Growth Over 21%
Australian inflation data is under the microscope, with some economists arguing official figures may be overstating the problem and keeping interest rates higher than they need to be. If that view gains traction, growth focused stocks with solid finances could attract fresh attention as rate pressure eases. This article highlights three Canadian companies that analysts expect to grow earnings quickly while still keeping their balance sheets in reasonable shape.
The three stocks highlighted here offer a compelling starting point if you want exposure to healthy high growth potential businesses that still keep their finances in check. However, if you want the names that matter most, these 14 best high growth potential stocks are the strongest companies we've found.
Cameco (TSX:CCO)
Overview: Cameco is a Canadian nuclear fuel supplier whose uranium mining, processing, and Westinghouse reactor services support electricity generation worldwide.
Market Cap: CA$46.86b
Cameco ties neatly into the Healthy high growth potential theme because analysts expect earnings to increase over the next three years, supported by uranium demand and Westinghouse exposure across the nuclear fuel cycle. Forecast ROE improvement and earnings quality provide some support for that outlook, although future returns still depend on how one unseen pressure shapes pricing power and margins.
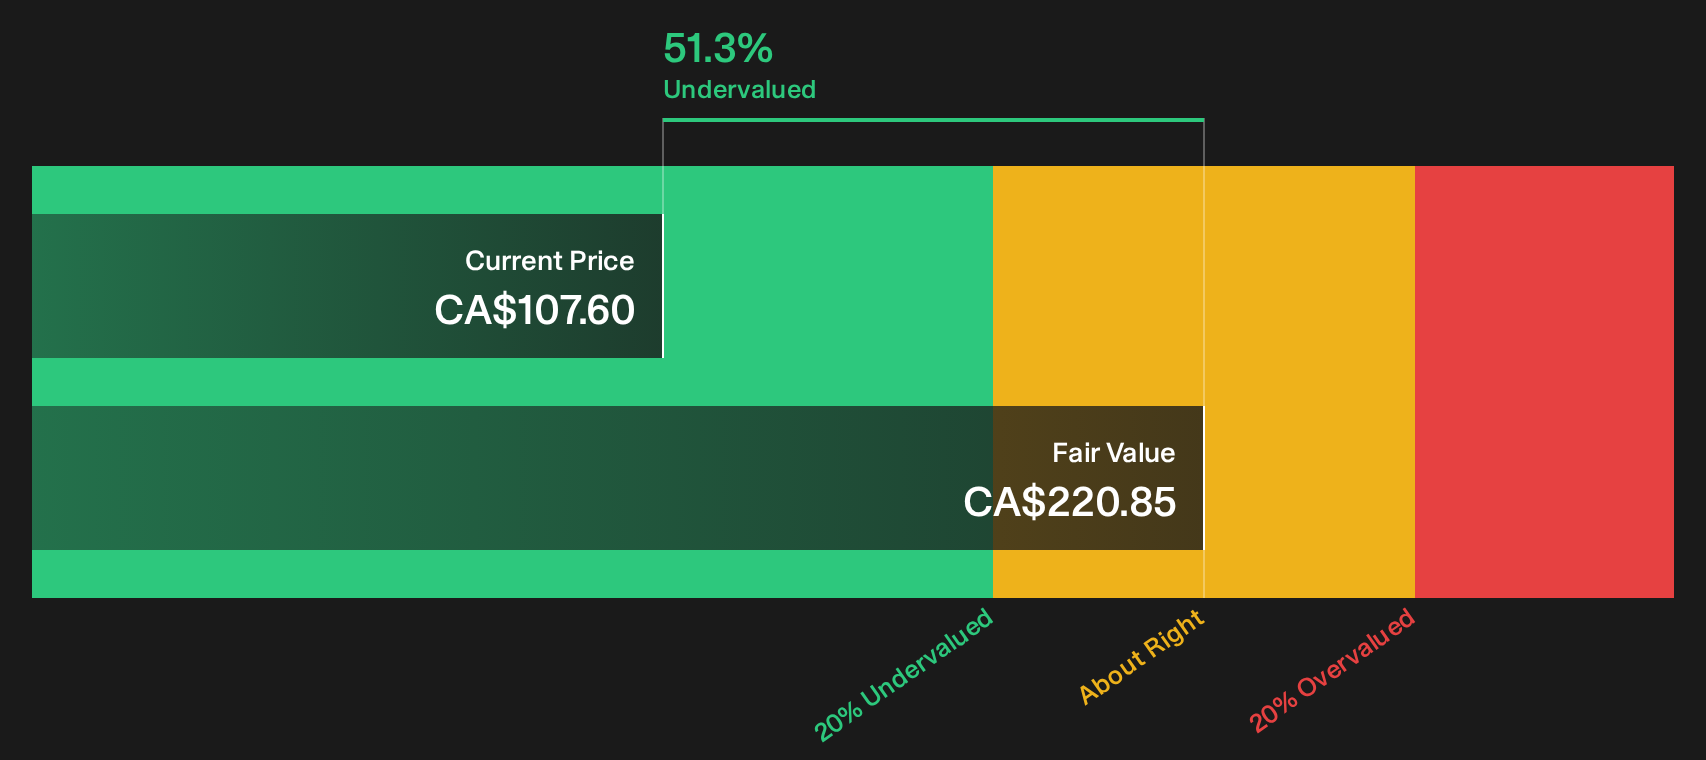
That unseen pressure is exactly what the DCF valuation analysis for Cameco weighs up, so you can see how pricing power assumptions might shift the whole earnings story.
Alamos Gold (TSX:AGI)
Overview: Alamos Gold is a Toronto based producer that runs gold mines in Canada and Mexico, with Cerro Negro and Island Gold expansions central to near term earnings growth.
Operations: Alamos Gold generates about US$1.1b from the Island Gold District and US$599 million from Mulatos, with most revenue coming from Canada.
Market Cap: CA$16.04b
Alamos Gold sits firmly in the Healthy high growth potential theme because its producing assets are already funding expansion that analysts expect to support strong earnings growth while keeping the balance sheet in acceptable shape.
"Integration of higher grade underground ore from Island Gold into the larger Magino mill is expected to increase throughput and reduce unit processing costs, which can support higher revenue and stronger net margins as the combined Canadian operation matures."
The real swing factor for Alamos Gold is how one cost and execution pressure ultimately shapes margins just as production scales up.
That execution risk is exactly why reading the full narrative for Alamos Gold can be useful for seeing how cost pressures, grades and capital plans might still accelerate Alamos Gold's story.

Energy Fuels (TSX:EFR)
Overview: Energy Fuels is a US based producer that focuses on uranium for nuclear fuel, alongside rare earth and mineral products.
Operations: Energy Fuels currently generates about US$106 million in revenue almost entirely from its uranium segment, with segment adjustments minimal.
Market Cap: CA$2.69b
Energy Fuels matters for the Healthy high growth potential theme because uranium driven earnings expectations sit alongside a push into rare earth processing that could reshape its mix of future cash flows.
"Completion and commissioning of the White Mesa Mill rare earth separation Phase 2 expansion (potentially increasing monazite processing to 60,000 tonnes/year and enabling commercial-scale heavy rare earth production such as Dy/Tb) could establish Energy Fuels as a major western supplier, capturing price premiums driven by western supply chain security and increasing electrification demand, supporting long-term revenue and margin upside."
The real test for Energy Fuels is how one future supply and pricing balance ultimately feeds through to margins just as volumes scale.
If that pricing balance is what you are watching, the full narrative for Energy Fuels explains how Energy Fuels' uranium and rare earth story could accelerate from here.

Seeking Alternatives Before The Crowd?
Fresh ideas move first. Breakout stories gain momentum while others watch prices move away. Identify potential opportunities still under the radar for now. Consider acting early if appropriate for your strategy.
- Target resilient compounders that navigate volatility by scanning the 9 resilient stocks with low risk scores before those price stories are fully covered in the headlines.
- Spot early movers in digital assets infrastructure using the curated 18 cryptocurrency and blockchain stocks before the next wave of attention focuses on the theme.
- Look for potential income-oriented candidates with the hand picked 3 dividend fortresses while yields remain attractive and before payout trends attract wider interest.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com