
Does Raised Guidance Change The Bull Case For Garmin Stock (GRMN)?
- Garmin reported third quarter 2026 sales of US$1.99b and net income of US$541.66m, raised full year revenue guidance to about US$8.15b, and outlined a short term fourth quarter top line decline tied to weaker domain controllers.
- The business paired this guidance update with a focused push into high end cycling devices and smart trainers, while steadily retiring shares through a US$92.82m buyback that reduced the share count by 0.19%.
- We now look at how Garmin's investment narrative shifts in light of raised full year guidance and a heavier cycling product focus.
Scan beyond Garmin and see how cyclists’ demand for premium hardware is playing out across 95 robotics and automation stocks tied to automation, smart devices, and connected training gear.
Garmin Investment Narrative Recap
To own Garmin, you need to be comfortable with a story where Fitness, services and higher end devices offset softer pockets like Outdoor and Auto OEM. The raised full year revenue outlook to about US$8.15b indicates that management sees that mix holding up, even as fourth quarter sales are expected to decline year over year on weaker domain controllers.
The key short term catalyst is continued execution on higher margin wearables and services, while keeping a grip on costs as memory pricing shifts. The biggest risk is that ongoing Outdoor softness and the expected Auto OEM downturn, combined with those component headwinds, start to pressure consolidated margins more than expected.
The most relevant update for that catalyst is the new Edge 1060 cycling computer. This product pushes Garmin deeper into premium performance hardware tied into its wider software ecosystem. Voice control, deeper training tools and GroupRide features keep cyclists inside Garmin’s platform rather than treating the device as a one off gadget.
That matters because higher engagement with Edge, Tacx trainers and Garmin Connect can support both hardware demand and subscription style services over time. The risk is that cycling remains a discretionary spend category, so any slowdown in rider appetite for US$799.99 devices could leave Garmin more exposed if Outdoor and Auto OEM are already under pressure.
What The Garmin Consensus Implies
Analysts are effectively asking you to underwrite a Garmin story that leans on steady top line expansion and a larger profit pool a few years out. The assumptions are not extreme on paper, yet they stack up to a very specific earnings and valuation picture by the end of the decade.
Consensus forecasts point to revenue growth of 9.1% per year over the next three years, paired with a modest squeeze in profit margins from 24.5% today to 23.6%. That combination assumes higher cost pressure and mix shifts do not fully erode profitability, even while Fitness, services and higher priced cycling hardware carry more of the load as Outdoor and Auto OEM deal with softer demand and rising memory costs.
On the bottom line, the group of covering analysts expects earnings to move from US$1.9b today to about US$2.3b by 2029, with the most optimistic forecasts stretching to US$3.0b. The increase from current earnings to the US$2.3b consensus figure is roughly US$400m, which implies a larger profit base even after factoring in the expected margin dip and small annual growth in the share count of 0.27%.
Those earnings assumptions then feed directly into how the stock is framed. The consensus view looks for Garmin to trade on a P/E of 31.5x in 2029, up from 28.9x today and well above the current 13.1x P/E for the broader US Consumer Durables industry. That higher multiple effectively prices in confidence that the Fitness and cycling centric ecosystem, including software layers like Garmin Connect and TrainingPeaks, can justify a premium versus peers that lean more on lower margin hardware.
Garmin's narrative projects US$10.0b revenue and US$2.3b earnings by 2029. This implies 9.1% yearly revenue growth and an earnings increase of about US$400m from the current US$1.9b.
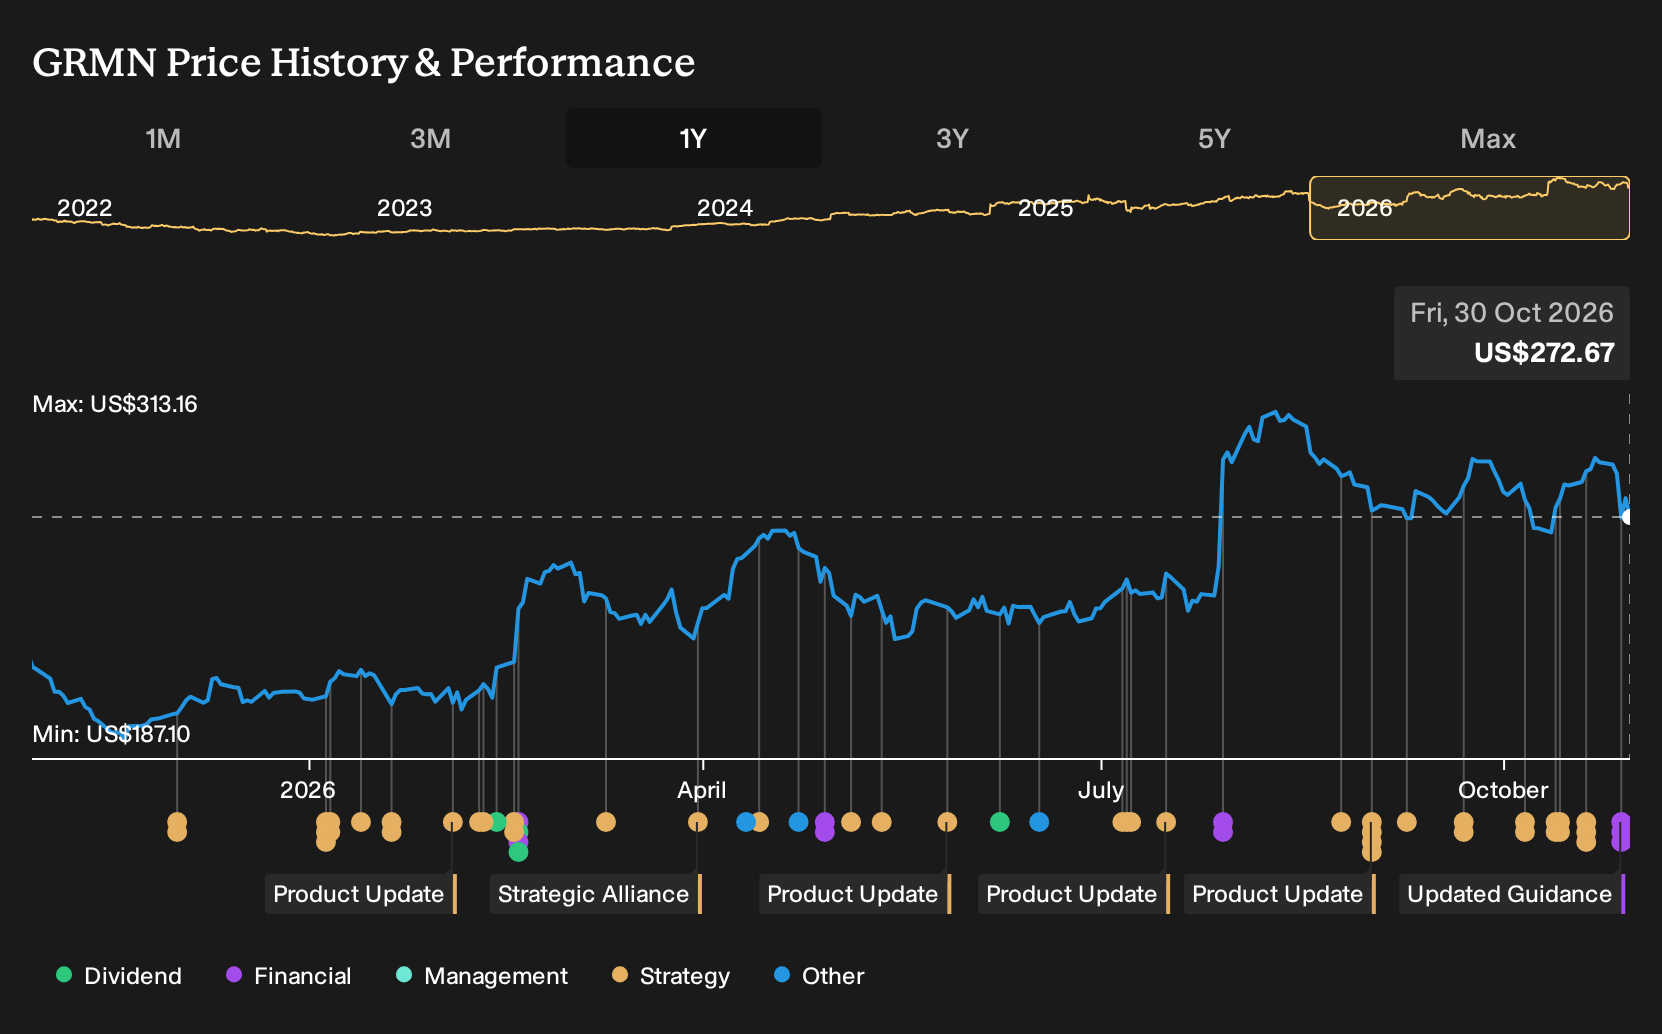
Price targets simply translate those earnings and multiple ideas into a dollar figure. The average analyst target of US$302.00 sits 6.9% above the recent US$281.16 share price, with a fairly wide spread between US$231.00 on the low end and US$370.00 on the high side. That range tells you there is real disagreement about how durable Garmin's Fitness and services growth will be and how much investors will be willing to pay for those future earnings.
For you as an investor, the useful takeaway is not whether US$302.00 is "right" but which assumptions you find realistic. If you think revenue can reach US$10.0b, margins hold near 23% and the market is comfortable paying more than 30x earnings for Garmin in 2029, then the consensus case lines up with your view. If any of those pillars look too demanding, the current setup starts to look more like a fully priced cycling and wearables platform that leaves less room for disappointment on execution.
Uncover how Garmin's fair value indicates an 11% potential upside to its current price before sentiment around Garmin's premium cycling push closes that gap.
Exploring Other Perspectives
One alternate viewpoint focuses on margin risk rather than revenue growth. The most bearish Garmin analysts previously pencilled in about US$10.2b of 2029 revenue and US$2.5b of earnings, yet still landed on a US$220 price target. You effectively get a story where higher component costs and Auto OEM losses matter more than new cycling launches. With fresh guidance and the Edge and Tacx releases now on the table, those harsher assumptions may shift. Treat them as one of several reference points to test your own view against.
Explore 4 other Garmin fair value estimates, including one that indicates as much as 19% downside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so rely on your own analysis.
- A great starting point for your Garmin research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Garmin. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Garmin's overall financial health at a glance.
Looking For More Investment Ideas Beyond Garmin?
If the Garmin story leaves you wanting a wider hunting ground, the Simply Wall St Screener can help you quickly filter the market and line up a few more candidates to research in detail.
- For investors who want potential upside with stronger quality markers than the broader market, scan through a curated set of 19 high quality undiscovered gems that might warrant a closer look.
- If capital preservation sits high on your priority list, narrow your focus to a 29 resilient stocks with low risk scores that score well on resilience and balance sheet strength.
- Income seekers who care about cash returns as much as price moves can review a group of 5 dividend fortresses that offer higher yields while still passing basic financial health checks.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com