
Should Upcoming Earnings Require Action From Monster Beverage Stock Investors?
- Monster Beverage is set to report its third quarter 2026 results after the close on 5 November, followed by an investor call led by CEO Hilton Schlosberg, with international markets such as China, India, Brazil and Mexico in focus for revenue diversification.
- The key tension for Monster Beverage is how far international expansion and category mix can support fundamentals at a time when the high P/E ratio and rising distribution, aluminum and marketing costs keep valuation and profitability under close scrutiny.
- We will now assess how Monster Beverage's investment narrative aligns with current expectations for international expansion ahead of its Q3 earnings.
Monster Beverage Investment Narrative Recap
To own Monster Beverage, investors need to believe the business can continue translating energy drink demand into steady earnings while absorbing higher freight, fuel, aluminum and marketing costs. A key near-term consideration is whether international growth in markets such as China, India, Brazil and Mexico can offset these rising expenses and support operating leverage.
The biggest short-term swing factor is how management balances price increases and mix shift toward zero sugar and premium offerings against these input and distribution headwinds. The main risk is that cost pressures or weaker Alcohol Brands performance compress margins more than anticipated around this earnings update. If that does not occur, the impact from this event may be limited.
One detail closely tied to this earnings setup is Monster Beverage planning selective price increases in the U.S. during Q4 2026, supported by a formal revenue growth management capability. This is notable because distribution and selling expenses have taken a larger share of net sales, and aluminum costs are expected to see a modest sequential increase through at least the end of 2026.
If these price actions and mix management efforts are effective, they could help stabilize gross margin while the company expands further into APAC, EMEA and LATAM energy categories. If execution is weaker, higher tariffs or commodity costs, along with softer Alcohol Brands performance, could pressure profitability and lead to closer scrutiny of the high P/E ratio after the November 5 report.
Monster Beverage's narrative projects US$12.1b revenue and US$2.9b earnings by 2029. This assumes 9.6% yearly revenue growth and an earnings increase of about US$800m from current earnings of US$2.1b.
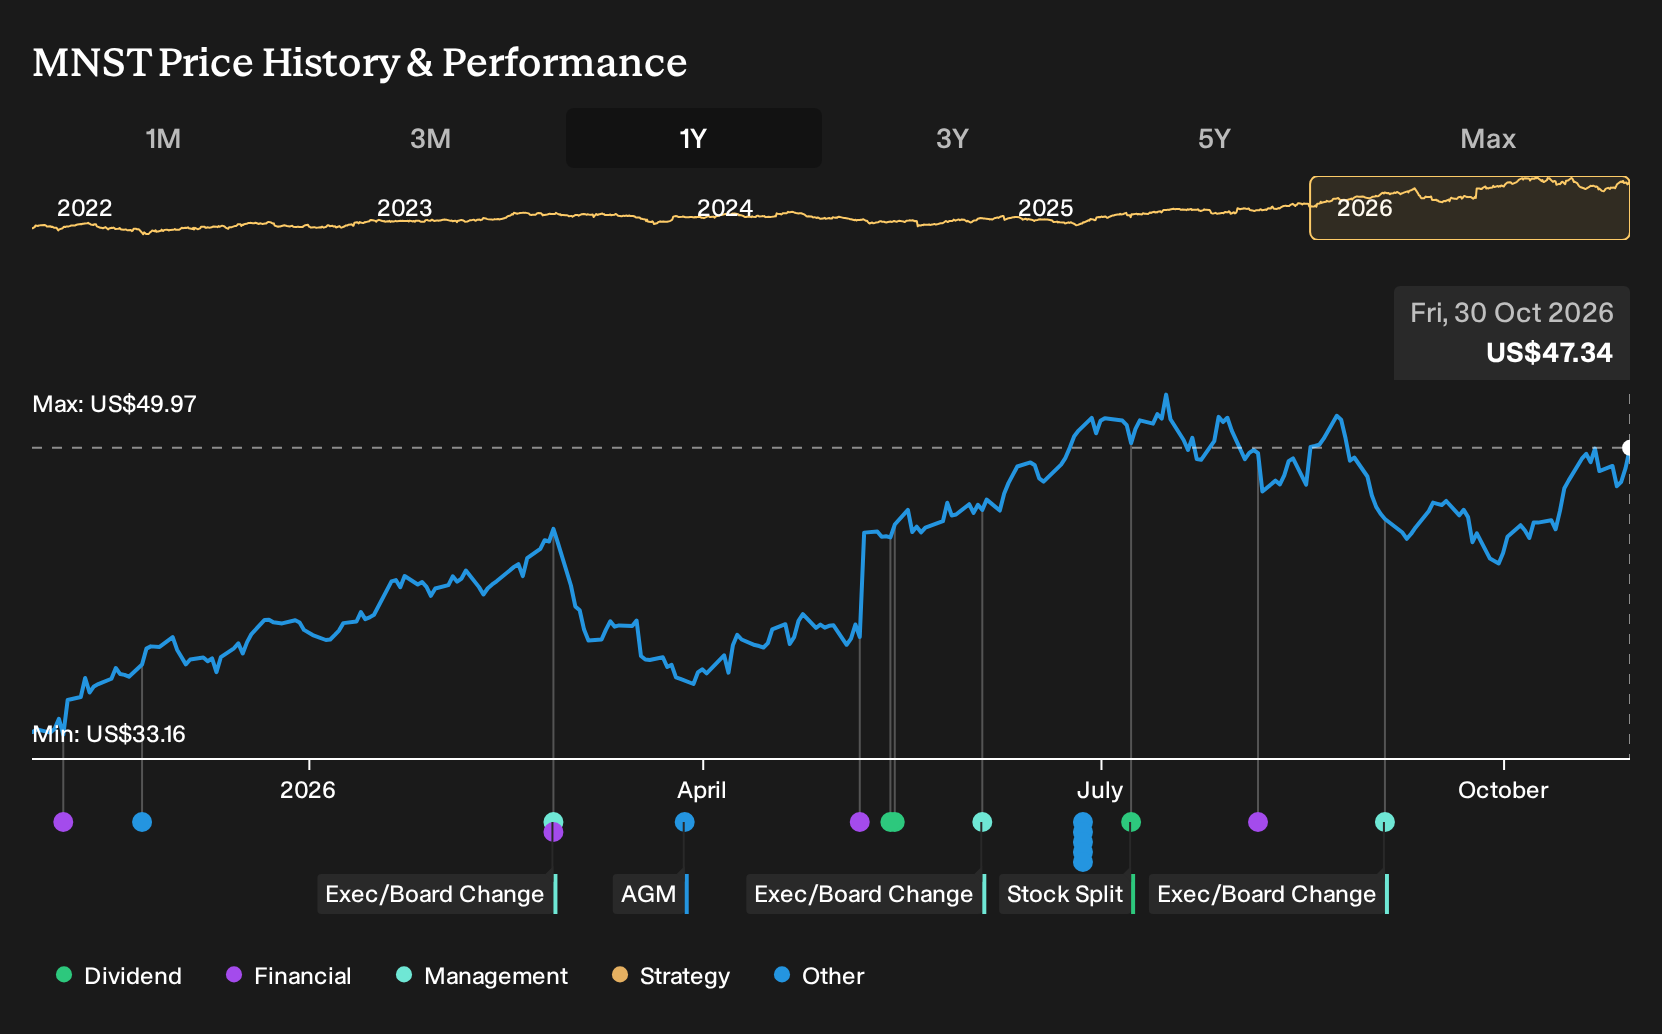
Uncover why Monster Beverage's fair value indicates a 6% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternate angle on Monster Beverage places greater emphasis on execution risk following Americas CEO Rob Gehring’s planned departure. This view suggests that leadership change could matter more than aluminum or freight costs. The most cautious analysts were working from assumptions of roughly US$11.7b in revenue and US$3.0b in earnings by 2029. Those assumptions were made before this earnings release, so treat them as moving pieces rather than fixed truths and consider how your own expectations compare.
Explore 3 other Monster Beverage fair value estimates, including one that suggests the potential for as much as 14% downside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Monster Beverage research is our analysis highlighting 2 key rewards that could impact your investment decision.
- See our latest analysis for Monster Beverage. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Monster Beverage's overall financial health at a glance.
Looking For More Investment Ideas Beyond Monster Beverage?
If Monster Beverage has sharpened your thinking about brands, pricing power and expansion risk, it can help to widen the lens and compare it with other listed businesses that share similar qualities or offer very different trade offs.
- For investors who want potential upside but still care about valuation discipline and balance sheet quality, review a curated 19 high quality undiscovered gems that may not yet be widely followed.
- If capital preservation and smoother ride potential are higher on your list, weigh up a set of 29 resilient stocks with low risk scores that score well on resilience and fundamental strength.
- Income focused investors can scan a group of 5 dividend fortresses that combine higher yields with an emphasis on durability.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com