
Toast (TOST) Following FTC Lawsuit Is It Still Undervalued Or Already Priced In
Toast (TOST) moved into the legal spotlight after the Federal Trade Commission sued over how the Restore Online Shoppers' Confidence Act applies to its restaurant contracts, putting the company’s subscription model under intense scrutiny.
The lawsuit arrives after a mixed period for Toast, with the share price at US$31.68 and a 30-day share price return of 9.28% pointing to recent momentum. In contrast, a year-to-date share price return decline of 6.88% and a 1-year total shareholder return decline of 12.34% suggest longer term enthusiasm has cooled. Recent legal headlines now sit alongside an 81.13% total shareholder return over three years, so investors are weighing whether the current legal overhang shifts the balance between Toast’s past gains and the risk profile implied by its subscription driven model.
Spot legal pressure on Toast as a cue to reassess contract risk across your portfolio and scan our hand picked 30 resilient stocks with low risk scores for potentially more resilient exposure.Toast now looks like a robust restaurant software platform wrapped in a fresh layer of legal and sentiment risk. After that sharp three year run and recent rebound, is the business quality already fully reflected in the price?
Most Popular Narrative: 32% Undervalued
According to the most widely followed Toast narrative, a fair value of $46.44 versus the recent $31.68 close points to a wide valuation gap that sits in sharp contrast to the legal noise now surrounding the subscription contracts.
Margin of Safety
Moderate to Limited: Consensus intrinsic value estimates sit around $38 to $39, implying a potential 20% to 25% upside relative to the current price (~$30). However, the 35.5x P/E multiple already bakes in demanding ongoing growth expectations.
See why 5 investors see Toast as 32% undervalued.
Result: Fair Value of $46.44 (UNDERVALUED)
Still, the FTC lawsuit over subscription practices and Toast’s relatively high ~35.5x P/E could pressure sentiment if legal outcomes or profitability expectations shift.
Find out about the key risks to this Toast narrative.
Another View: Toast On Rich Earnings Multiples
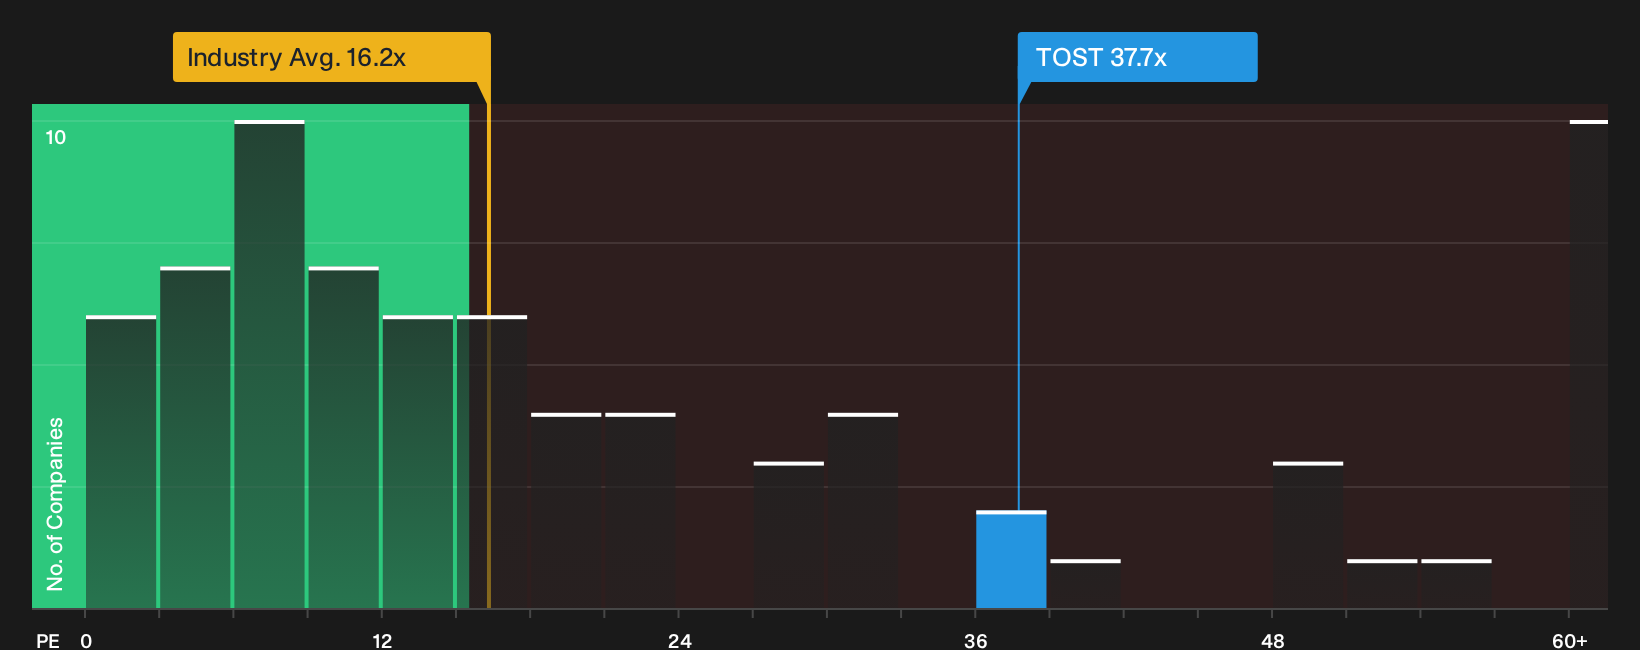
That $46.44 fair value anchor paints Toast as undervalued. A different lens tells a sharper story. On a 37.7x P/E versus a fair ratio of 19.3x and a Diversified Financial industry average near 16x, the stock carries a heavy premium that raises real repricing risk.
Investors who lean on earnings-based yardsticks may want to ask how much legal, competitive, and execution risk they are comfortable paying for at almost double the fair ratio See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
If this mix of legal risk and valuation debate around Toast feels muddled, treat that as a prompt to move quickly and test the numbers yourself using the 4 key rewards.
Looking For More Investment Ideas Beyond Toast?
If Toast’s legal risk and valuation story has you rethinking concentration in a single stock, broaden your opportunity set with a few focused screeners on Simply Wall Street.
- Target potential mispricings by scanning a curated pool of quality candidates through the 29 high quality undervalued stocks.
- Strengthen capital preservation by filtering for companies with healthier finances using the list of solid balance sheet and fundamentals (25 results).
- Pressure test your income plan by hunting for reliable cash distributions across the 5 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com