
Learn Why The Bull Case For Peoples Bancorp Stock Could Change Following Quarterly Earnings Report
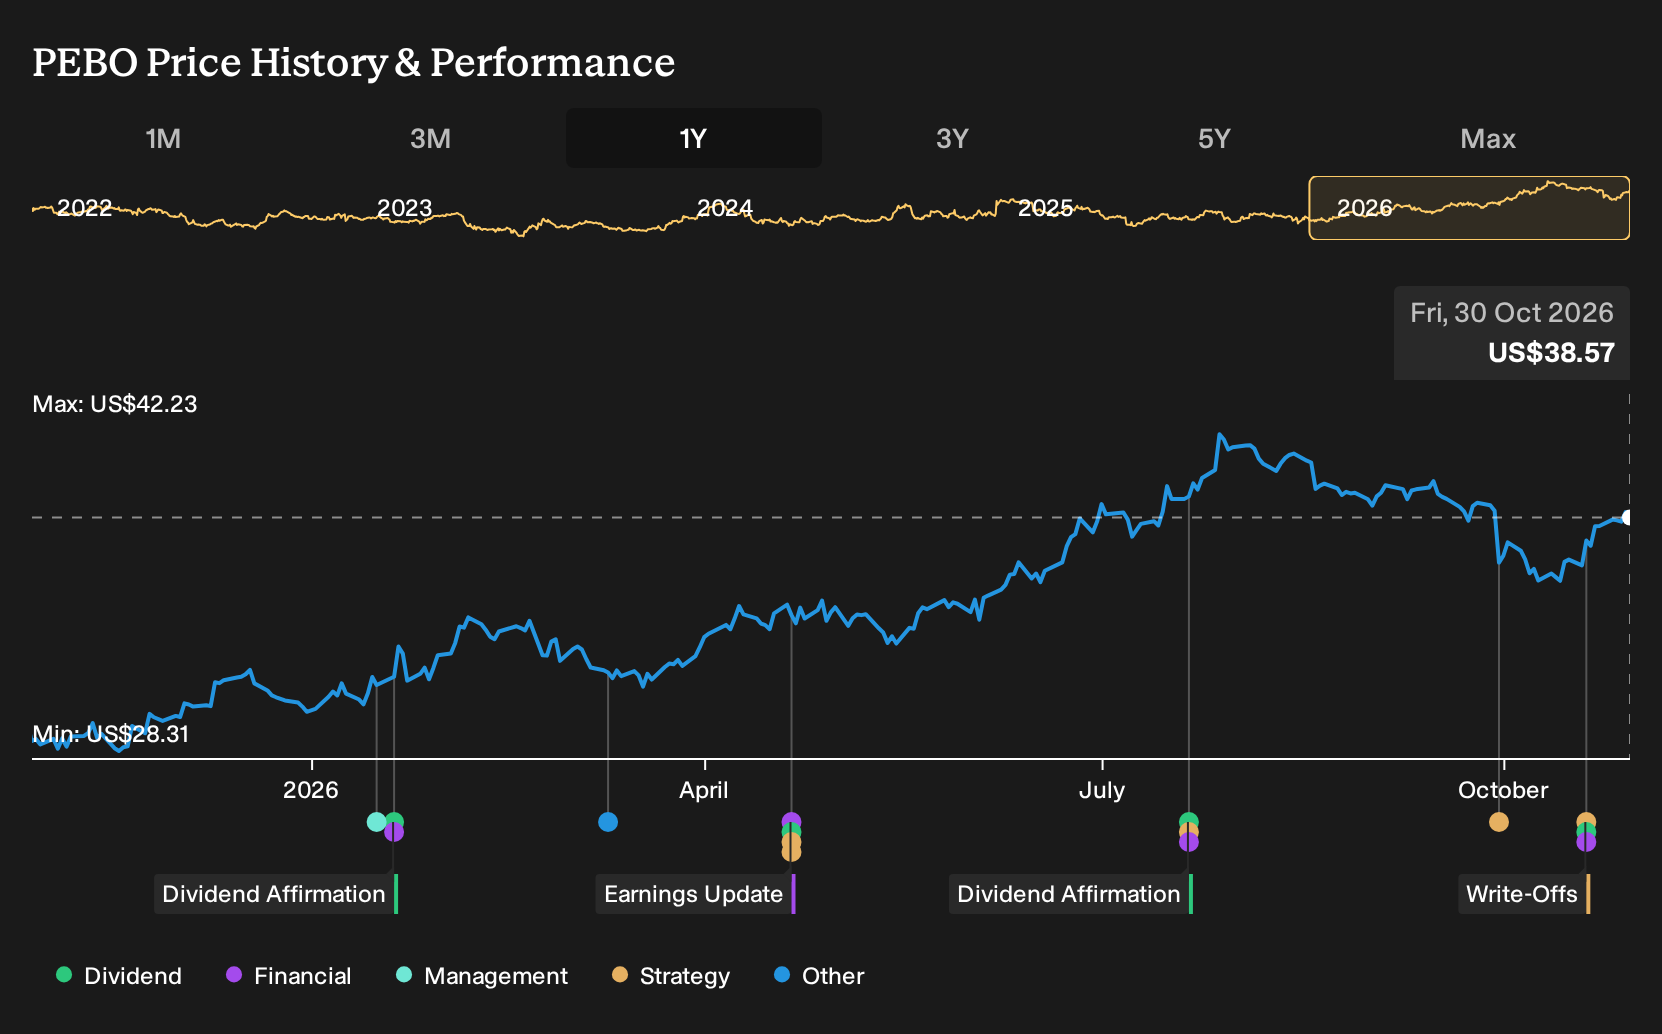
- Peoples Bancorp reported third quarter 2026 net interest income of US$93.84 million and net income of US$32.61 million, alongside net charge offs of US$6.01 million and a US$0.42 quarterly dividend declared in October, all based on unaudited figures.
- The combination of higher earnings per share, stable net charge offs compared to last year, and a maintained cash dividend highlights how Peoples Bancorp is balancing credit costs with ongoing shareholder payouts.
- We will look at how Peoples Bancorp's higher quarterly earnings shape the existing investment narrative built around acquisitions and integration.
Peoples Bancorp Investment Narrative Recap
To own Peoples Bancorp, you need to believe that management can turn a larger, more fee diverse regional bank into consistently better earnings without letting credit costs get away from them. The latest quarter fits that story. Net interest income reached US$93.84 million and net income came in at US$32.61 million, while net charge offs of US$6.01 million stayed close to last year.
The near term swing factor is still whether future integrations, balance sheet mix and funding costs keep supporting that earnings profile. Credit is the main watchpoint. Net charge offs remain controlled, yet any broad weakening in borrower health or tighter regulation could quickly test Peoples Bancorp credit appetite and the payoff from higher yielding portfolios.
The most relevant announcement for that debate is the earnings release for the quarter and the first nine months of 2026. Peoples Bancorp reported quarterly basic earnings per share from continuing operations of US$0.92, compared with US$0.83 a year earlier, and diluted earnings per share of US$0.91, compared with US$0.83, on higher net interest income.
That step up in profitability gives investors a fresh reference point as they weigh the larger acquisition and fee income story against execution risk and integration complexity. It also ties directly into the short term catalyst. Any sign that these earnings levels cannot be maintained once mergers close, or that credit losses rise meaningfully from here, would challenge the upbeat narrative around Peoples Bancorp.
What The Analyst Case Implies For Peoples Bancorp
Peoples Bancorp's narrative projects US$1.1b revenue and US$313.5 million earnings by 2029. This aligns with analysts' assumptions of 35.0% yearly revenue growth and an earnings increase of roughly US$196.4 million from US$117.1 million today, based on the projections provided.
Uncover how Peoples Bancorp's fair value indicates a 10% potential upside to its current price before the market closes that gap.
Exploring Other Perspectives
The four fair value estimates from the Simply Wall St Community range from about US$42 to nearly US$80 per share, which shows how far apart private investors can be on Peoples Bancorp. Those views were formed before the latest earnings, dividend affirmation and net charge off data, so you should weigh them against updated credit trends and acquisition milestones.
Explore 3 other Peoples Bancorp fair value estimates, including one that suggests it could be worth just $42.33.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Peoples Bancorp research is our analysis highlighting 5 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Peoples Bancorp. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, which makes it easy to evaluate Peoples Bancorp's overall financial health at a glance.
Looking For More Investment Ideas Beyond Peoples Bancorp?
If you want to stress test your thesis on Peoples Bancorp, a smart next step is to line it up against other businesses with different balance sheet profiles, dividend policies, and risk scores. The Simply Wall St Screener can help you do that quickly by surfacing companies that match the traits you care about most.
- If capital preservation is high on your list, scan a curated set of companies that appear more defensively positioned through the 30 resilient stocks with low risk scores.
- For investors focused on quality at a reasonable entry point, compare Peoples Bancorp with a 29 high quality undervalued stocks that may offer stronger fundamentals at current prices.
- If reliable income is a priority, line up its payout profile against a 5 dividend fortresses that offer higher yields with supporting cash flows.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com