
Japan Tobacco (TSE:2914) Stock Can Q3 Earnings Keep Record Profit In Focus
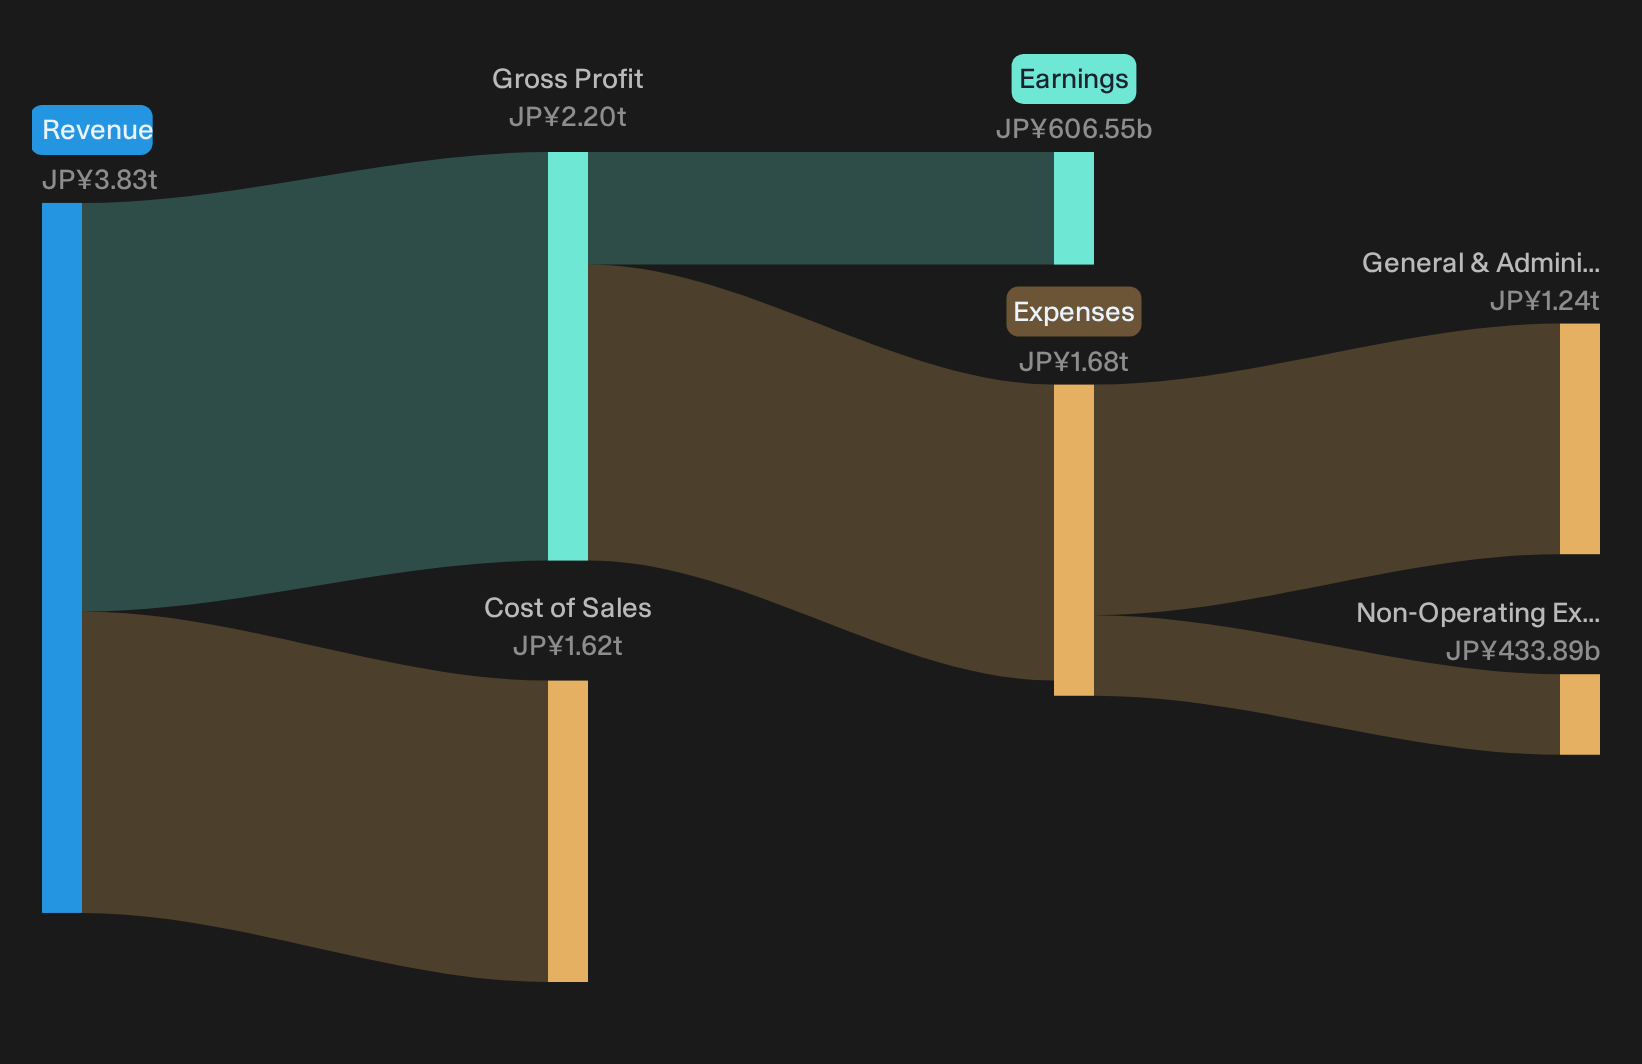
Japan Tobacco stock closed at ¥7,247 on Friday, leaving the 7 day return down about 3.9% even as fresh numbers hit the tape. The Q3 2026 print showed an increase in adjusted operating profit over the first nine months, and management raised full year guidance again. That mix, a weaker near term share price and a company talking about record profit for the year, puts the spotlight on what really matters for you.
Like the idea of Japan Tobacco talking up record profit while the share price lags in the short term, yet want similar income potential backed by balance sheets built for stress tests? Scan the 29 dividend fortresses to benchmark this setup against other high yield candidates with stronger downside cushions.
Q3 2026 Earnings Summary
- Revenue (Q3 2026 vs Q3 2025): ¥1,005,312m vs. ¥907,562m (up 10.8%)
- Net Income (Excl. Extra Items, Q3 2026 vs Q3 2025): ¥187,063m vs. ¥162,425m (up 15.1%)
- Basic EPS (Q3 2026 vs Q3 2025): ¥105.36 per share vs. ¥91.49 per share (up 15.2%)
- Trailing 12 Month Net Profit Margin (TTM to Q3 2026 vs TTM a year earlier): 15.9% vs. 15.5% (slight improvement in profitability)
Record guidance rests on keeping the pricing engine humming. Ask Charlie which risk could derail Japan Tobacco’s pricing run.
Japan Tobacco’s RRP Ambition Meets Hard Earnings Evidence
Japan Tobacco’s bullish story hinges on RRPs starting to reshape earnings quality rather than just adding a side stream of volume.
"Rapid adoption of Ploom AURA and EVO premium sticks in Japan, with HTS share at 15.5% in Q3 and user numbers about double compared to 2 years ago, supports a shift toward higher value reduced risk products that can lift revenue and support earnings quality over time."
Recent numbers show that RRP volume rising more than 30% and tobacco core revenue at constant FX up high single digits are now visible in the income statement. Higher pricing plus RRP growth helped push 9M AOP at constant FX up double digits, and management has raised full year AOP and profit guidance while calling for record results. That combination suggests the heated tobacco push is starting to carry financial weight, not just consumer buzz.
That disagreement has a full argument behind it. → Uncover the higher Fair Value this Narrative argues for.
Japan Tobacco Costs, FX And RRP Spend Under The Microscope
One key worry is that Japan Tobacco loads up on heated tobacco spending without proving it can pay its own way.
"the planned ¥800b RRP investment program for 2026 to 2028, with spending skewed to later years, risks locking in high marketing and capital outlays before profitability is proven in many of the roughly 30 target markets."
Current 9M figures show AOP and profit still rising after heavier Ploom marketing and new device launches, so the feared margin crunch is not yet visible. Input cost inflation and Russia downtrading are present, but raised AOP guidance and maintained dividend imply these pressures remain contained for now rather than overwhelming earnings.
Hunt Quiet Disconnects In Japan
Japan Tobacco recently combined a softer share move with management discussing record profit. The real opportunity sits in stocks that could be undervalued before the market adjusts them.
- Company 1 - 25% below our estimate - supplies capacitors and power modules embedded in electrified vehicles and connected devices.
- Company 2 - 44% below our estimate - grows fee and interest income by layering leasing, cards and regional services onto a lending base.
- Company 3 - 37% below our estimate - designs and maintains complex air and cooling systems for critical facilities with rising data density and uptime needs.
That is three of the list. See all 15 potentially undervalued companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com