
Western Alliance Bancorporation (WAL) Stock May Be Undervalalued After Phoenix Deposit Lead
Western Alliance Bancorporation has delivered a 68.3% gain over the past three years, yet the bigger issue for anyone looking at the stock today is whether that share price now lines up with the earnings power behind it. Recent shifts in its regional banking footprint keep pushing the conversation back to a simple question for investors who hold or track Western Alliance Bancorporation: what are they really paying for its profits at the current valuation?
- The 68.3% three year return puts real weight on the question of whether Western Alliance Bancorporation's earnings can support the price level the market now assigns to the stock.
- Western Alliance Bank extending its lead in Phoenix area deposits, with reported local balances of US$51.5b in 2026, can influence how investors think about the durability and scale of the earnings base that underpins the valuation.
- The analysts covering Western Alliance Bancorporation have run their own numbers. See what analysts think Western Alliance Bancorporation's shares could be worth.
The stock's next move may depend on whether the current price is justified by Western Alliance Bancorporation's earnings when set against the Fair Ratio benchmark.
If this has you rethinking what you pay for Western Alliance Bancorporation's earnings profile, it can help to compare against a focused list of 29 high quality undervalued stocks.
Is Western Alliance Bancorporation a Bargain on Earnings?
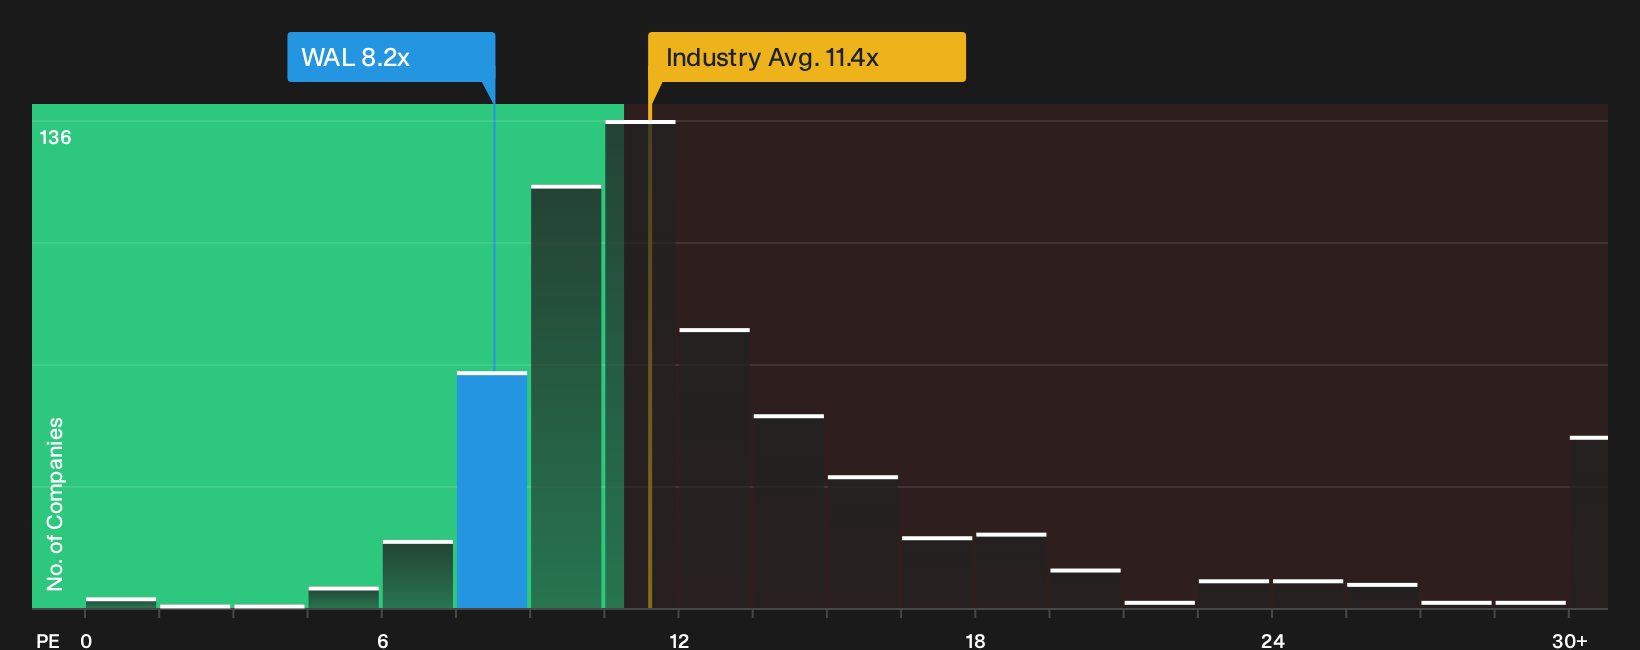
The P/E ratio tends to fit Western Alliance Bancorporation because earnings remain the main yardstick investors use to judge a regional bank. On this metric, the shares trade on roughly 8.2x earnings, which is below the Banks industry average of about 11.4x and also below the broader peer group level of around 12.6x. Against the Fair Ratio benchmark, which reflects what investors might typically pay for Western Alliance Bancorporation given its profitability profile and risk, the current P/E sits on the cheaper side.
Because Western Alliance Bank has already built a leading deposits position in the Phoenix area, with US$51.5b reported in 2026, the gap between the present 8.2x multiple and what similar financial institutions command raises a direct question about how confidently the market prices that earnings base. For anyone tracking NYSE:WAL, the current discount on this earnings measure is a clear signal to weigh against balance sheet strength, credit quality and future profitability before deciding if the valuation trade off feels attractive enough to act on. Explore the numbers behind Western Alliance Bancorporation's P/E valuation.
The Western Alliance Bancorporation Narrative: What Would Justify Today's Price?
Narratives on Simply Wall St extend the valuation question for Western Alliance Bancorporation by spelling out which future paths for growth, margins and earnings would need to play out for the current price to look meaningfully higher or lower. Instead of a single P/E or model output, they break that number into the underlying assumptions so you can see what has to happen and check over time whether those conditions are actually showing up.
One of the top community narratives on Western Alliance Bancorporation: 15% undervalued
"The current valuation implies that the market is discounting Western Alliance Bancorporation’s pivot toward higher returning capital allocation, growing fee and specialized deposit franchises..."
Discover why this Narrative puts Western Alliance Bancorporation at 15% undervalued.
Western Alliance Bancorporation’s valuation still leaves one big missing piece
Price multiples tell you what the market pays for Western Alliance Bancorporation today, but the unanswered piece is how professional forecasters currently map out its earnings power a few years from now. Explore where analysts expect Western Alliance Bancorporation to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com