
Does Quarterly Loss Change The Bull Case For Liberty Energy Stock (LBRT)?
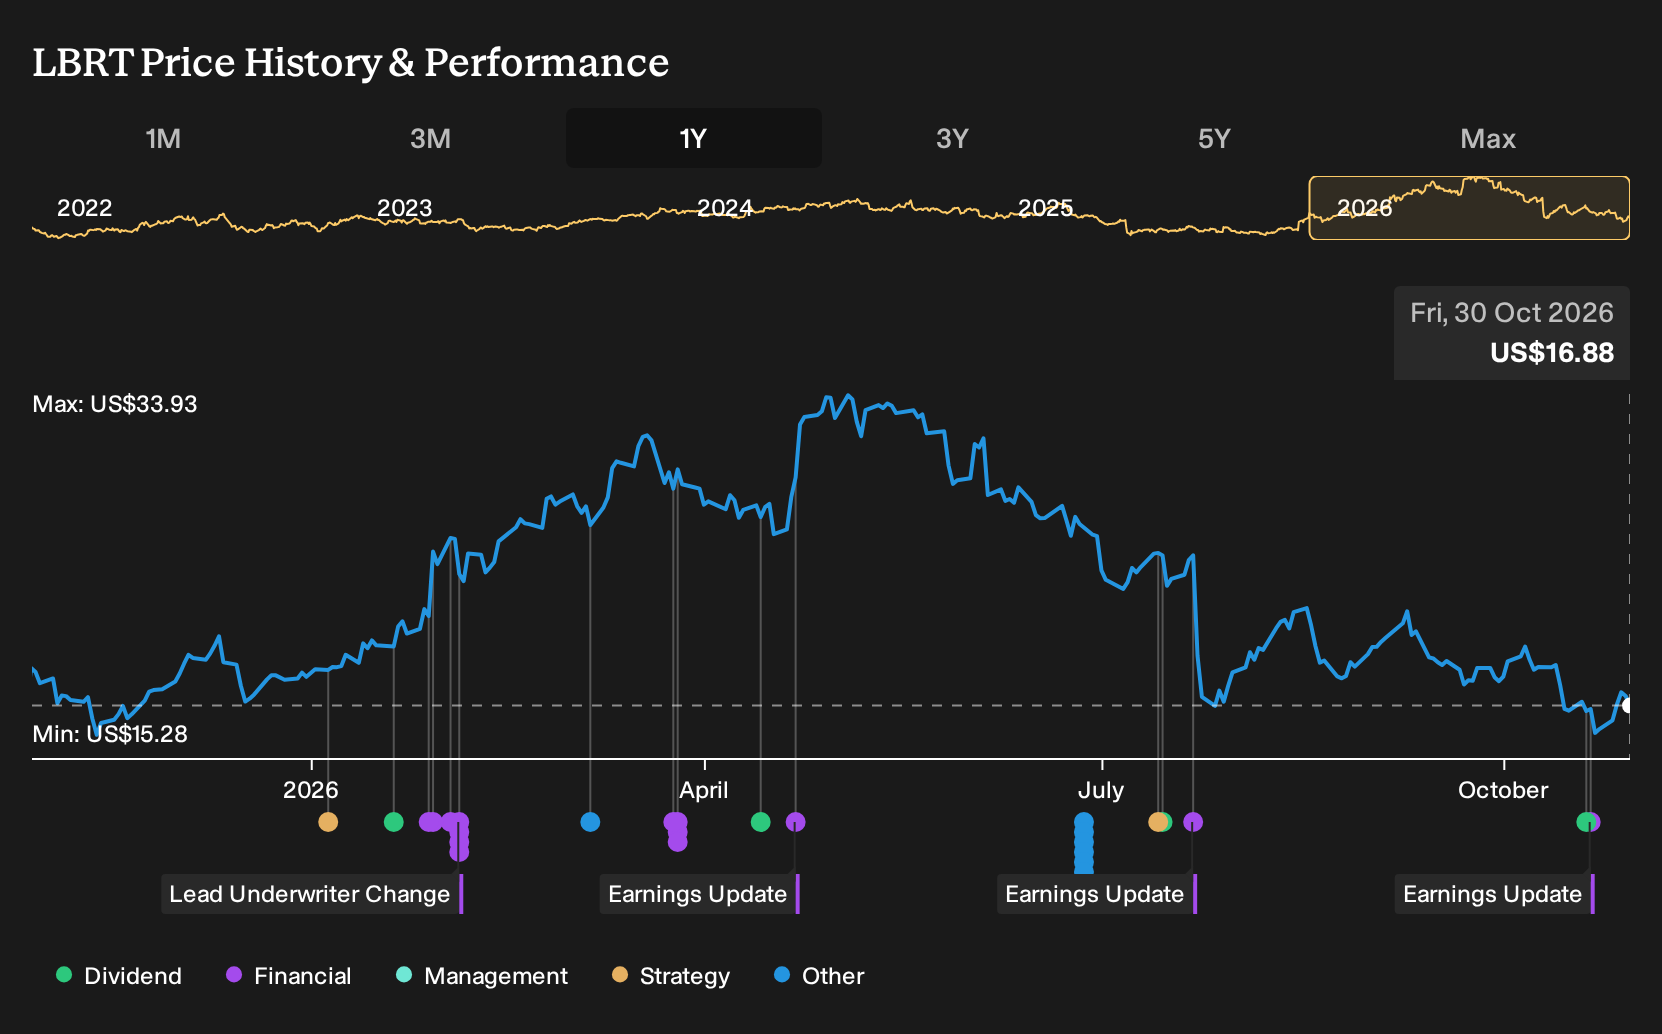
- Liberty Energy reported third quarter 2026 sales of US$1,196.16 million and a net loss of US$39.06 million, while also declaring a US$0.10 per share dividend payable in December 2026.
- The combination of higher sales alongside a swing to loss and a continued cash dividend puts Liberty Energy's capital allocation and earnings quality in sharp focus for investors.
- This raises questions about how Liberty Energy's earnings miss against last year could reshape the overall investment narrative for the business.
Liberty Energy Investment Narrative Recap
To own Liberty Energy, you need to believe the heavy 2026 capex for the 3 GW power build out and a tight frac market can eventually support healthier earnings and cash generation. The latest quarter challenges that belief in the near term. Sales were US$1,196.16 million, but the business swung to a net loss of US$39.06 million, which keeps execution risk front and center.
The key near term catalyst remains proving that completion services can stay utilized and priced well enough to fund the power portfolio without eroding balance sheet flexibility. The biggest current risk is that higher spending and weaker earnings quality, with margins already under pressure, limit financial room if frac pricing or activity softens from here.
The US$0.10 per share dividend declared for December 2026 is the announcement that matters most against this backdrop. It signals Liberty Energy is still returning cash to shareholders despite a quarterly loss and higher capital needs. For you as an investor, that puts the focus squarely on whether future operating cash flow can comfortably cover both capex and payouts.
Dividend sustainability already screens as a concern, with prior analysis flagging that distributions are not well covered by earnings or free cash flow. Layer the third quarter loss and US$1.5b 2026 capex plan on top of that and the payout becomes a real test of discipline. The way management balances that dividend against funding the 3 GW build out will likely shape how much confidence investors place in the whole Liberty Energy catalyst story.
Liberty Energy's narrative projects US$6.2b revenue and US$575.2 million earnings by 2029. This assumes 12.0% yearly revenue growth and an earnings increase of about US$535 million from US$40.3 million today.
Uncover why Liberty Energy's fair value indicates a 60% potential upside to its current price, which could narrow quickly if sentiment turns back in Liberty Energy's favor.
Exploring Other Perspectives
One alternate angle on Liberty Energy focuses on the risk that its 3 GW power build ties up capital for years before customers show up. The most bearish analysts were penciling in only about US$5.5b of 2029 revenue and roughly US$510.9 million of earnings, prior to this quarter. That is a much more cautious story. Use this earnings miss and the fresh dividend news as a prompt to compare that pessimistic setup with your own expectations and explore how views might shift as new data lands.
Explore 4 other Liberty Energy fair value estimates, including one that suggests as much as 48% downside from the current price!
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider your own analysis carefully.
- A great starting point for your Liberty Energy research is our analysis highlighting 1 key reward and 4 important warning signs that could impact your investment decision.
- See our latest analysis for Liberty Energy. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Liberty Energy's overall financial health at a glance.
Looking For More Investment Ideas Beyond Liberty Energy?
If Liberty Energy has sharpened your sense of risk and reward, use that same lens on a wider set of opportunities. The Simply Wall St Screener lets you quickly filter for the balance of quality, resilience, and income that best matches your own playbook.
- Prioritizing financial strength and staying power, you can focus on a list of solid balance sheet and fundamentals (25 results) to see which businesses combine robust balance sheets with fundamentals that hold up under closer inspection.
- If you prefer potential mispricings with quality still intact, narrow your search to a 29 high quality undervalued stocks that highlights stocks where underlying cash flows and balance sheets may not be fully reflected in current prices.
- Looking for ideas the market may be overlooking, you can scan a 18 high quality undiscovered gems to find smaller companies with strong fundamentals that have not yet attracted broad attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com