
Is Woolworths Group (ASX:WOW) Fully Priced Following Its First Quarter Sales Update?
Woolworths Group (ASX:WOW) put fresh numbers on the table with its first quarter trading update, reporting A$19,353 million in sales compared with A$18,483 million for the same period last year.
The latest trading update landed alongside a punchy year to date share price return of 36.66%. However, the stock has slipped 3.66% over the past week. Woolworths Group now trades at A$40.22, with a 1 year total shareholder return of 45.19% that far outpaces its 5 year total shareholder return of 17.82%. This indicates that momentum has picked up recently rather than being a slow build over the longer haul.
Contrast Woolworths Group's current momentum with other large retailers by scanning a hand picked 6 resilient stocks with low risk scores that aim to pair dependable balance sheets with steadier share price moves.
After a 1 year total return in the mid 40s and a share price now just above its quoted target, Woolworths Group looks less like an obvious bargain. Does the current valuation still leave enough upside for new buyers?
Most Popular Narrative: 2% Overvalued
The most followed Woolworths Group narrative points to a fair value of A$39.32 using a 7.33% discount rate, slightly below the last close at A$40.22 and suggesting the recent share price already builds in a lot of the good news on execution.
The current valuation, along with this narrative’s view that Woolworths Group is fairly valued with a bullish stance, implies the share price already reflects meaningful success in cost efficiency, digital profitability and earnings from complementary businesses.
The main requirement for this narrative is continued execution on cost savings, logistics automation and value programs, together with managing regulatory scrutiny and mixed performance in New Zealand Food.
See why 86 investors see Woolworths Group as 2% overvalued.
Result: Fair Value of A$39.32 (OVERVALUED)
Still, Woolworths Group faces real pressure if tighter pricing rules and supplier cost hikes squeeze margins, or if the New Zealand food recovery stalls again.
Find out about the key risks to this Woolworths Group narrative.
Another View: Woolworths Group Through The P/E Lens
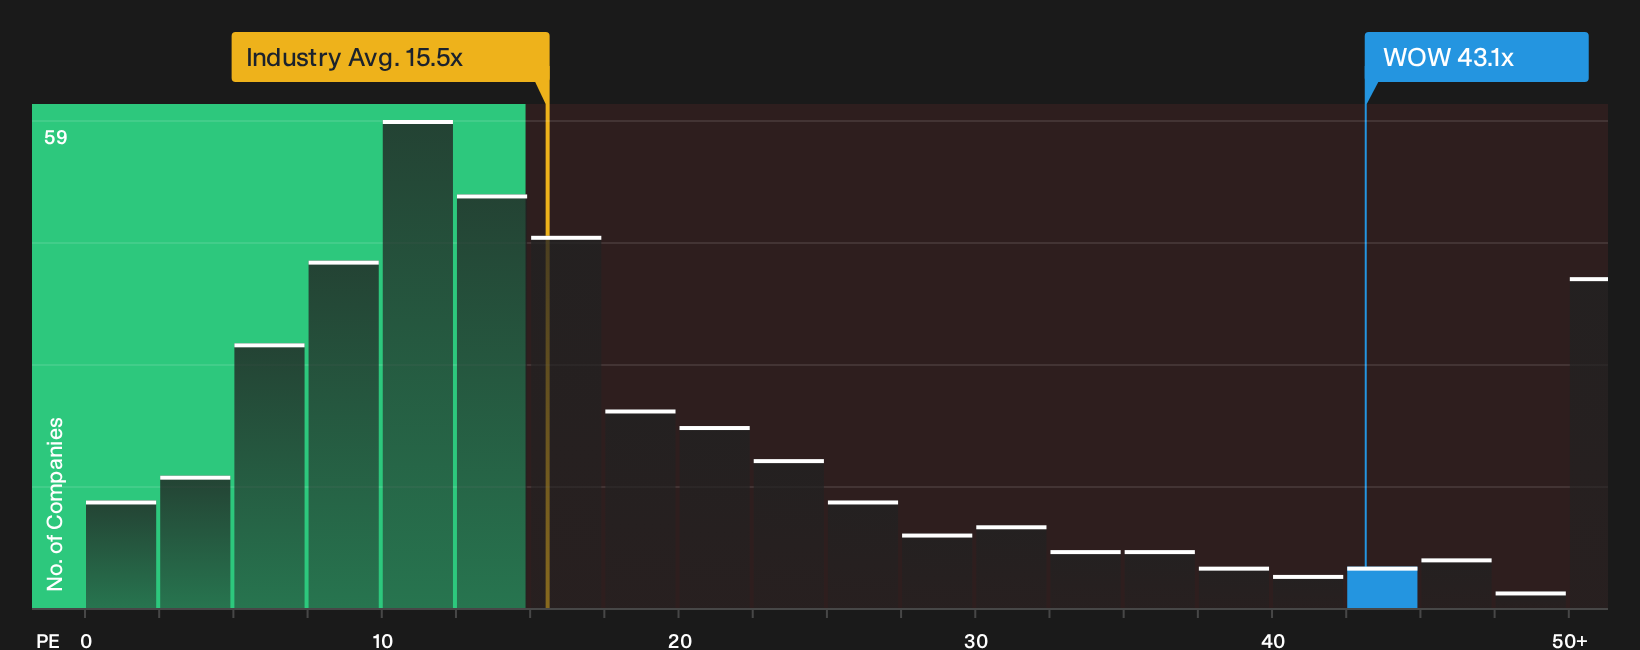
Multiples send a different message. Woolworths Group trades on a P/E of 43.1x, below its peer average of 48.1x, yet well above the global Consumer Retailing mark of 15.3x and a fair ratio of 28.7x. That gap raises a simple question. How much optimism is already in the price?
To pressure test that optimism against hard numbers, take a closer look at what the valuation gap implies for future expectations and risk with See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed signals on Woolworths Group so far, with both concerns and reasons for optimism, mean your own read of the full picture really matters. To weigh both sides quickly, review the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Woolworths Group?
If Woolworths Group already feels priced in, consider broadening your opportunity set. The market rarely hands the most compelling ideas to investors who stop at one stock.
- Focus on quality at a discount by scanning companies that pass stringent value and fundamentals checks using the 1 high quality undervalued stocks.
- Work toward a sturdier core portfolio by focusing on companies with resilient balance sheets and established financial strength through the list of solid balance sheet and fundamentals (12 results).
- Monitor lesser known businesses with strong fundamentals using the 15 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com