
Redwire (RDW) Could Be 35% Undervalued As EnduroSat Deal Lifts Contract Visibility
Redwire (RDW) has signed a memorandum of understanding with EnduroSat that connects its power systems and prime contracting experience with EnduroSat’s high-volume spacecraft manufacturing for European defence and commercial missions.
Redwire’s latest move with EnduroSat arrives after a choppy stretch for the stock, with the share price down 19.6% over the past 30 days and 7.1% year to date. At the same time, the 1 year total shareholder return is 6.6% and the 3 year total shareholder return is very large, suggesting that long term momentum has cooled recently as investors reassess execution risk and contract visibility around its growing project pipeline.
Scan other space and defense contractors benefiting from similar contract momentum with our curated list of 39 power grid technology and infrastructure stocks
The recent pullback in Redwire after strong multi year gains raises a simple question: Are you seeing a reset in sentiment around contract risk, or a closer reflection of what the business is worth today?
Most Popular Narrative: 35% Undervalued
Redwire last closed at $8.39 while the most followed narrative pegs fair value at $12.82. That gap is driving a very different conversation to the recent share price pullback.
The combination with Edge Autonomy and the shift to a scalable space and defense platform is already reflected in year-over-year revenue of US$103.4 million in Q3 2025 and adjusted gross margin of 27.1%. This could support further operating leverage and earnings as cost savings and lean programs flow through SG&A.
See why 42 investors see Redwire as 35% undervalued.
Result: Fair Value of $12.82 (UNDERVALUED)
Still, the narrative around Redwire can shift quickly if government contract awards face delays or if the ongoing adjusted EBITDA losses persist longer than investors expect.
Find out about the key risks to this Redwire narrative.
Another View: What Multiples Say About Redwire
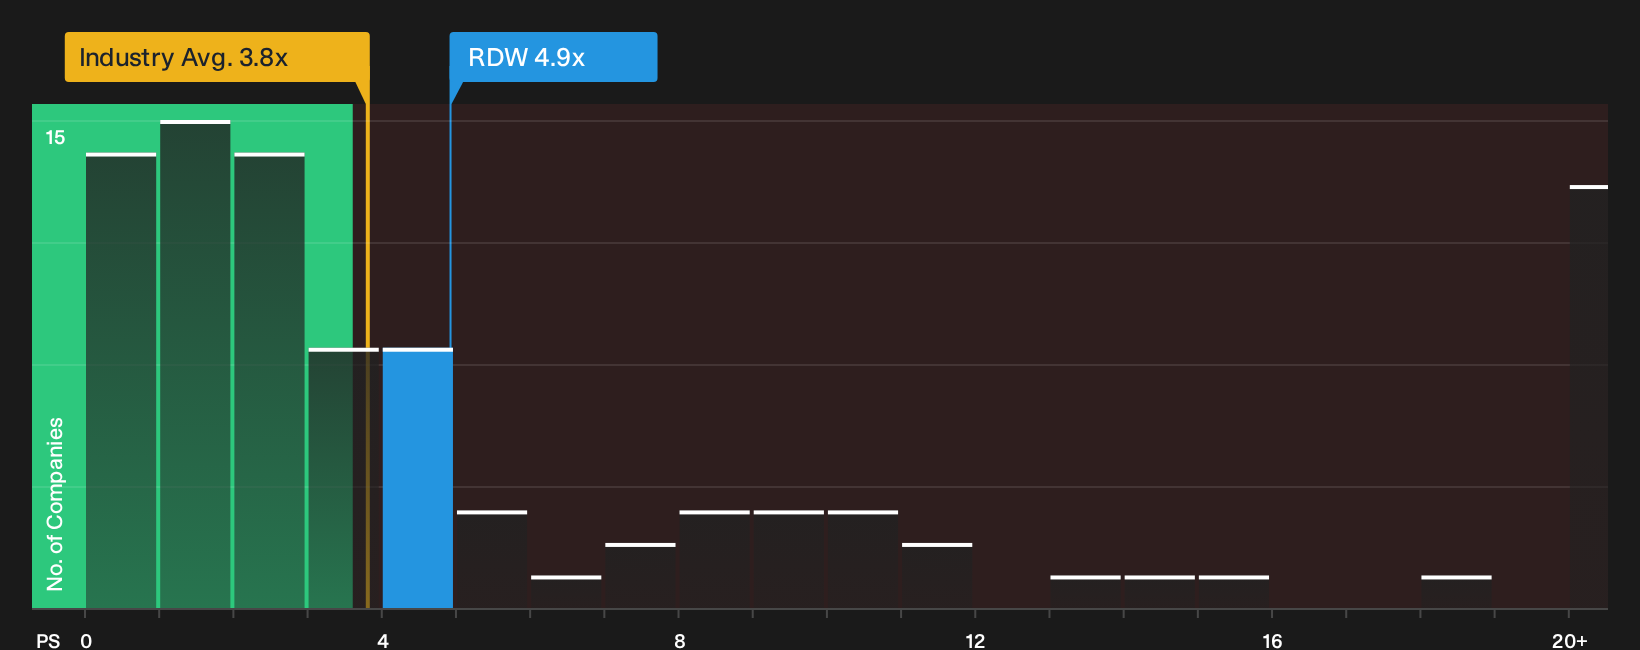
There is a catch. While Redwire looks undervalued against the most popular fair value narrative, the P/S ratio tells a different story. At 4.9x sales, the stock trades richer than the US Aerospace & Defense group at 3.8x and above an estimated fair ratio of 2.6x. That gap implies less margin for error if execution stalls or contract timing slips, so how comfortable are you paying a premium multiple for a business that is still loss making?
For a closer look at how those ratios stack up against peers, and what they might imply for future re-rating risk, see the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Redwire’s mixed signals on valuation and execution risk make it a stock you need to assess with your own framework, not someone else’s quick take. Move fast, examine both the potential upside and the execution questions, then weigh the 2 key rewards and 3 important warning signs.
Looking for more Redwire sized investment ideas?
If Redwire has sharpened your focus on risk and reward, do not stop here. Use fresh ideas from powerful screeners so potential opportunities do not slip past you.
- Target quality at a discount and use the 29 high quality undervalued stocks to find companies where fundamentals and pricing appear out of sync.
- Prioritise resilience by scanning the 30 resilient stocks with low risk scores for businesses with sturdier profiles when conditions turn choppy.
- Hunt for tomorrow’s potential standouts through the 18 high quality undiscovered gems that combine strong fundamentals with lower market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com