
Why Dorman Products (DORM) Is Back In The Spotlight
Dorman Products (DORM) just put fresh numbers on the table, reporting third quarter results that combined higher sales with lower net income and slightly reduced full year guidance for both revenue growth and earnings.
Against that backdrop, Dorman Products shares have been moving higher, with a 7 day share price return of 8.60% and a 30 day gain of 10.94%, suggesting investors are reassessing the outlook despite lower guidance and softer quarterly net income. Over a longer window, momentum looks more measured, with a 1 year total shareholder return of 1.40% compared with a very strong 3 year total shareholder return of 99.60%. This hints that expectations built up over several years and the latest earnings update and guidance revision are now shaping a more cautious, valuation focused phase around the current US$136.01 share price.
Scan beyond Dorman Products and compare this earnings reaction with other aftermarket and auto-related businesses in our hand picked 30 resilient stocks with low risk scores featuring resilient balance sheets and relatively steady risk profiles.
Bulls see Dorman Products as a quality aftermarket supplier coming off a temporary earnings wobble, while bears focus on softer guidance and a big multi year run. Which story does the valuation now support?
Most Popular Narrative: 16% Undervalued
Dorman Products is trading at $136.01 against a widely followed fair value estimate of about $161.63, which frames the current debate around whether the recent guidance cut is already reflected in the price.
The main thing that has to go right is that Dorman Products continues to convert aging fleet demand, new product launches and Heavy Duty share gains into consistent volume and margin delivery despite softer sales guidance and mixed segment trends.
See why 7 investors see Dorman Products as 16% undervalued.
Result: Fair Value of $161.63 (UNDERVALUED)
Still, the bullish script around Dorman Products can unravel quickly if tariff costs flare up again or if weaker Specialty Vehicle demand drags on margins and guidance.
Find out about the key risks to this Dorman Products narrative.
Another View: Dorman Products Looks Priced Rich On Earnings
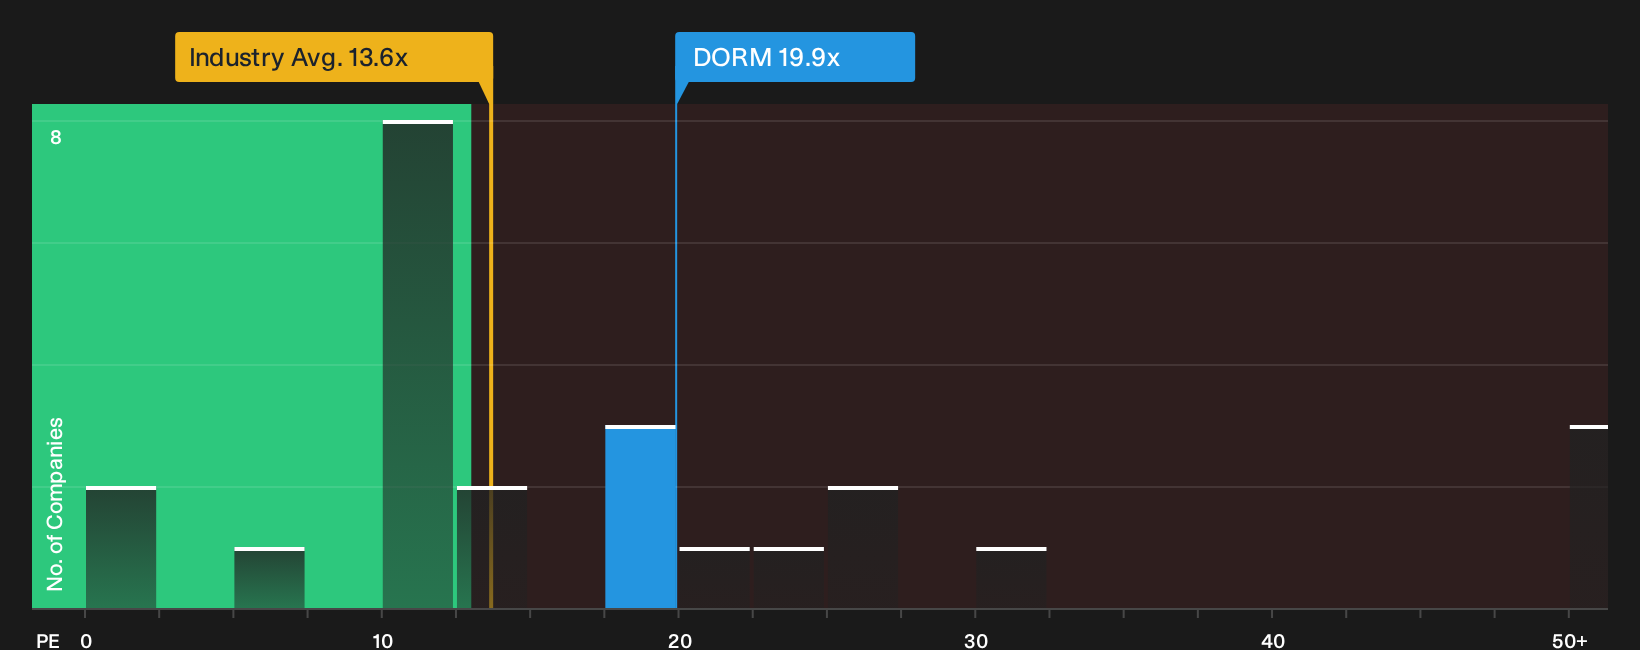
The DCF and fair value work suggest Dorman Products might be modestly undervalued around $136.01. Yet on a simple P/E lens it looks expensive, trading on 19.9x compared with the US Auto Components sector on 16.6x and a peer group average of 9.3x. The fair ratio points to 12.9x as a level the market could move toward. That gap raises a practical question for you: are you being paid enough for the valuation risk if sentiment turns?
For a closer look at how this earnings based view stacks against the rest of the market, take a look at the See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Plenty of opinions on Dorman Products are already baked into the price, but your view should come from the numbers in front of you. Move quickly, stress test the bullish rewards yourself, then decide if the story matches your risk tolerance by checking the 2 key rewards
Looking For More Investment Ideas Beyond Dorman Products?
If Dorman Products has sharpened your focus on valuation and quality, do not stop here. Cast the net wider with a few targeted idea lists that many investors overlook until the opportunity has already moved.
- Target potential value opportunities by scanning a curated 29 high quality undervalued stocks that blend quality fundamentals with prices that may not fully reflect them yet.
- Strengthen the defensive side of your holdings by reviewing a list of solid balance sheet and fundamentals (25 results) that can help anchor your portfolio when conditions get tougher.
- Get ahead of the crowd by combing through 18 high quality undiscovered gems that pair sturdy financials with relatively low investor attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com