
Is NiSource (NI) Undervalued As Earnings Beat Supports Its Long Term Investment Plan?
NiSource (NI) has stepped back into the spotlight after its latest quarterly update, which showed higher net income, firmer earnings per share, and a renewed push behind a long-term, multibillion-dollar investment program.
Recent trading suggests investors are warming to that message. NiSource’s share price has gained 14.28% over the past month and 5.72% year to date, while its 1 year total shareholder return of 8.68% sits alongside a 5 year total shareholder return of 106.72%, indicating long term momentum that has also been evident in the short term.
Scan how NiSource’s latest earnings momentum compares with other regulated utilities by running a quick check on 39 power grid technology and infrastructure stocks shaping the future of grid reliability and energy infrastructure.
After a 14% jump in a month and fresh earnings strength, NiSource now sits at a very different price than it did this summer. Does it make more sense to commit at the current level or wait for a cheaper entry?
Most Popular Narrative: 7% Undervalued
NiSource’s most followed narrative pegs fair value at $47.72, slightly above the latest $44.57 close. This suggests investors are not fully pricing in the company’s long range grid and data center build out.
Strong visibility into multi year, rate based capital expenditure has been updated to a plan through 2033 that supports 9 to 11% consolidated rate base growth and higher long term adjusted EPS CAGR guidance of 9 to 10%. This can compound regulated revenue and earnings as projects enter the rate base.
See why 11 investors see NiSource as 7% undervalued.
Result: Fair Value of $47.72 (UNDERVALUED)
Still, the NiSource story can wobble if regulators push back on its US$28.6b capital plan or if faster electrification makes gas-focused spending more difficult to earn on.
Find out about the key risks to this NiSource narrative.
Another View: NiSource Looks Full on Earnings
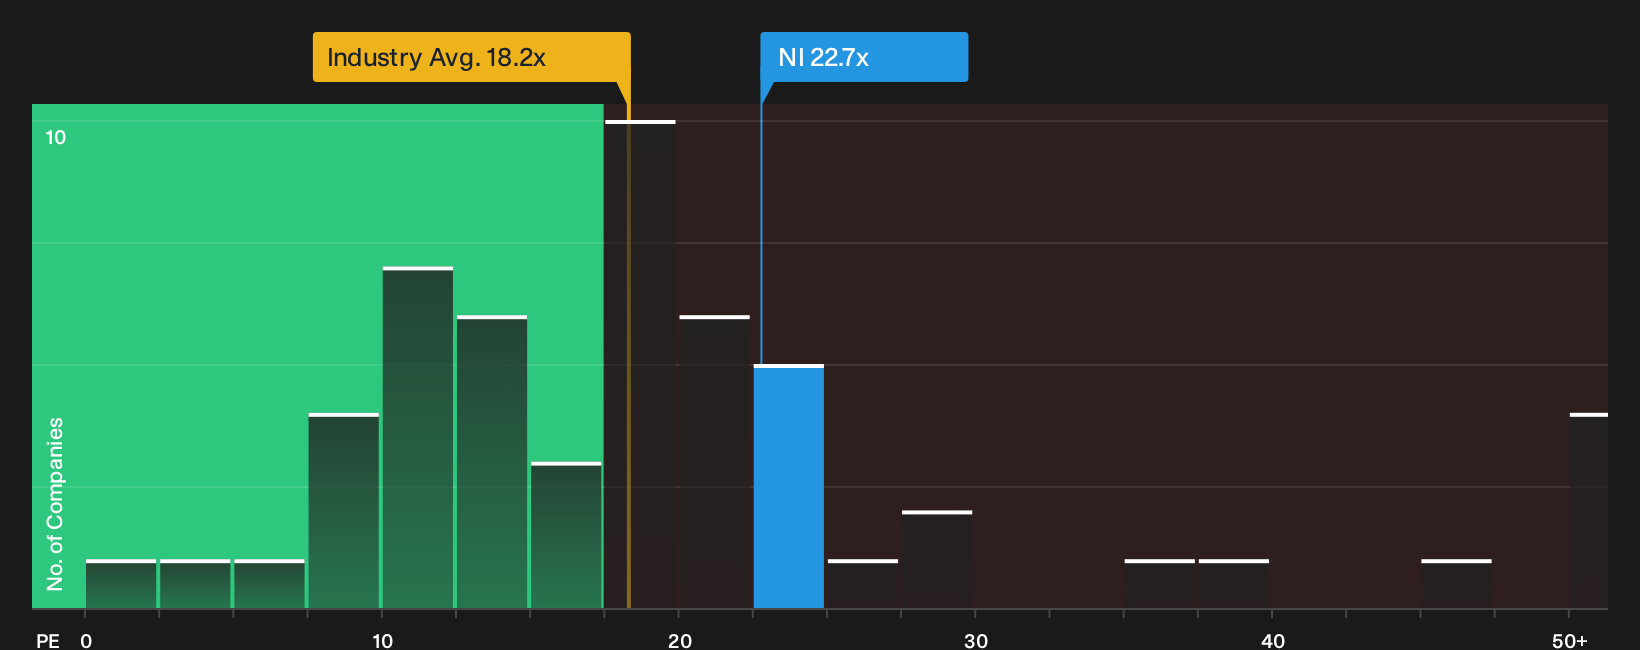
On price versus earnings, NiSource tells a different story. The shares trade on a P/E of 22.7x, above the global integrated utilities average of 18.1x and also above a fair ratio of 21x that the market could eventually lean toward. That gap leaves less room for error if growth or regulation disappoints, so how much valuation stretch are you comfortable with at this stage?
To see how this earnings based view compares with a fuller breakdown of the numbers, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on NiSource so far. Move quickly to review the underlying data, weigh both sides of the story, and decide where you stand with 2 key rewards and 3 important warning signs.
Looking for more NiSource sized investment ideas?
NiSource gives you one story. Do not stop there. Cast a wider net now so you are not chasing the next opportunity after it has already moved.
- Spot potential bargains early by scanning companies that pass tight quality and valuation filters with the 29 high quality undervalued stocks.
- Prioritise resilience by checking businesses with strong finances using the list of solid balance sheet and fundamentals (25 results).
- Target dependable income by reviewing companies built around robust cash returns through the 5 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com