
Did Record Earnings Just Shift AerCap Stock Investment Narrative?
- AerCap Holdings reported third quarter 2026 revenue of US$2,415.33 million and net income of US$948.8 million, raised full year adjusted earnings guidance, and continued active fleet management through US$1.1 billion of asset sales and new 777-300ERSF freighter leases with Turkish Airlines for delivery from 2027.
- The combination of record adjusted earnings, high asset sale activity and expansion of the 777-300ERSF cargo conversion program reflects AerCap Holdings’ focus on tight aircraft supply and diversified cash flow streams across passenger, freight and asset trading.
- The focus now is on how AerCap Holdings’ investment narrative incorporates record adjusted earnings together with new 777-300ERSF leasing commitments.
AerCap Holdings Investment Narrative Recap
To own AerCap Holdings, you need to believe its scale, tight aircraft supply and diversified fleet can keep driving high utilization and lease yields, even as reported net income and margins move around. The near term swing factor is how long asset sale gains and maintenance income stay strong enough to offset pressure on reported earnings.
The biggest operational risk right now is a squeeze on airline profitability from higher fuel costs or weaker traffic, which could soften demand for older jets and compress gains on sale. Recent earnings, guidance and cargo expansion support the existing thesis rather than materially changing it.
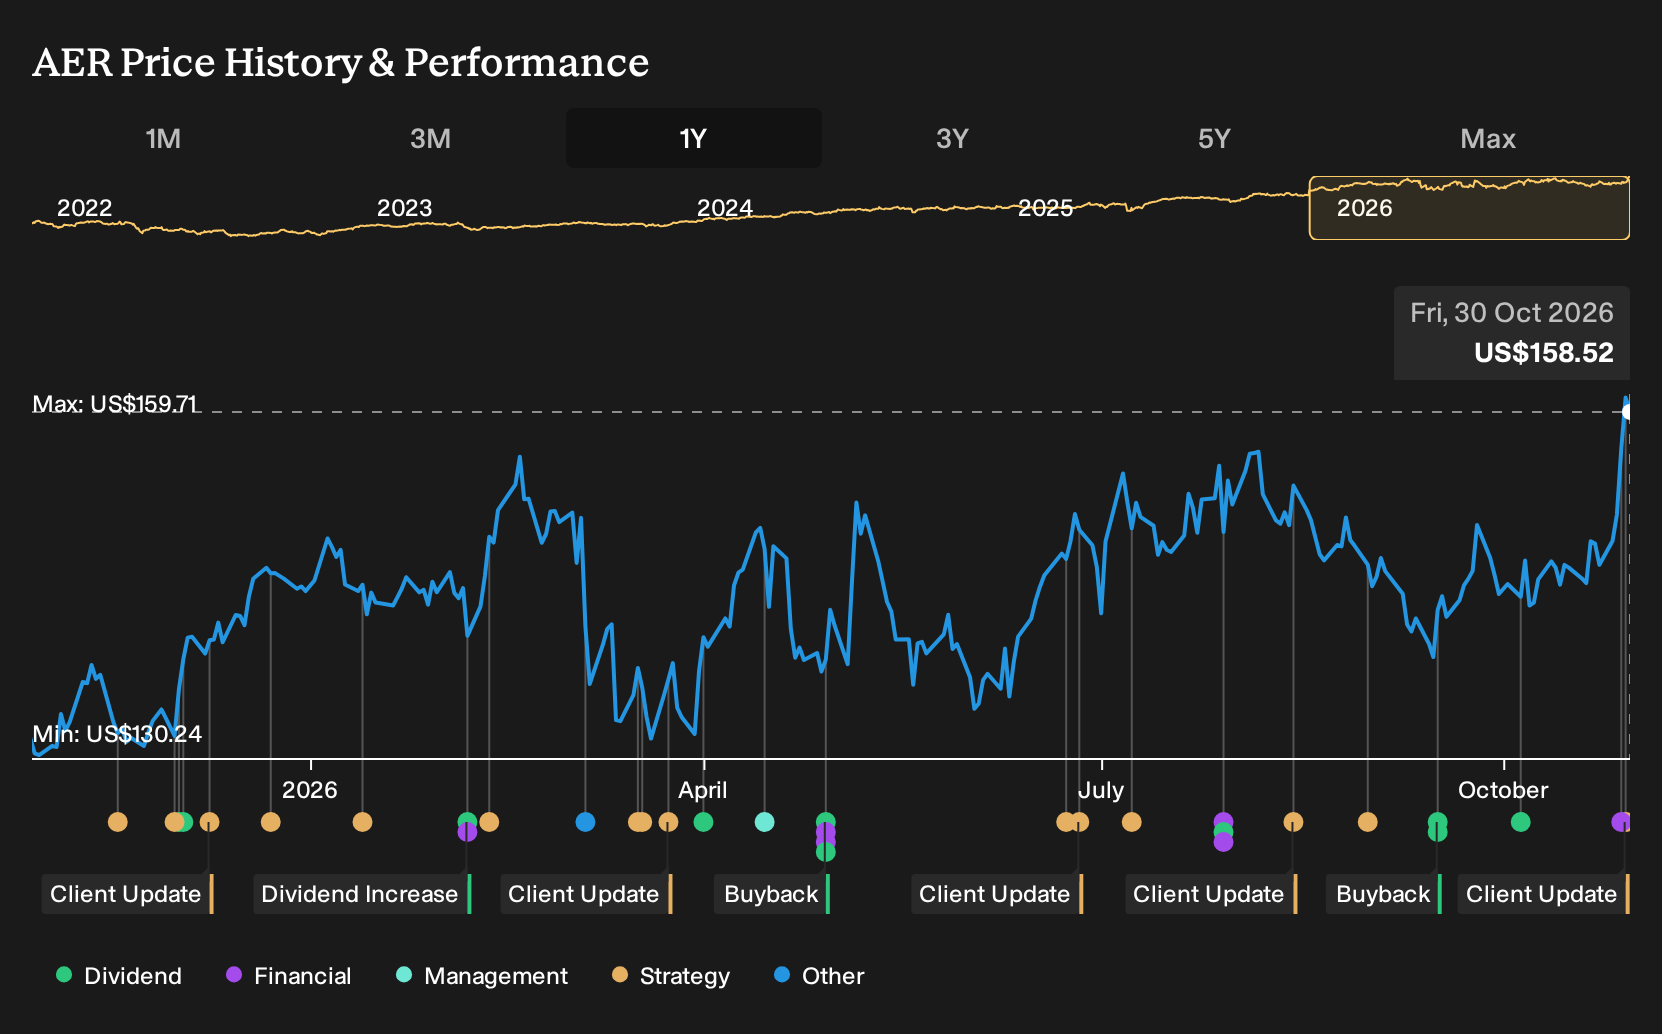
The most relevant update is AerCap Holdings’ record third quarter 2026 adjusted earnings and higher full year guidance, supported by US$2,415.33 million of revenue and US$948.8 million of net income. That performance, combined with a 22% adjusted return on equity and over US$1.1b of asset disposals, keeps the focus on how repeatable sale gains and maintenance income really are.
For you as a shareholder, the key question is whether AerCap Holdings can keep recycling aircraft at attractive prices while deploying cash into new leases, for example through the 777-300ERSF program. If gains on sale normalise or lease extension rates soften, the valuation could be vulnerable, especially with expectations already framed around high execution and ongoing capital returns.
AerCap Holdings' current earnings are about US$3.1b, with analysts forecasting revenues of US$8.3b and earnings of US$2.3b by 2029. This outlook assumes revenue will decline by 2.9% per year and implies an earnings decrease of roughly US$0.8b from earnings today to the 2029 consensus level.
Uncover how AerCap Holdings' fair value indicates an 18% potential upside to its current price before the market closes that valuation gap.
Exploring Other Perspectives
You are not short of opinions on AerCap Holdings. Two fair value estimates from the Simply Wall St Community cluster between about US$109 and US$187, which is a wide span for private investors using their own models. When you layer on the recent 777-300ERSF lease deals and any prolonged jet fuel squeeze, you can reach very different conclusions about earnings resilience. Use that spread as a prompt to review several community viewpoints, not just one headline number.
Explore another AerCap Holdings fair value estimate, including one that suggests as much as 18% upside from the current price.
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your AerCap Holdings research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for AerCap Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate AerCap Holdings' overall financial health at a glance.
Looking for more investment ideas beyond AerCap Holdings?
If you want to stress-test your AerCap Holdings view against other opportunities, use the Simply Wall St Screener to line up companies by quality, balance sheet strength and risk profile in a few clicks.
- For investors who want potential upside with fewer red flags on fundamentals, scan a curated 30 resilient stocks with low risk scores that can help you focus on businesses with more resilient profiles.
- If you care most about financial strength and staying power, filter for companies using a list of solid balance sheet and fundamentals (25 results) that keeps weaker balance sheets out of your shortlist.
- When you are hunting for ideas that the crowd might be missing, start with a 18 high quality undiscovered gems to surface lesser known companies with strong underlying numbers.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com